
Bloom Energy Stock Rallies as Barclays Turns Bullish on California Power Partnership
Surging demand for clean, on-site power generation is driving major revaluations across the alternative energy sector. As grid constraints intensify, strategic utility partnerships and accelerating customer deposit pipelines signal robust institutional confidence in micro-grid fuel-cell infrastructure to support power-intensive industrial operations. Reflecting this powerful sector tailwind, Bloom Energy (BE) stock recently surged following a Barclays upgrade to “Overweight” and a major power development deal in California.
Bloom Energy develops and manufactures solid-oxide fuel-cell systems that generate reliable, on-site electricity for businesses, data centers, and other energy-intensive operations. The company's distributed power solutions are attracting growing attention as artificial intelligence (AI) infrastructure expands and demand for dependable electricity increases.
Bloom Energy Stock Under Pressure
BE stock has delivered substantial gains in 2026, supported by rising demand for on-site power generation, growing data-center electricity requirements, and strong business momentum. Shares have gained approximately 99% year-to-date (YTD), significantly outperforming the broader market.
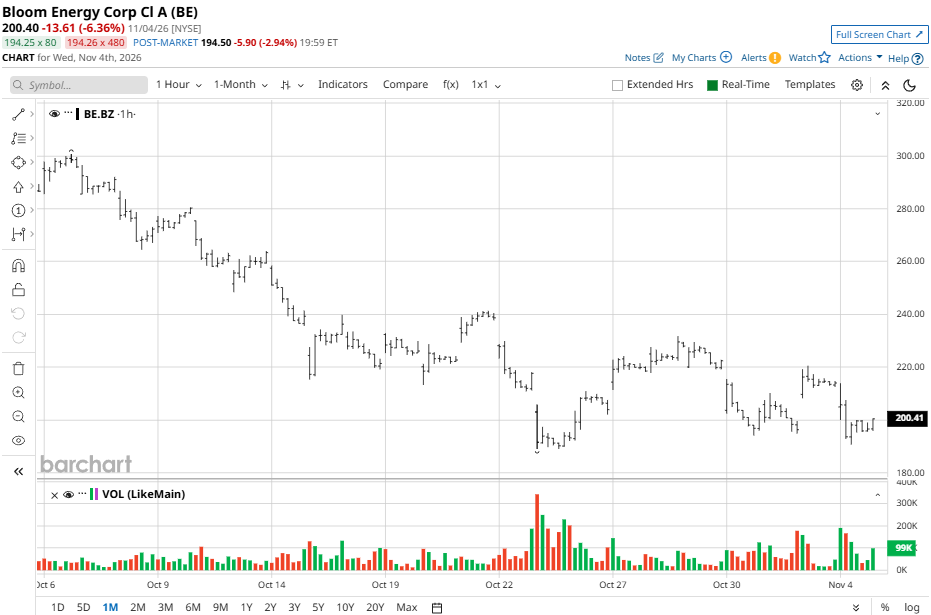
However, the rally has been accompanied by considerable volatility. BE shares recently came under pressure, down approximately 41% over the last month and trading well below the 52-week high of $351.28.
Bloom Energy Presents Record Results
Bloom Energy reported record third-quarter fiscal 2026 revenue of $1.24 billion, representing a 138% year-over-year (YOY) increase and comfortably exceeding Wall Street's estimate of approximately $1.07 billion. Non-GAAP diluted EPS reached $0.94, compared with analysts' expectations of $0.69 and $0.15 in the year-ago quarter. Meanwhile, GAAP diluted EPS came in at $0.78 compared with a loss of $0.10 a year earlier, reflecting a significant improvement in profitability.
The Q3 financial performance also showed considerable margin expansion. Gross margin increased to 33.8%, up from 29.2% in the prior-year quarter, while non-GAAP gross margin improved to 34.5%. Operating income climbed to $225.4 million from $7.8 million a year earlier, and non-GAAP operating income reached $285.7 million. Net income attributable to common stockholders was $250.3 million, compared with a net loss of $23.1 million in Q3 2025. Product revenue was particularly strong, rising 179% to approximately $1.07 billion.
Looking ahead, management raised its full-year 2026 revenue guidance to $4.4 billion to $4.6 billion. The company also expects non-GAAP gross margin of approximately 34%, non-GAAP operating income between $960 million and $1.03 billion, and non-GAAP EPS of $3.10 to $3.40. Management attributed the improved outlook to strong customer demand and business execution, while highlighting the expanding need for reliable, on-site electricity across data centers and other industries.
BE Stock Rallies on Barclays Upgrade and 1 GW California Power Partnership
Bloom Energy shares surged 9% on Nov. 3 after Barclays upgraded the stock from “Equal Weight” to “Overweight” and assigned a $289 price target, citing stronger-than-expected demand for its fuel-cell technology. The bullish assessment coincided with a potential partnership between Bloom and California Resources Corporation to evaluate at least 1 gigawatt of fuel-cell power capacity combined with carbon capture and storage in California.
Barclays analyst Christine Cho highlighted a sharp increase in customer deposits, which climbed from $78 million at the end of 2025 to $661 million in Q3 2026, including a roughly $300 million sequential increase. Assuming typical upfront deposits of 10% of contract value, just that quarterly increase could indicate at least $3 billion in underlying contracts. Barclays believes rising customer commitments, manufacturing expansion, and supplier investments point to a strengthening demand pipeline for Bloom's on-site power solutions.
Should You Buy BE Stock?
Bloom Energy's recent Barclays upgrade and its potential 1 GW California power partnership highlight growing confidence in its fuel-cell technology and long-term demand prospects. These developments could strengthen its position in the expanding market for data-center power and low-carbon energy solutions.
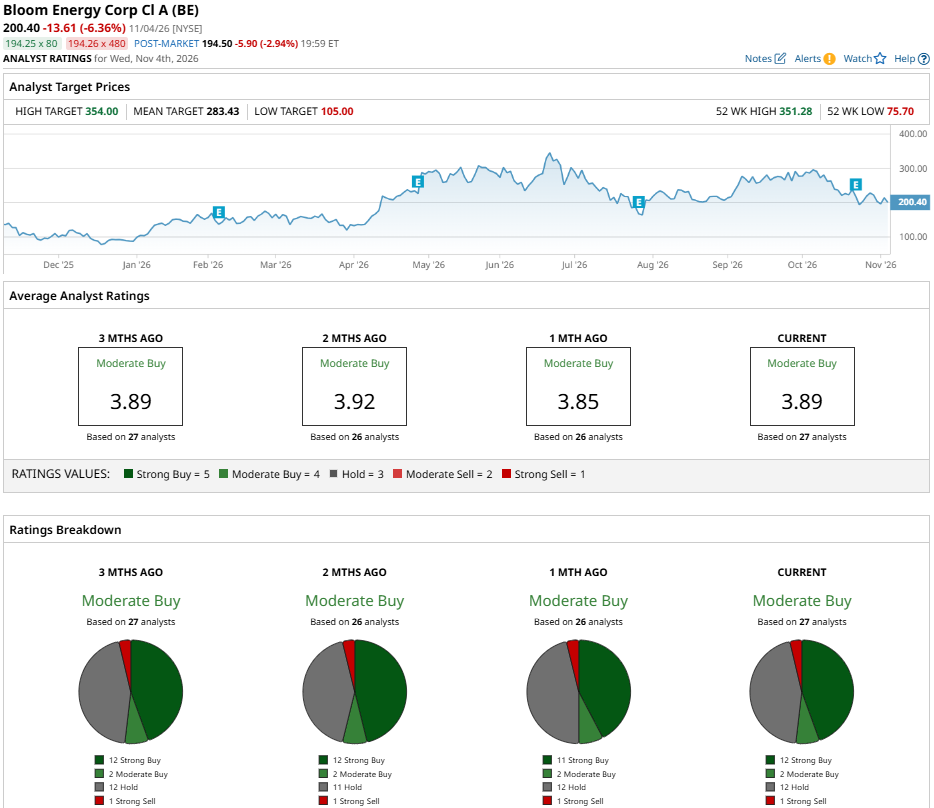
Wall Street currently maintains a consensus “Moderate Buy” rating for BE stock. Among 27 analysts with coverage, 12 have a “Strong Buy” rating, two have a “Moderate Buy” rating, 12 have a “Hold,” and one analyst has a “Strong Sell," indicating optimism alongside some caution. The mean price target of $283.43 implies potential upside of 64% from current levels.
On the date of publication, Ruchi Gupta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.