
Albemarle (ALB) Stock Still Looks Underpriced After A 62% Five Year Fall
Albemarle has had a tough longer term ride, with deep share price declines over several years followed by sharp swings more recently, and that leaves investors asking whether the current valuation still lines up with what its earnings can support. With fresh company news and a volatile return profile, the question now is how much of the current story is already reflected in the US$99.25 share price.
- The stock has fallen 61.8% over the past 5 years, which puts the focus squarely on whether the underlying earnings justify staying invested or stepping in at today's level.
- Recent company updates point to stronger profitability and activity in its lithium focused business lines, which can influence how durable investors expect Albemarle's margins and future cash generation to be.
- The analysts covering Albemarle have run their own numbers. See what analysts think Albemarle's shares could be worth.
The stock's next move may depend on whether its current earnings profile makes the recent share price look well supported or stretched.
If you want a clearer benchmark for Albemarle's earnings story and share move, it can help to line it up against 39 high quality undervalued stocks.
Is Albemarle a Bargain on Earnings?
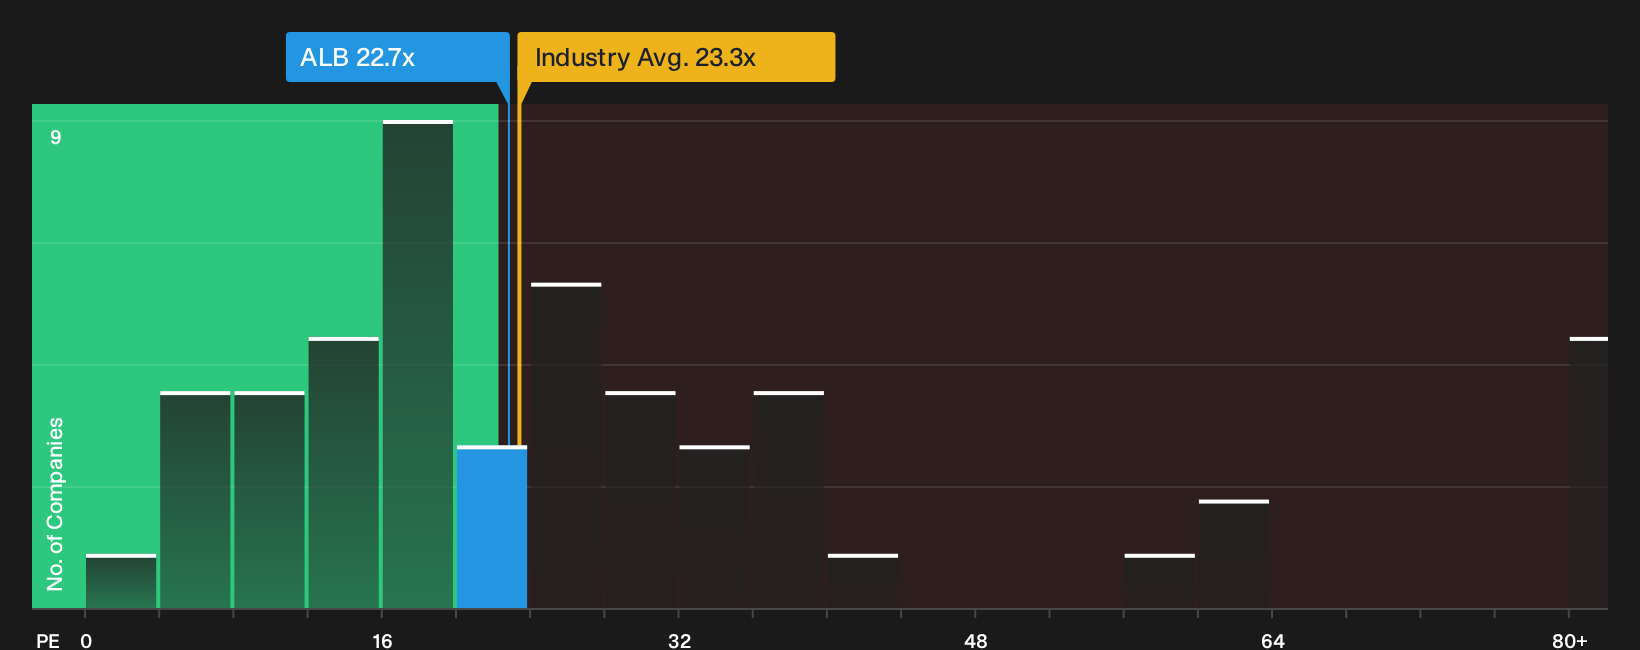
The P/E ratio fits Albemarle because investors are focused on how much they are paying for each dollar of current earnings. At a P/E of 22.7x, the stock trades slightly above its Chemicals sector peer average of 17.7x and close to the wider industry level of 23.3x, which places Albemarle in the higher priced group on this metric.
Because the stock screens below the more tailored fair P/E level implied by its own profile, the current multiple points to Albemarle looking undervalued on earnings relative to what the model suggests might be justified. Despite the strong Q3 2026 update around lithium driven profits, the share price still values those earnings at a discount to that fair P/E marker, which leaves room for investors to debate whether the recent operational strength is fully reflected. Explore the numbers behind Albemarle's P/E valuation.
The Albemarle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Albemarle's P/E puzzle leaves off, spelling out the earnings, margin and growth conditions that would need to play out for the stock to be worth materially more or less than it is today, and they sit on the Community page. Rather than using one headline multiple, each scenario lays out the moving parts behind its fair value view so you can compare those assumptions with Albemarle's reported results over time.
Community views on Albemarle are split between those who see margin resilience creating upside and those who think execution issues already cap the story.
Bull case: 36% undervalued
"With ~50% of sales volumes locked under long-term agreements with major Western OEM and battery customers, Albemarle benefits from enhanced revenue stability and reduced cyclicality…"
Discover why this Narrative puts Albemarle at 36% undervalued.
Bear case: 8% overvalued
"Bearish analysts expect Albemarle to face pressure on lithium pricing power as alternative battery chemistries and new supply projects keep a lid on how much value the company can capture from growing demand…"
Explore why this Narrative puts Albemarle at 8% overvalued.
One more Albemarle question before you act
Before leaning too hard on today’s P/E and narrative debate, it can help to see where professional analysts think Albemarle’s earnings profile could sit a few years from now, and how that lines up with today’s pricing. Explore where analysts expect Albemarle to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com