
Skyworks Solutions (SWKS) Earnings And Guidance Put Its Valuation Back In Focus
Why Skyworks Solutions Stock Is Back In Focus
Skyworks Solutions (SWKS) has jumped back onto investor watchlists after reporting fourth quarter and full year results on November 3, along with fresh revenue guidance for the December quarter.
The semiconductor group posted fourth quarter sales of US$1.05b compared with US$1.10b a year earlier, while net income declined to US$23.4m from US$141.4m. Earnings per share from continuing operations also moved lower year over year on both a basic and diluted basis.
Skyworks Solutions has seen momentum cool in the past week, with a 7 day share price return of down 6.15%. This comes even though the 90 day share price return of 16.38% and year to date share price return of 27.63% point to improving sentiment compared with the longer term 5 year total shareholder return of down 42.49%.
Scan how Skyworks Solutions stacks up against other chip makers by running the curated 52 AI infrastructure stocks that are catching fresh attention after earnings and guidance shifts.
After Skyworks Solutions shares rallied over the past quarter despite weaker headline earnings, the real tension is simple. Does the current valuation still skew the risk reward toward new buyers, or has most of the easy upside been used up already?
Most Popular Narrative: 4% Overvalued
Skyworks Solutions last closed at $82.19 while the most followed narrative pegs fair value at $78.68, so the story hinges on whether the merger and RF opportunity truly justify that premium.
The planned Qorvo merger is framed around creating a combined mobile business of roughly US$5.5b and a non mobile business of about US$2.5b to US$2.6b, with at least US$500m of cost synergies over 24 to 36 months and a long term model of 50% to 55% gross margin and 30% to 35% operating margin. This could materially lift net margins and earnings power that current pricing may assume will be delivered in full.
See why 57 investors see Skyworks Solutions as 4% overvalued.
Result: Fair Value of $78.68 (OVERVALUED)
Still, two pressure points could flip that overvaluation story: smoother Qorvo integration unlocking the planned US$500m synergies, and continued strength in AI data center demand.
Find out about the key risks to this Skyworks Solutions narrative.
Another View: Cash Flows Tell A Different Skyworks Story
While analyst narratives frame Skyworks Solutions as about 4% overvalued at a fair value of $78.68, the SWS DCF model points in the opposite direction. It puts fair value closer to $154.17, which implies the current $82.19 price is trading at roughly a 47% discount. That gap raises a simple question: Is the market overpaying for near term earnings multiples or underappreciating longer term cash generation?
Look into how the SWS DCF model arrives at its fair value.
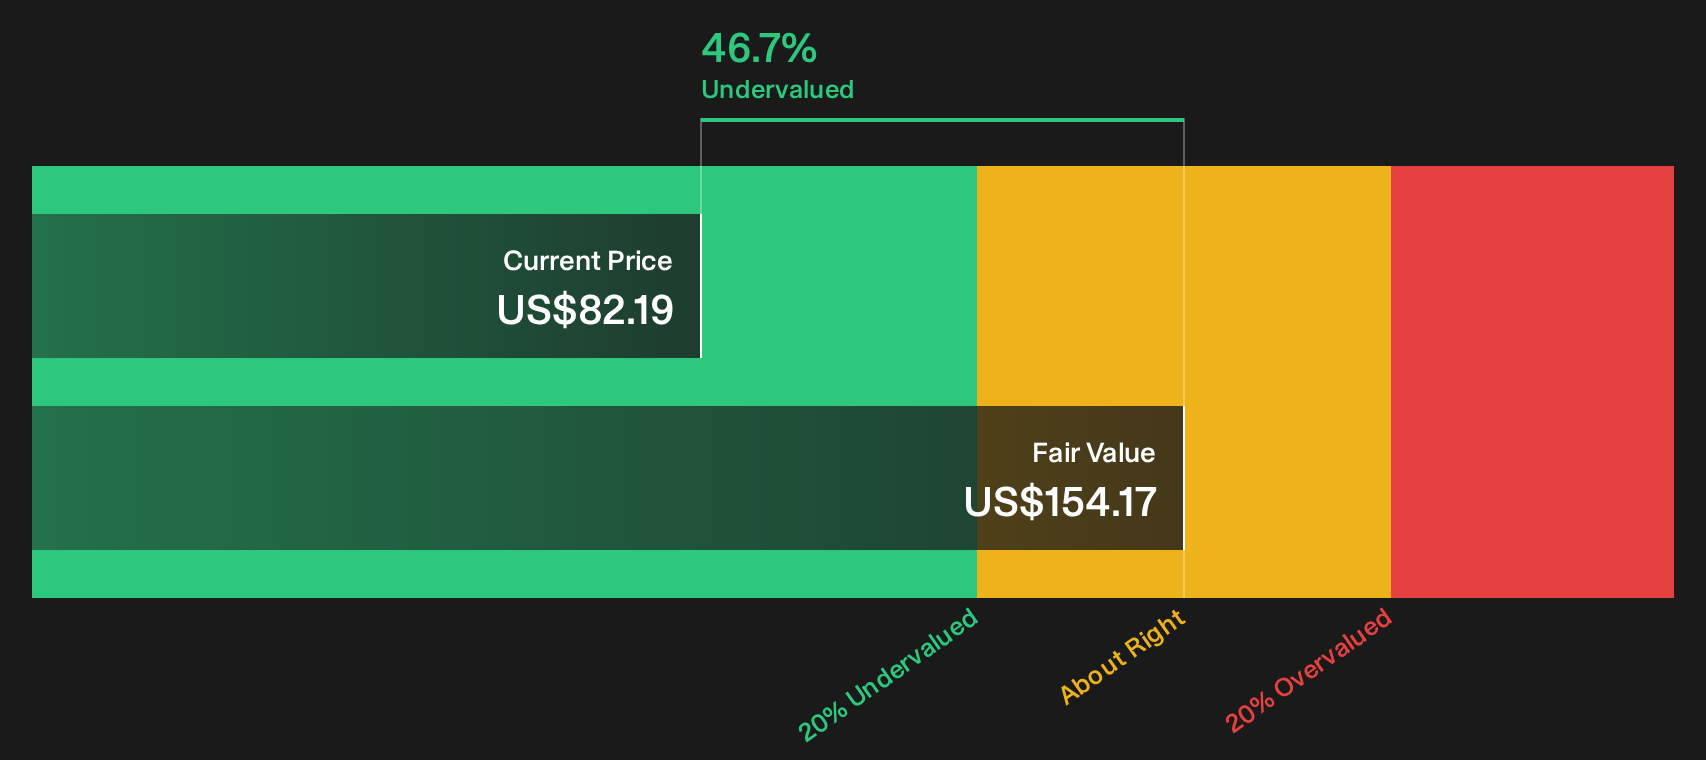
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Skyworks Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views are already forming around Skyworks Solutions, with some investors focused on the upside story and others watching the red flags more closely. Move quickly, review the underlying data, and then weigh both sides with the help of 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Skyworks Solutions?
If you only stop at Skyworks Solutions, you risk missing other opportunities with different return drivers, income profiles, and balance sheet strengths that could suit you better.
- Target resilient cash generators by checking companies with strong fundamentals in the list of solid balance sheet and fundamentals (24 results) that can help anchor a more balanced portfolio.
- Hunt for potential mispricing by scanning the 39 high quality undervalued stocks that combine quality financials with prices that may not fully reflect their fundamentals.
- Build a steadier income stream by reviewing the 8 dividend fortresses that focus on higher yields backed by more robust underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com