
Bloom Energy (BE) Faces Election Driven AI Fears As NTT Deal Keeps Undervalued Story Alive
Bloom Energy (BE) is back in the spotlight after a sharp selloff tied to Democratic election results, which raised questions about future AI data center approvals and energy policy.
Over the past month, Bloom Energy has seen sentiment swing hard, with a 30 day share price return of down 40.53% and a 7 day move of down 14.73% as investors reacted to election driven worries about AI data center approvals, even while fresh agreements such as the 900 megawatt NTT DATA rollout and the California Resources carbon capture memorandum kept the commercial pipeline in view. Looking past this pullback, the stock still carries a year to date share price return of 75.54%. The 1 year total shareholder return of 28.13%, along with the very large 3 year and 5 year total shareholder returns, indicates that long term holders have already experienced a powerful move and that shorter term momentum has recently cooled.
Spot similar AI power plays reacting to policy headlines by scanning our hand picked 52 AI infrastructure stocks alongside Bloom Energy.Bloom Energy looks like a real business win, with multi gigawatt deals and rising guidance, yet the stock has just been knocked back hard. Is the current share price a fair reflection of what investors already own?
Most Popular Narrative: 55% Undervalued
On the numbers, Bloom Energy closed at $173.24, while the most followed narrative on the stock pegs fair value at $386.10. This frames the recent selloff as a gap between sentiment and what some investors think the business is worth.
The Bloom Energy story is still early days. Wall Street cannot seem to comprehend that so many areas for their growth, international, other market segments, even personal or community power (where they started) are largely untapped.
The main constraint on their opportunity is plain and simple ignorance.
See why 45 investors see Bloom Energy as 55% undervalued.
Result: Fair Value of $386.10 (UNDERVALUED)
Still, that bullish Bloom Energy narrative runs into real world friction if large customers slow orders or if future energy policy tightens around fuel based power.
Find out about the key risks to this Bloom Energy narrative.
Another View: Bloom Energy Looks Expensive On Earnings
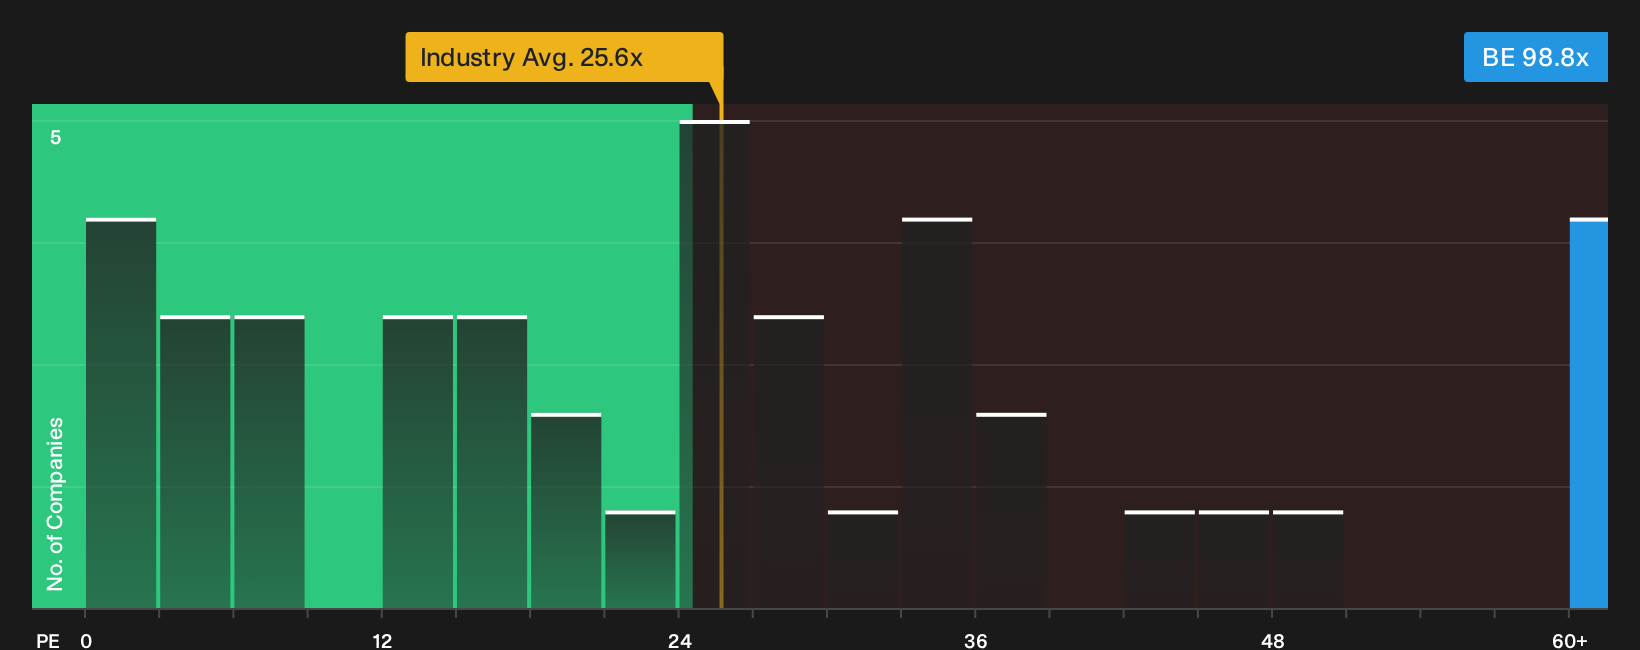
On a cash flow view, Bloom Energy screens as undervalued, yet the earnings multiple tells a very different story. The stock trades on a P/E of 98.8x, versus 25.6x for the US Electrical industry, 58.7x for peers, and a fair ratio of 70.7x that our models suggest the market could move toward. That gap points to real valuation risk if sentiment or growth expectations cool, so how comfortable are you paying this kind of premium for Bloom Energy today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Bloom Energy is split, with sharp recent price swings on one side and long term enthusiasm on the other. Move quickly and weigh the underlying numbers for yourself while the debate is still fresh, then drill into the full picture of 3 key rewards and 3 important warning signs.
Looking for more Bloom Energy style ideas?
Do not stop with Bloom Energy. Use this pullback as a prompt to refresh your watchlist with new possibilities before other investors start combing through the same opportunities.
- Target potential mispricing by scanning a curated set of companies that combine quality and attractive pricing through the 39 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with robust finances and clean balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Spot early stage opportunities by checking a focused pool of smaller stocks with strong underlying fundamentals via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com