
Vertex (VERX) Lifted Guidance And Launched Vertex Sol, Is It Still Undervalued?
Vertex (VERX) just delivered a busy earnings week, lifting its full year 2026 revenue outlook after reporting third quarter results that topped its own guidance and unveiling a new AI powered tax compliance platform.
Vertex’s latest update lands after a sharp shift in sentiment, with the 30 day share price return of 38.52% and 90 day gain of 43.05% reversing an earlier year to date share price decline of 10.15% and a 1 year total shareholder return fall of 12.46%.
Scan beyond Vertex and see how other tax and compliance software players are priced and growing with our hand picked 19 high quality undiscovered gems.
After a 40% style rebound in a few months, while Vertex is still valued at a hefty discount to one intrinsic estimate, it raises a blunt question: Has the real upside yet to play out, or has most of it already passed by?
Most Popular Narrative: 40% Undervalued
Vertex closed at $17.08, while the most followed narrative pegs fair value around $17.15. This uses a 9.06% discount rate to frame cash flows and risk over the next few years.
The April 2026 value creation plan that targets US$60 million to US$70 million of annual cash savings from 2027, combined with Q2 2026 adjusted EBITDA margin of 25% and management’s aim to progress margins toward the high 20s by late 2027, indicates a potential path to structurally higher EBITDA and free cash flow conversion even if revenue growth remains in the low double digits.
See why 13 investors see Vertex as 0% undervalued.
Result: Fair Value of $17.15 (UNDERVALUED)
Still, Vertex’s story can break if large enterprises keep delaying cloud migrations or if heavy AI and e invoicing investment fails to translate into stronger customer adoption.
Find out about the key risks to this Vertex narrative.
Another View: What Vertex’s Ratios Are Saying
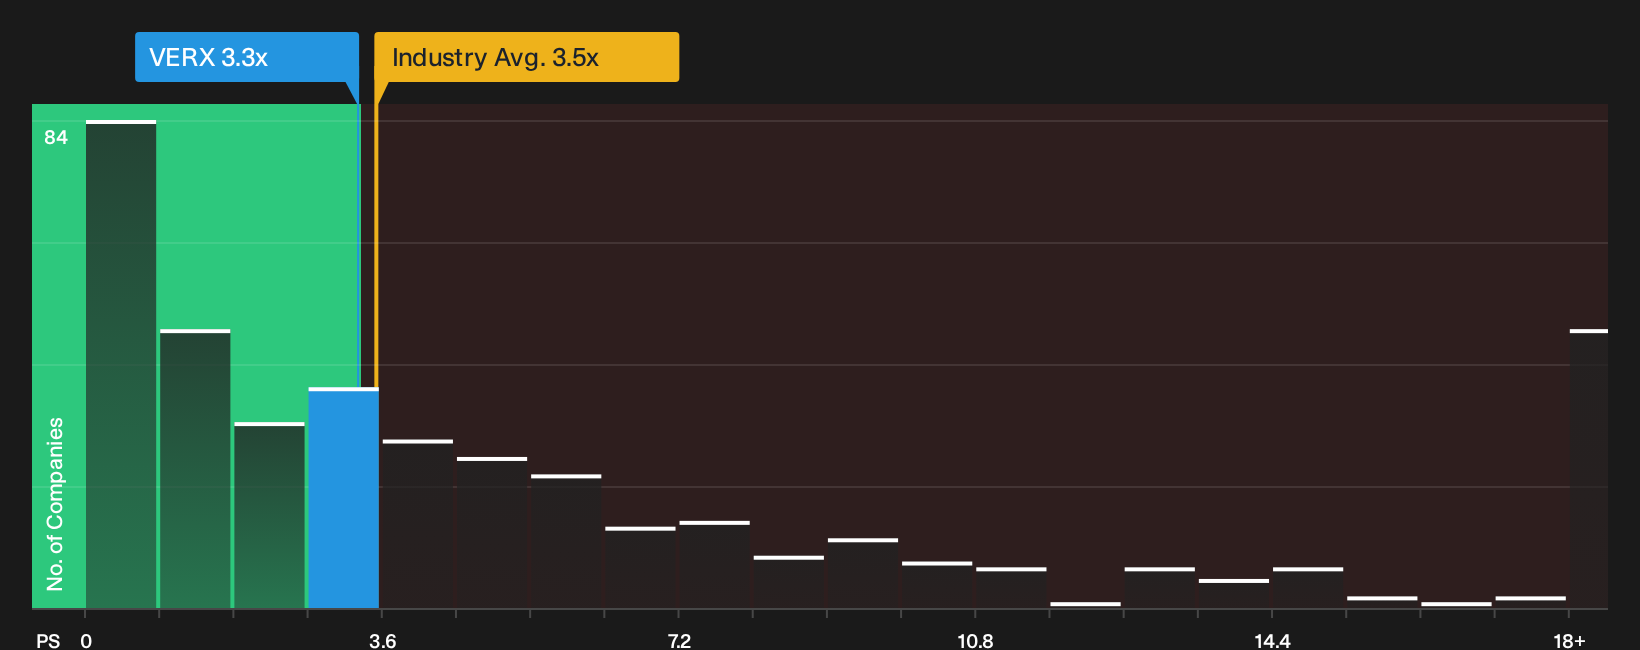
The DCF story presents Vertex as 43.7% below an estimate of its future cash flow value at $30.32, which leans clearly toward undervalued. The simple P/S picture is less generous. At 3.3x revenue, Vertex trades slightly above its 3.2x fair ratio and ahead of peer averages. When the signals conflict, investors need to decide which lens they consider more informative.
To see how those sales multiples line up against both direct peers and the wider US software group, and what that gap could mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all feels mixed, that is the signal to start testing the numbers yourself and to move before the next narrative forms around you. To see what investors are currently optimistic about, review the 2 key rewards
Looking for more investment ideas beyond Vertex?
Do not stop your work with Vertex alone. The real edge often comes from lining it up against a wider field of opportunities that fit your style.
- Target fresh upside candidates by scanning the 19 high quality undiscovered gems that combine quality fundamentals with room for wider investor attention.
- Prioritise resilience by checking the 29 resilient stocks with low risk scores that score well on financial strength and lower overall risk indicators.
- Build a sturdier core to your portfolio by focusing on companies in the list of solid balance sheet and fundamentals (24 results) that keep leverage and liquidity in tighter shape.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com