
The Call Talos Energy Bulls Got Right
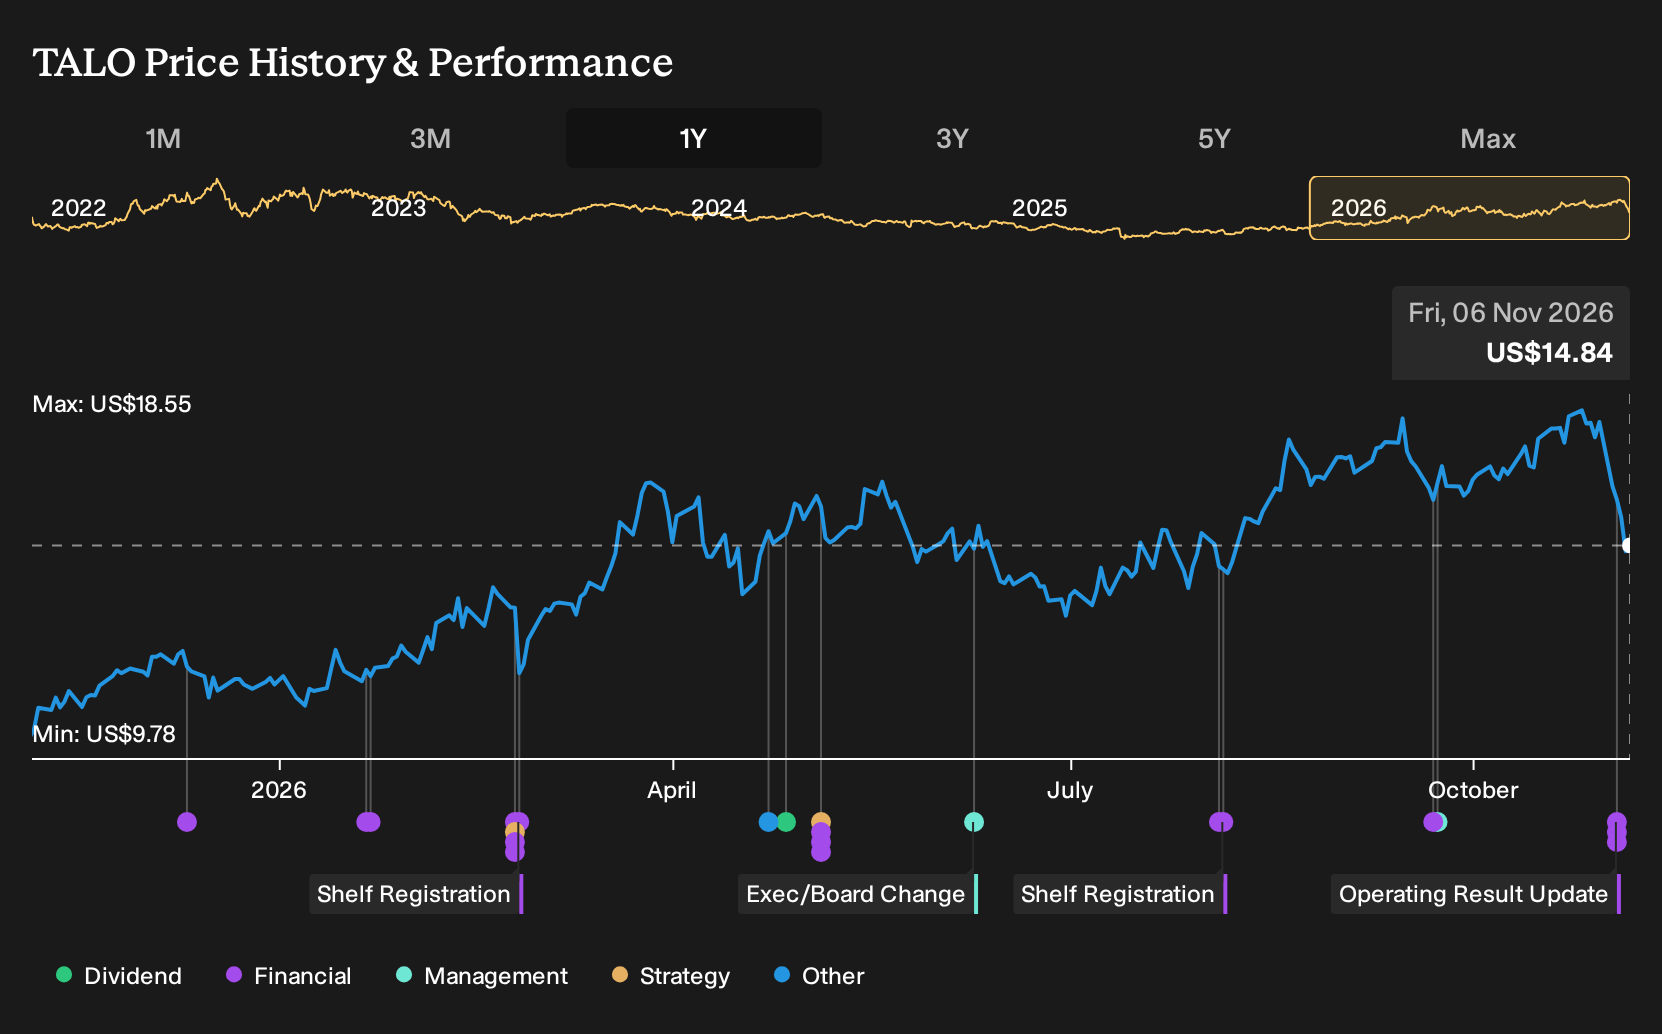
If you only scanned the headlines on Talos Energy this past year, the mix of insider selling, fresh impairments and new offshore deals might have looked like a recipe for whiplash rather than wealth creation. Holding Talos Energy over the past year would have returned 43.0%, including dividends. If you had been weighing a position back on 6 November 2025, how could that outcome square with warnings about Gulf risk, decommissioning costs and unprofitable earnings?
Talos Energy has already moved. See which of 39 high quality undervalued stocks still trade below our estimates.
The Two Talos Energy Stories Investors Had To Compare
The shares cost US$9.78 at the start of the period, and Talos Energy investors were weighing two very different stories about what that price implied.
On the optimistic side, the bullish view pointed to a Fair Value of US$13.17, a price implied by faith in disciplined costs and Gulf of Mexico projects. That narrative leaned heavily on the planned US$100 million per year in efficiency gains and recurring free cash flow improvements.
The more cautious argument anchored to a Fair Value of US$9, a level tied to worries about Gulf concentration and decommissioning burdens. This camp focused on the risk that heavy offshore exploration spending and rising abandonment liabilities could strain future cash generation.
What The Talos Energy Results Actually Tested
The clearest development for Talos Energy was the Shell deepwater asset purchase, which added producing reserves and infrastructure that backed the optimistic focus on high margin Gulf projects and free cash flow. At the same time, Talos still reported a net loss in Q3 2026, even though revenue and net margin both improved compared with Q3 2025, so the profitability part of the bullish story remained unproven. Overall, the evidence cut both ways.
The episode turned on whether efficiency and asset deals could outrun ongoing losses. For other offshore producers, track two things together: watch net margin alongside any acquisition or cost saving story, and check whether reported losses actually move toward break even instead of just scaling with higher production.
What Talos Energy's Price Now Asks You To Believe
Talos Energy now trades at US$14.84. The selected Narrative presents a Fair Value above that level and ties the gap to how well the enlarged Gulf portfolio and efficiency plan support recurring free cash flow and balance sheet strength.
Your question is whether integration of Na Kika and Coulomb really can keep delivering the operational savings and cash generation this Narrative assumes.
"Talos Energy is still executing its targeted US$100 million per year initiative in operational efficiencies and cost reductions, and progress on the Optimal Performance Plan that had already reached more than two thirds of its 2026 target by mid year supports the original view that ongoing savings could support free cash flow, net margins and earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 18% below our estimate - sells high-bandwidth memory and storage that ease AI data-center congestion.
- Company 2 - 30% below our estimate - runs complex gold mines balancing reserve length, operating costs and political risk.
- Company 3 - 42% below our estimate - wins subsea work on brownfield tiebacks and long-duration offshore service agreements.
Those are three of them. See every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com