
Why BeOne Medicines Stock Is In Focus After Earnings Beat And Raised Guidance
- BeOne Medicines reported Q3 2026 revenue of US$1.89b and net income of US$384.71m, with earnings per share from continuing operations materially above the prior year, and raised full year revenue guidance alongside updates on BRUKINSA-driven hematology momentum.
- The FDA’s Priority Review for BRUKINSA plus rituximab in previously untreated mantle cell lymphoma, backed by the Phase 3 MANGROVE trial, highlights how BeOne Medicines is trying to extend a key franchise while simultaneously advancing a broad late stage solid tumor pipeline.
- We will now look at how BeOne Medicines' upgraded guidance and BRUKINSA progress may reshape the existing investment narrative.
Scan how BeOne Medicines fits into the broader healthcare opportunity set by comparing it with 35 healthcare AI stocks that are also focused on late stage pipelines and regulatory catalysts.
BeOne Medicines Investment Narrative Recap
To own BeOne Medicines, you need to believe the oncology platform can keep turning a packed late stage pipeline and strong hematology portfolio into recurring cash generation while operating expenses continue to climb. The Q3 print, with US$1.89b in revenue and US$384.71m in net income, reinforces that the business is currently scaling profitably.
The near term swing factor is still execution around BTK based therapies and key filings, with tacabrutideg timing already pushed to mid 2027. Elevated R&D and commercial spend, plus pricing constraints such as the GENEROUS framework and looming biosimilar pressure on partnered drugs, remain the main operational risks.
The FDA Priority Review for BRUKINSA plus rituximab in previously untreated mantle cell lymphoma now sits at the center of the BeOne Medicines story. It is backed by the Phase 3 MANGROVE study, which met its primary endpoint on progression free survival and will have full data presented at ASH on 13 December 2026.
If that chemo free regimen secures approvals across major markets, it could reinforce BRUKINSA as the anchor of the B cell franchise and support the upgraded 2026 revenue guidance of US$6.9b to US$7.0b. If regulators or prescribers react more cautiously than expected, the firm would lean harder on BEQALZI, solid tumor assets and disciplined cost control to offset that gap.
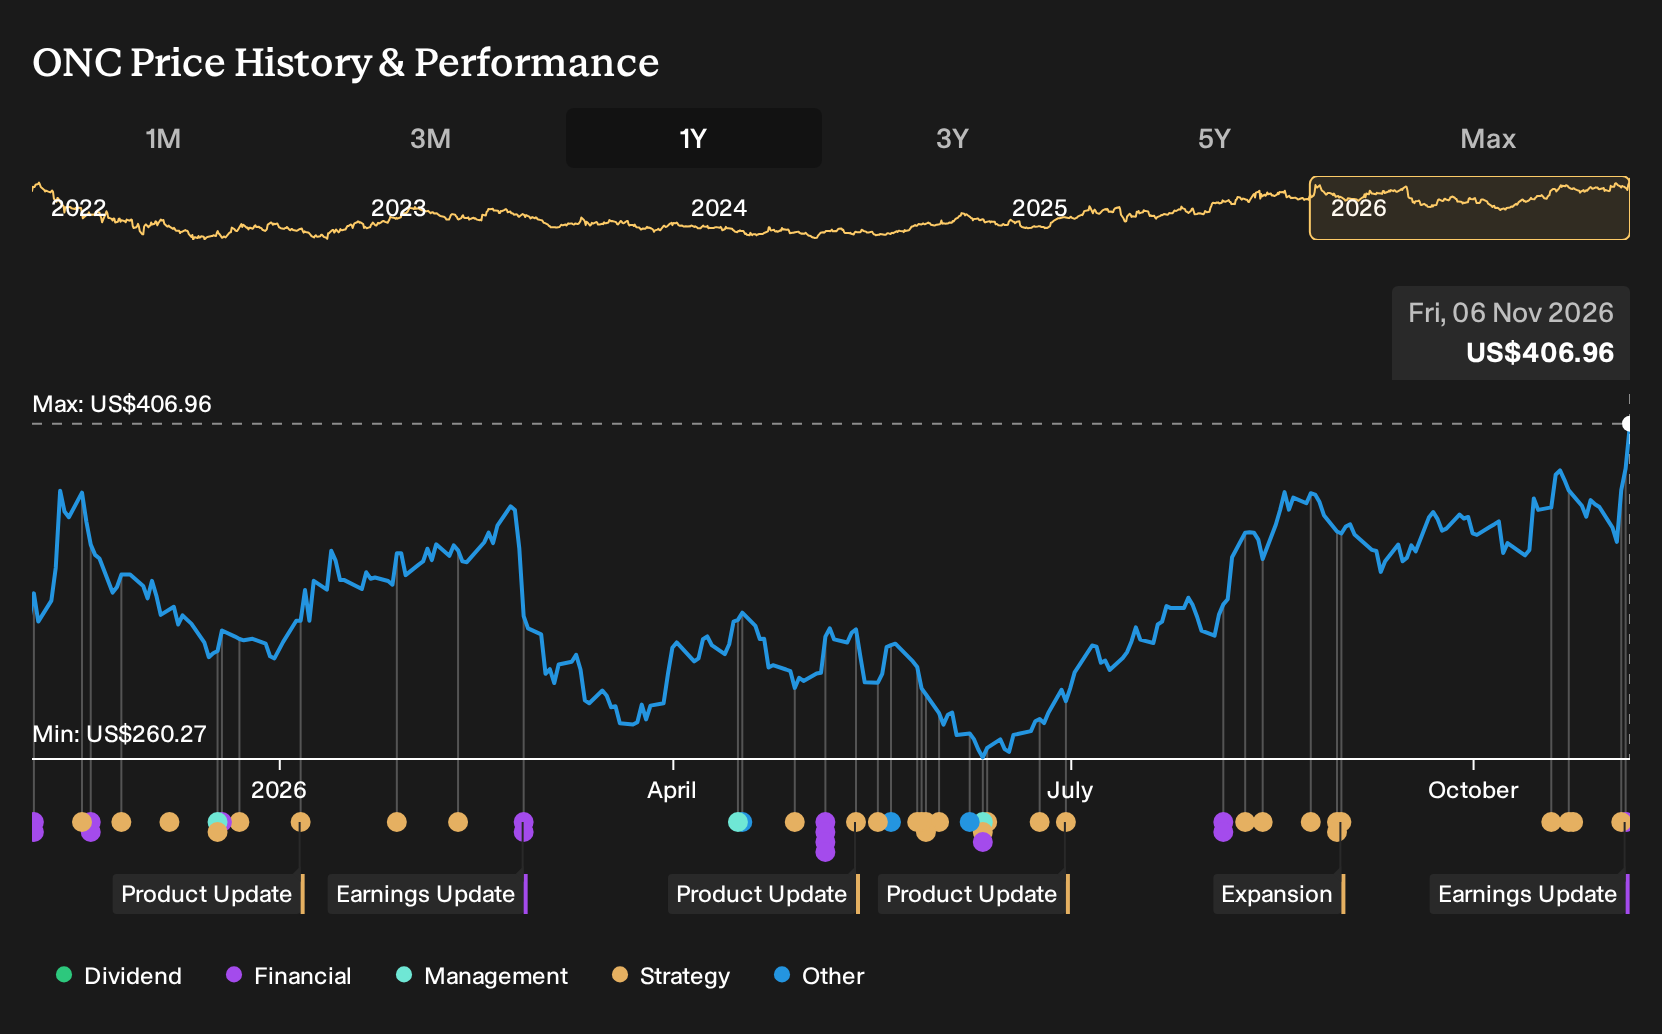
BeOne Medicines' analyst narrative projects US$9.2b revenue and US$1.9b earnings by 2029. This implies 14.7% yearly revenue growth and an earnings increase of about US$1.2b from US$655.7m today.
Uncover why BeOne Medicines' fair value indicates an 8% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
For BeOne Medicines, the most optimistic analysts focus on the solid tumor pipeline as the real swing factor. Before this week’s earnings beat, they were sketching out revenue of about US$10.8b and earnings of US$2.6b by 2029, far above consensus. Your takeaway is simple: opinion spreads are wide, and this fresh BRUKINSA news could push both narratives to evolve.
Explore 4 other BeOne Medicines fair value estimates, including one that suggests there could be up to 125% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BeOne Medicines research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for BeOne Medicines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BeOne Medicines' overall financial health at a glance.
Looking for more investment ideas beyond BeOne Medicines?
Once you have a handle on BeOne Medicines, it can help to widen the lens and see how other opportunities stack up using the Simply Wall St Screener.
- If you want a shortlist of companies that still look attractively priced, start with a focused set of 39 high quality undervalued stocks that pair quality fundamentals with undemanding expectations.
- For readers who care most about resilience and capital preservation, scan a 29 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- If you prefer to hunt for underfollowed ideas, work through a 19 high quality undiscovered gems that combine solid metrics with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com