
How Investors May Respond To OneMain Holdings (OMF) Higher Charge Offs
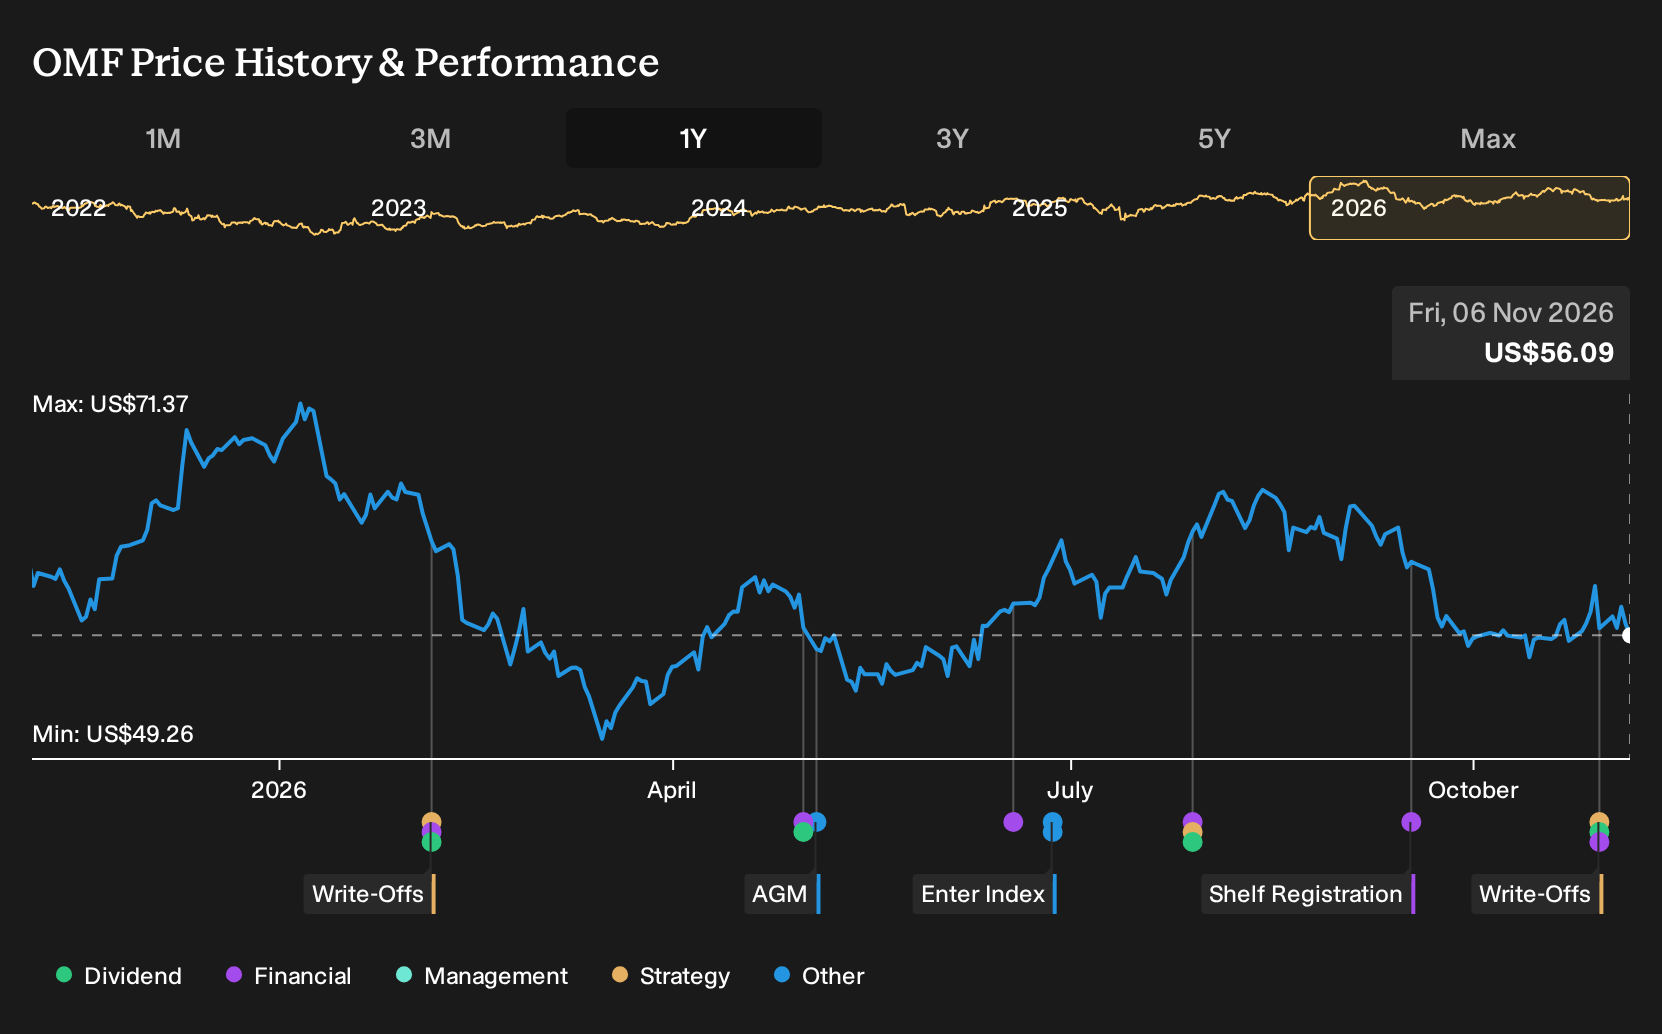
- OneMain Holdings reported third quarter 2026 net income of US$185 million and net charge offs of US$469 million, while also updating investors on dividends, earnings per share and share repurchases completed under its existing buyback plan.
- The company reported higher net charge offs and slightly lower quarterly earnings per share, alongside a US$1.05 quarterly dividend and a completed buyback tranche that reduced the share count by just over 5% under the current program.
- Investors will now assess how OneMain Holdings' investment narrative is influenced by higher net charge offs alongside a maintained cash dividend.
Scan how OneMain Holdings stacks up against other lenders returning cash to shareholders by reviewing our curated list of 8 dividend fortresses.
OneMain Holdings Investment Narrative Recap
To own OneMain Holdings, you need to be comfortable with a consumer lender that focuses on higher yielding products while carrying meaningful credit and funding risk. The recent quarter showed net charge offs of US$469 million and net income of US$185 million. That keeps the near term focus on whether credit metrics can settle without eating too far into earnings power.
The most important short term catalyst is how quickly credit costs stabilise as receivables in personal loans, auto finance and cards season. The largest risk remains that card and legacy back book losses stay elevated, which could constrain margin improvement. The latest figures incrementally reinforce that risk but do not radically change it.
The Q3 2026 earnings update is the clearest lens for this news. Net income of US$185 million, compared with US$199 million a year earlier, and basic EPS from continuing operations of US$1.61, compared with US$1.67, show the business still generating profits while absorbing higher net charge offs of US$469 million versus US$427 million.
For you as a shareholder, that trade off between earnings and credit quality ties directly into the key catalysts investors watch most closely for OneMain Holdings. Consistent profitability can support ongoing dividends and buybacks, while the higher credit costs highlight execution risk around card expansion and the remaining legacy loan book. How those two forces balance will shape sentiment around the stock.
OneMain Holdings' current analyst narrative points to forecast revenue of US$7.3b and earnings of US$1.2b by 2029. This reflects assumed yearly top line growth of 34.4% and an earnings increase of about US$419m from current earnings of US$781.0m.
Uncover why OneMain Holdings' fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently shows 2 fair value views for OneMain Holdings clustered between about US$61.64 and US$68.64, indicating a relatively narrow range of expectations. Those opinions do not yet reflect rising net charge offs or the affirmed US$1.05 dividend. You can use that difference to compare how various investors weigh credit risk and capital returns, then explore more community viewpoints before forming your own stance.
Explore another OneMain Holdings fair value estimate, including one that suggests as much as 22% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OneMain Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for OneMain Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate OneMain Holdings' overall financial health at a glance.
Looking for more investment ideas beyond OneMain Holdings?
Once you have a handle on OneMain Holdings, it can help to widen the lens and compare it with other companies that match your risk tolerance and income goals. The Simply Wall St Screener lets you filter for different profiles so you can build a list that fits how you like to invest rather than working from a single stock at a time.
- If capital preservation sits high on your list, consider starting with a group of businesses that score well on resilience through our 29 resilient stocks with low risk scores.
- Income focused investors can scan for companies combining higher yields with consistent shareholder payouts by reviewing a curated 8 dividend fortresses.
- For those hunting for underfollowed ideas with solid fundamentals, broaden your watchlist with a hand picked set of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com