
10x Genomics (TXG) Stock Looks Overvalued After Its 289% Run
10x Genomics has seen its stock swing sharply over the past year, which puts fresh attention on a simple question for you as a shareholder or potential buyer. Is the current share price adequately supported by the level of sales the business is generating today.
- Over the past year the stock has gained 288.7%, so anyone looking at 10x Genomics now is effectively being asked to pay a very different sales multiple than a year ago.
- The company has just launched Sentira Single Cell, an AI powered tool for interpreting single cell data, which may support expectations for future demand and the revenue that can be earned from its existing technology platform.
- There is a second opinion on 10x Genomics worth weighing. See what analysts think 10x Genomics's shares could be worth.
The issue now is whether the current market value of 10x Genomics is justified by its sales when viewed through this single lens.
If you want to sanity check 10x Genomics against other AI related opportunities, apply the same sales lens to 35 healthcare AI stocks.
Does 10x Genomics Look Pricey on Sales?
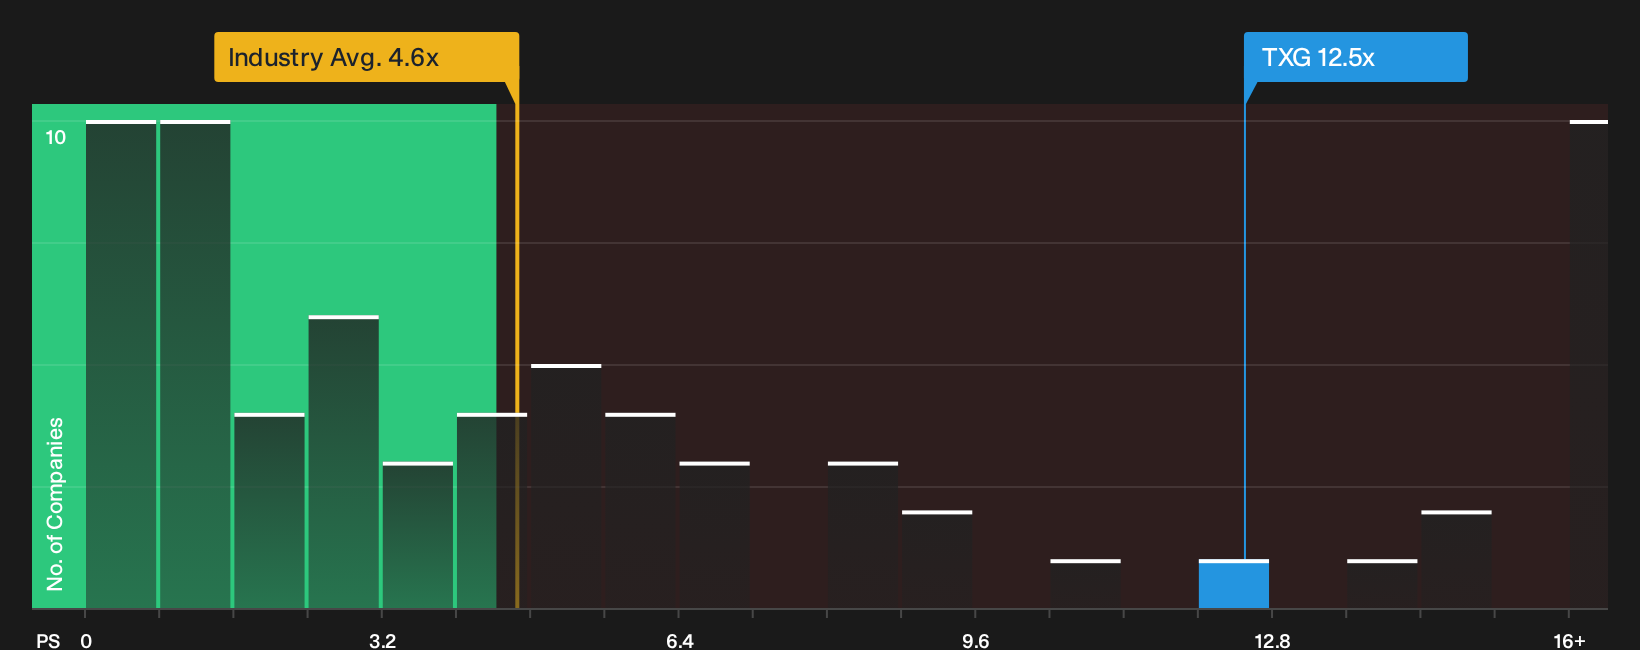
The P/S ratio fits 10x Genomics because revenue is still a key anchor for how the market judges its potential. Right now the stock trades on a P/S of 12.5x, compared with a Life Sciences industry average of about 4.6x and a peer group closer to 5.0x. Buyers are paying a much richer price for each dollar of current sales than for typical sector alternatives.
On Simply Wall St’s fair multiple framework, which adjusts the benchmark for factors like the company’s growth profile, margin structure, risk and size, that current 12.5x screens above the level implied by those fundamentals, so the shares look overvalued on this sales lens. Because Sentira Single Cell has kept attention on 10x Genomics’ AI angle despite recent share price pressure, that premium P/S suggests sentiment remains strong relative to both the sector and more tailored valuation markers. Explore the numbers behind 10x Genomics's P/S valuation.
The 10x Genomics Narrative: What Would Justify Today's Price?
10x Genomics' high P/S multiple raises an obvious follow up question for you as an investor. What future path for growth, margins and earnings would need to play out for this share price to look cheap, fair, or stretched? Simply Wall St Narratives sit on the Community page and spell out those embedded assumptions as clear scenarios. Each is framed as a thesis about the business that you can revisit over time rather than a one off snapshot.
Community views on 10x Genomics are split between those who see AI and spatial biology as underappreciated and those who think that enthusiasm is already baked in.
Bull case: 24% undervalued
"Global investment in genomics, including collaborations like the TISHUMAP initiative and large-scale AI-driven studies using 10x platforms, is increasing the customer base and creating new high-throughput, high-complexity data requirements…"
Discover why this Narrative puts 10x Genomics at 24% undervalued.
Bear case: 19% overvalued
"The numbers imply that the share price already embeds strong confidence in Atera driven spatial growth, AI linked demand for complex experiments, and progress toward clinical applications, which leaves limited room for disappointment…"
Explore why this Narrative puts 10x Genomics at 19% overvalued.
Before you move on, one more 10x Genomics check belongs beside the price tag
The valuation tells only part of the 10x Genomics story, since Simply Wall St's broader review has also flagged specific risk checks that deserve your attention next. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com