
Political Shift And ETF Buying Might Change The Case For Investing In Goldman Sachs (GS)
- Goldman Sachs Group recently issued a series of senior unsecured medium term notes, including new fixed coupon bonds and long dated zero coupon securities, alongside ongoing work to syndicate a large SpaceX chip financing package and continued activity in its physical gold ETF.
- During the same period, Goldman Sachs Group was at the center of a political and regulatory shift, with a Democratic sweep of Congress reducing perceived policy risk for large banks just as major ETFs such as the SPDR Dow Jones Industrial Average ETF Trust raised exposure to the stock.
- The current focus is on how Goldman Sachs Group's investment narrative around fee based growth and efficiency interacts with reduced policy risk and fresh ETF demand.
Scan how Goldman Sachs Group’s bond activity and ETF flows compare with other large financials by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) in the same space.
Goldman Sachs Group Investment Narrative Recap
To own Goldman Sachs Group, you need to be comfortable with a story built around fee heavy Global Banking & Markets, a growing Asset & Wealth Management arm and heavy investment in technology and AI to keep expenses in check. The biggest near term swing factor remains whether higher non compensation costs, including tech spend, settle into a sustainable run rate.
Recent fixed income issuance and ETF flows do not materially change that near term catalyst. The key risk stays the same. If higher trading mix volatility, pressure in FICC activity or tighter leverage constraints meet a stickier expense base, the effort to keep returns on equity near recent levels could be harder.
The most relevant recent development here is the cluster of senior, mostly callable medium term notes and zero coupon bonds that Goldman Sachs Group issued across maturities from 2028 out to 2046. These range from the new Zero Coupon Notes due November 5, 2041 to multiple 5% to 7% coupons with 100% issue prices and small discounts.
For you as a shareholder, this activity sits squarely in the operating story. It refreshes term funding that supports Global Banking & Markets and financing activity while interacting with the leverage ratio and higher non compensation spend. The execution risk is straightforward. Management needs to balance funding cost, capital usage and fee based growth so these new liabilities support, rather than dilute, the core catalysts in advisory and asset management.
Goldman Sachs Group's narrative projects US$74.4b revenue and US$21.7b earnings by 2029. This aligns with analysts assuming 1.6% yearly revenue growth and implies an earnings increase of about US$0.4b from the current US$21.3b level.
Uncover why Goldman Sachs Group's fair value indicates a 20% potential upside to its current price that may not last much longer.
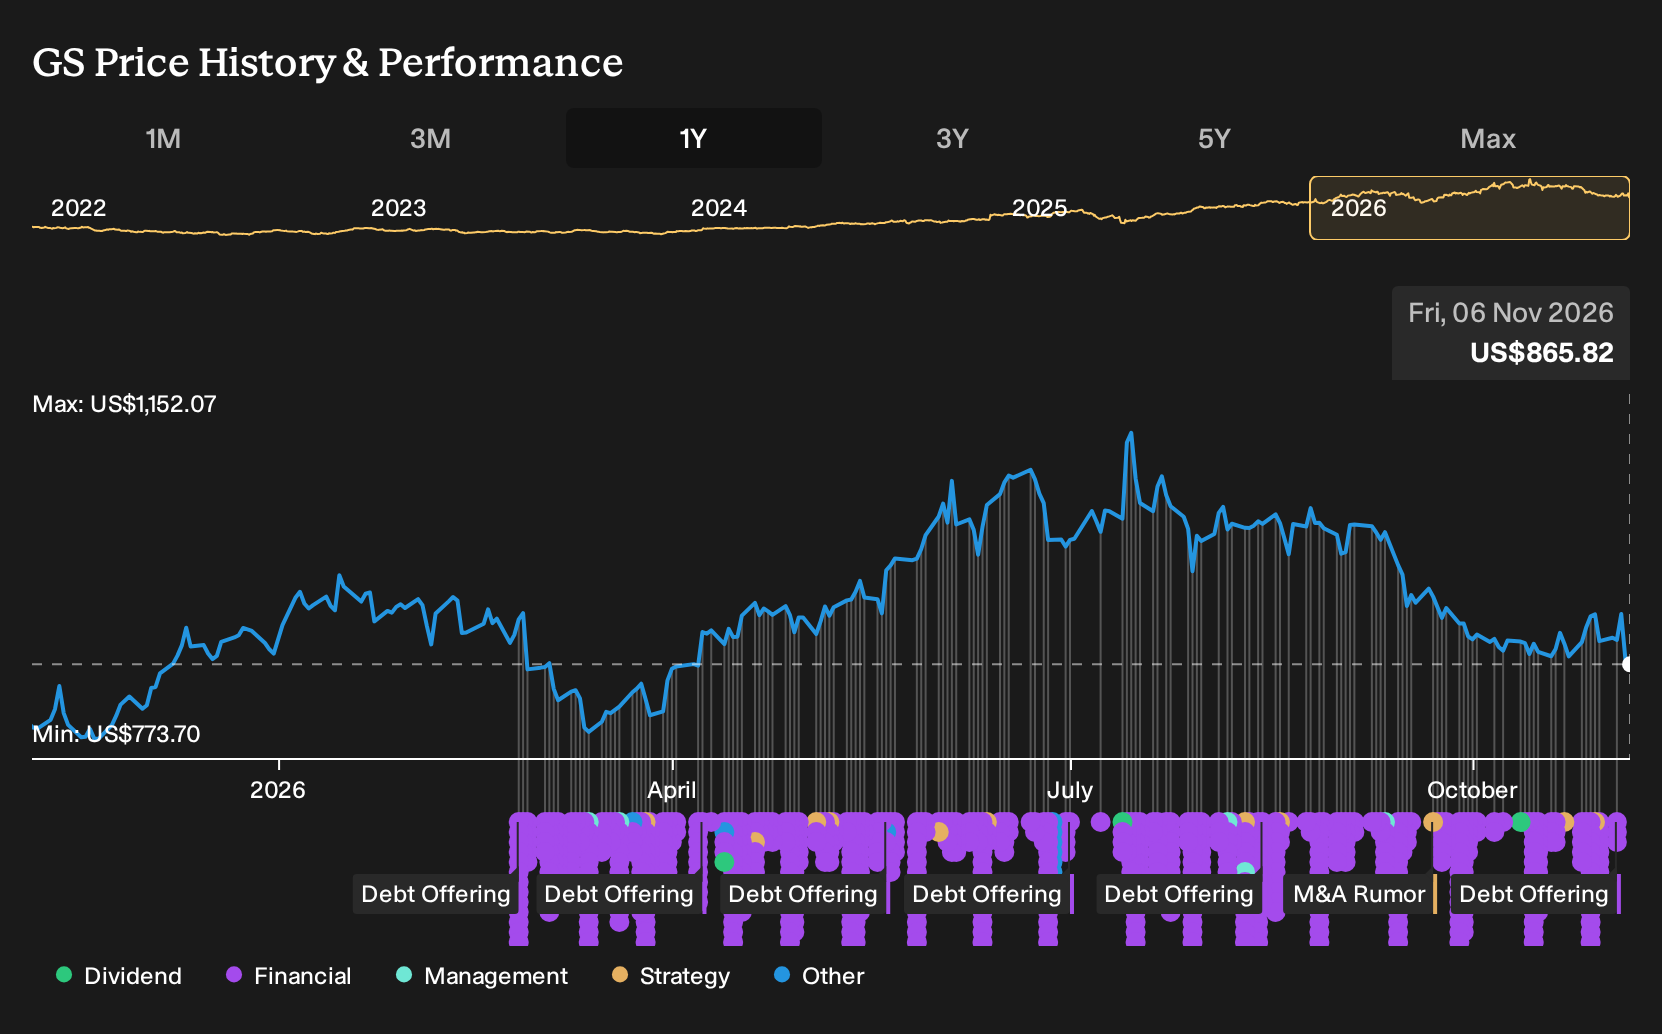
Exploring Other Perspectives
One bullish twist on Goldman Sachs Group focuses on the AI and data center financing wave rather than fee stability. The most optimistic analysts were pencilling in US$79.5b of revenue and US$24.4b of earnings by 2029 before this bond flood. If this funding shift reshapes risk or growth expectations, those narratives could move.
Explore 4 other Goldman Sachs Group fair value estimates, including one that suggests there could be as much as 34% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Goldman Sachs Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Goldman Sachs Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Goldman Sachs Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Goldman Sachs Group?
Once you have a view on Goldman Sachs Group, it can help to compare that thinking with other opportunities that share some of the qualities you care about most, whether that is balance sheet strength, income potential or under followed quality.
- For investors who want potential mispricing plus quality, review a curated group of companies with strong fundamentals using the 19 high quality undiscovered gems.
- If capital preservation and steadier profiles matter more to you than chasing maximum upside, filter for businesses with modest risk characteristics via the 29 resilient stocks with low risk scores.
- Income focused readers who prefer cash returns today over distant pay offs can survey companies with higher yields through the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com