
Does Soft Earnings Miss Change The Bull Case For Wynn Resorts Stock (WYNN)?
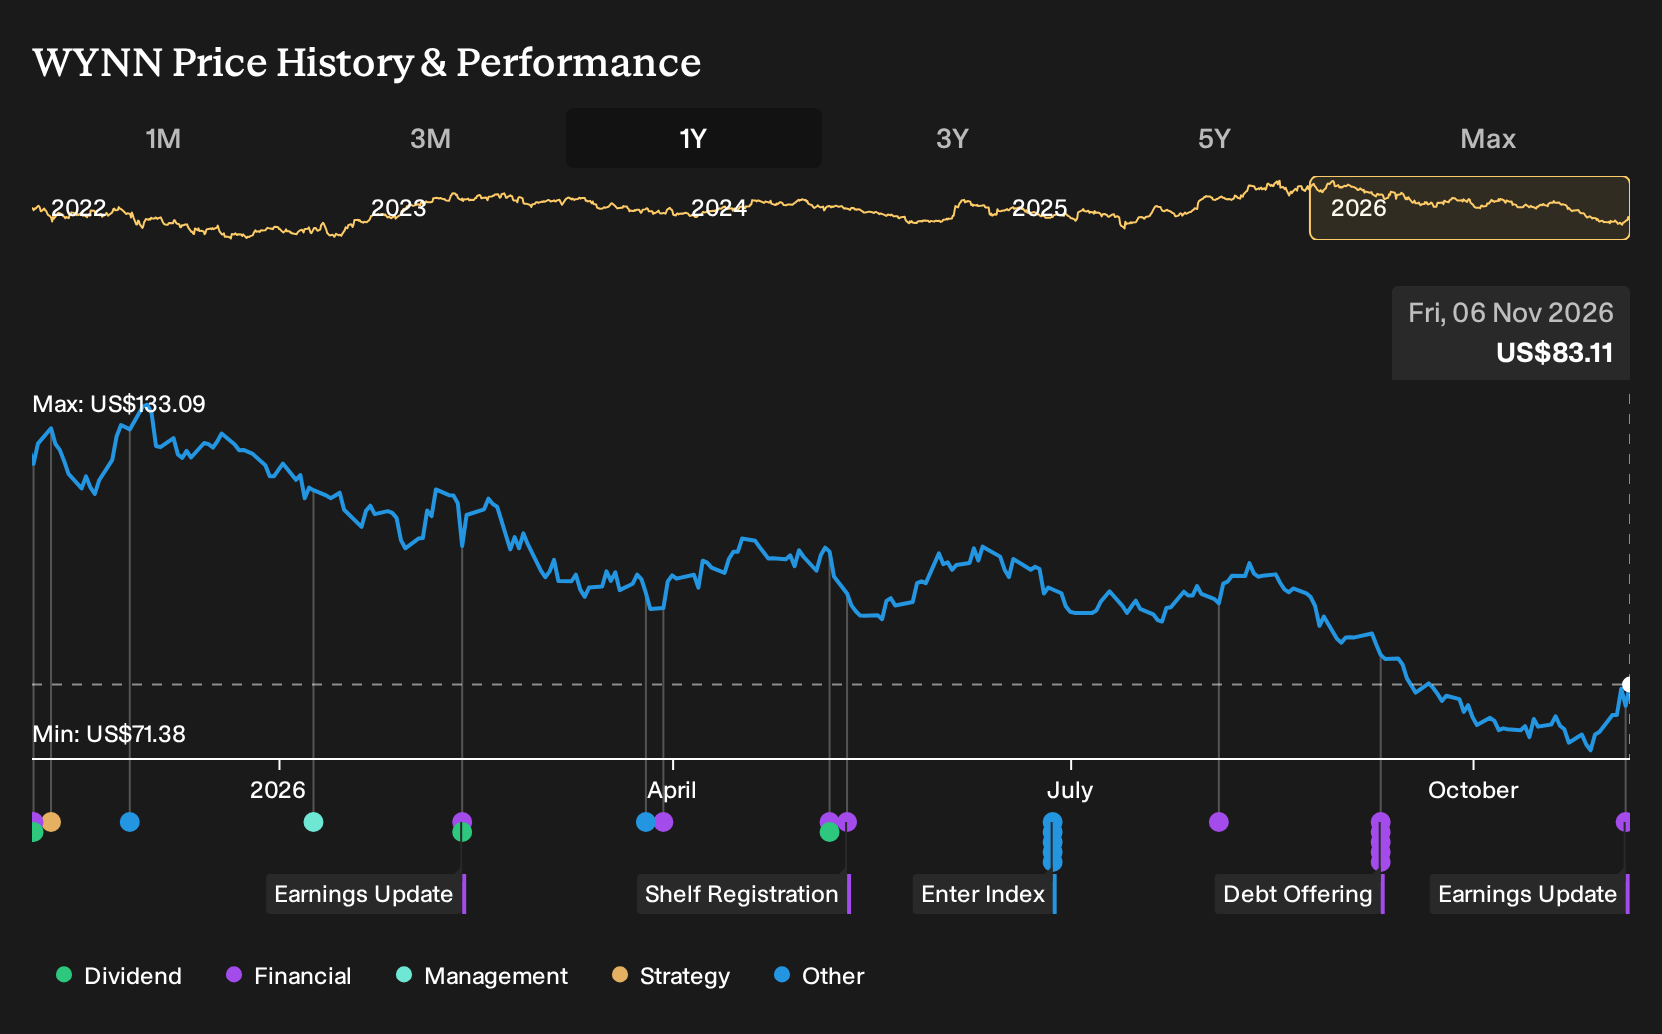
- Wynn Resorts reported Q3 2026 revenue of US$1.69b and net income of US$17.3m, with earnings and sales falling short of analyst expectations across major properties.
- The quarter exposed softer demand across Las Vegas, Macau and Encore Boston Harbor, at the same time the business is funding large, long dated resort projects.
- We will look at how Wynn Resorts' premium focused investment narrative compares with this softer quarter of broad based operational weakness.
Balance out Wynn Resorts' softer quarter by scanning a curated group of resilient casino and leisure operators in the 29 resilient stocks with low risk scores that may offer steadier risk profiles around events like this.
Wynn Resorts Investment Narrative Recap
To own Wynn Resorts, you need to believe the premium resort model can keep pulling in enough high spending guests to support heavy fixed costs and new builds. The latest quarter challenged that view a bit. Revenue of US$1.69b and net income of US$17.3m were both weaker than a year ago, which puts more pressure on efficiency and pricing.
The near term story now hinges on whether demand in Las Vegas, Macau and Encore Boston Harbor stabilises around key events and seasonality. The biggest operational risk is that softer volumes meet rising labor and interest costs at the same time, which would keep EBITDAR margins tight while Wynn Al Marjan Island and remodel projects still consume cash.
The most relevant recent update is management highlighting Wynn Al Marjan Island progressing toward its planned September 2027 opening, after a roughly US$600m uplift in total project cost. That resort is a central future catalyst because it adds a new integrated property in a fresh geography alongside the existing Las Vegas, Macau and Boston assets.
That opportunity cuts both ways for shareholders. Construction and fit out tie up capital for years, and delays or cost creep were already flagged as a key risk before this softer quarter. With third quarter earnings under pressure and interest costs important, execution on Al Marjan and the timing of any cash contribution from that resort matter more than ever.
Wynn Resorts' current analyst story points to revenue of US$9.2b and earnings of US$544.0m by 2029, based on 7.3% yearly top line growth and an earnings increase of about US$95m from US$448.9m today.
Uncover why Wynn Resorts' fair value indicates a 46% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One optimistic angle on Wynn Resorts focuses on the bullish view of Wynn Al Marjan Island. Top analysts were pencilling in revenue of about US$9.7b and earnings near US$580.5m by 2029 before this weaker quarter. You can treat this more upbeat story as one of several competing viewpoints that may shift after the latest results.
Explore 2 other Wynn Resorts fair value estimates, including one that suggests as much as 92% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Wynn Resorts research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Wynn Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wynn Resorts' overall financial health at a glance.
Looking For More Ideas Beyond Wynn Resorts?
If this latest update on Wynn Resorts has you reassessing concentration risk, it can help to widen the lens and compare it with other listed businesses that share some of the same qualities you are looking for, whether that is income, quality or balance sheet strength.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) to help you focus on companies with sturdier foundations when cycles turn.
- If steady income is higher on your priority list, scan a hand picked pool of 8 dividend fortresses that may suit a more yield focused approach.
- For those hunting for overlooked opportunities with robust fundamentals, broaden your watchlist with a curated set of 19 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com