
Is BJ's Wholesale Club Holdings (BJ) Above Fair Value On Earnings?
BJ's Wholesale Club Holdings has delivered a solid share price run in recent years, and the question now is whether that move is properly supported by its earnings power. With the stock at US$109.40 as of the last close, investors are asking if the current price still lines up with what the business earns today.
- Over the past 5 years, BJ's Wholesale Club Holdings has returned 75.3%, which puts real weight on whether its earnings can carry that kind of share price performance.
- The warehouse-club model relies heavily on membership fees and tight cost control, so the way BJ's Wholesale Club Holdings converts sales into profit may support very different earnings expectations than a typical retailer.
- The analysts covering BJ's Wholesale Club Holdings have run their own numbers. See what analysts think BJ's Wholesale Club Holdings's shares could be worth.
The issue now is whether BJ's Wholesale Club Holdings' current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing BJ's Wholesale Club Holdings against other earnings focused opportunities, it can help to compare it with 39 high quality undervalued stocks.
Is BJ's Wholesale Club Holdings Fairly Priced on Earnings?
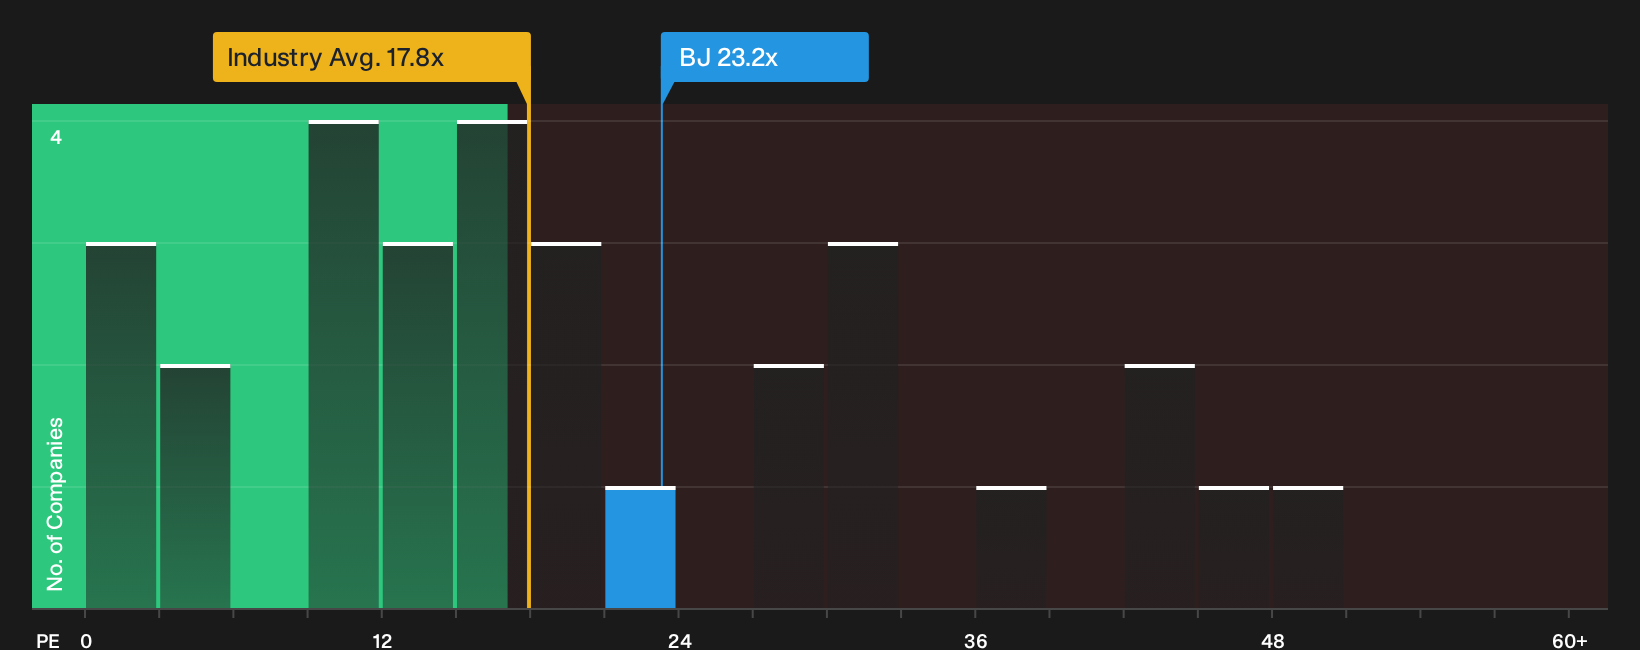
The P/E ratio fits BJ's Wholesale Club Holdings well because investors often judge membership driven retailers on the earnings stream they can produce each year. At roughly 23.2x earnings, the stock trades above the Consumer Retailing industry average of about 17.8x and also above the peer group near 19.7x, which means you are paying a richer price per dollar of profit than many listed retailers.
The Fair Ratio framework suggests a P/E level that lines up closely with where BJ's Wholesale Club Holdings changes hands today, so the current multiple sits only slightly above that tailored benchmark. That points to a valuation where the market is neither clearly stretching far ahead of the earnings profile nor heavily discounting it. The key question for you is whether BJ's can sustain the kind of membership economics and cost discipline that justify paying this sort of earnings multiple. Explore the numbers behind BJ's Wholesale Club Holdings's P/E valuation.
The BJ's Wholesale Club Holdings Narrative: What Would Justify Today's Price?
Narratives for BJ's Wholesale Club Holdings pick up where the valuation puzzle leaves off and explain what kind of future for growth, margins and earnings would need to unfold for the current share price to look meaningfully high or low. They turn a single P/E or model output into a set of concrete assumptions, so you can compare how the real business performance lines up with the scenario that price implies over time on Simply Wall St's Community page.
Community views on BJ's Wholesale Club Holdings are split between one group seeing extra upside in the membership model and another arguing the story is already well reflected in the price.
Bull case: 9% undervalued
"Outperformance of new Texas clubs, with memberships roughly 30 to 33% ahead of plan and gas stations ranking in the top tier of the chain for gallons…"
Discover why this Narrative puts BJ's Wholesale Club Holdings at 9% undervalued.
Bear case: roughly fairly valued
"The question this report tracks is whether the narrative architecture from the May call held, the price investment thesis, the tariff refund framework as a funding mechanism, the early Texas posture…"
Explore why this Narrative puts BJ's Wholesale Club Holdings at roughly fairly valued.
One more angle on BJ's Wholesale Club Holdings that could shift your view
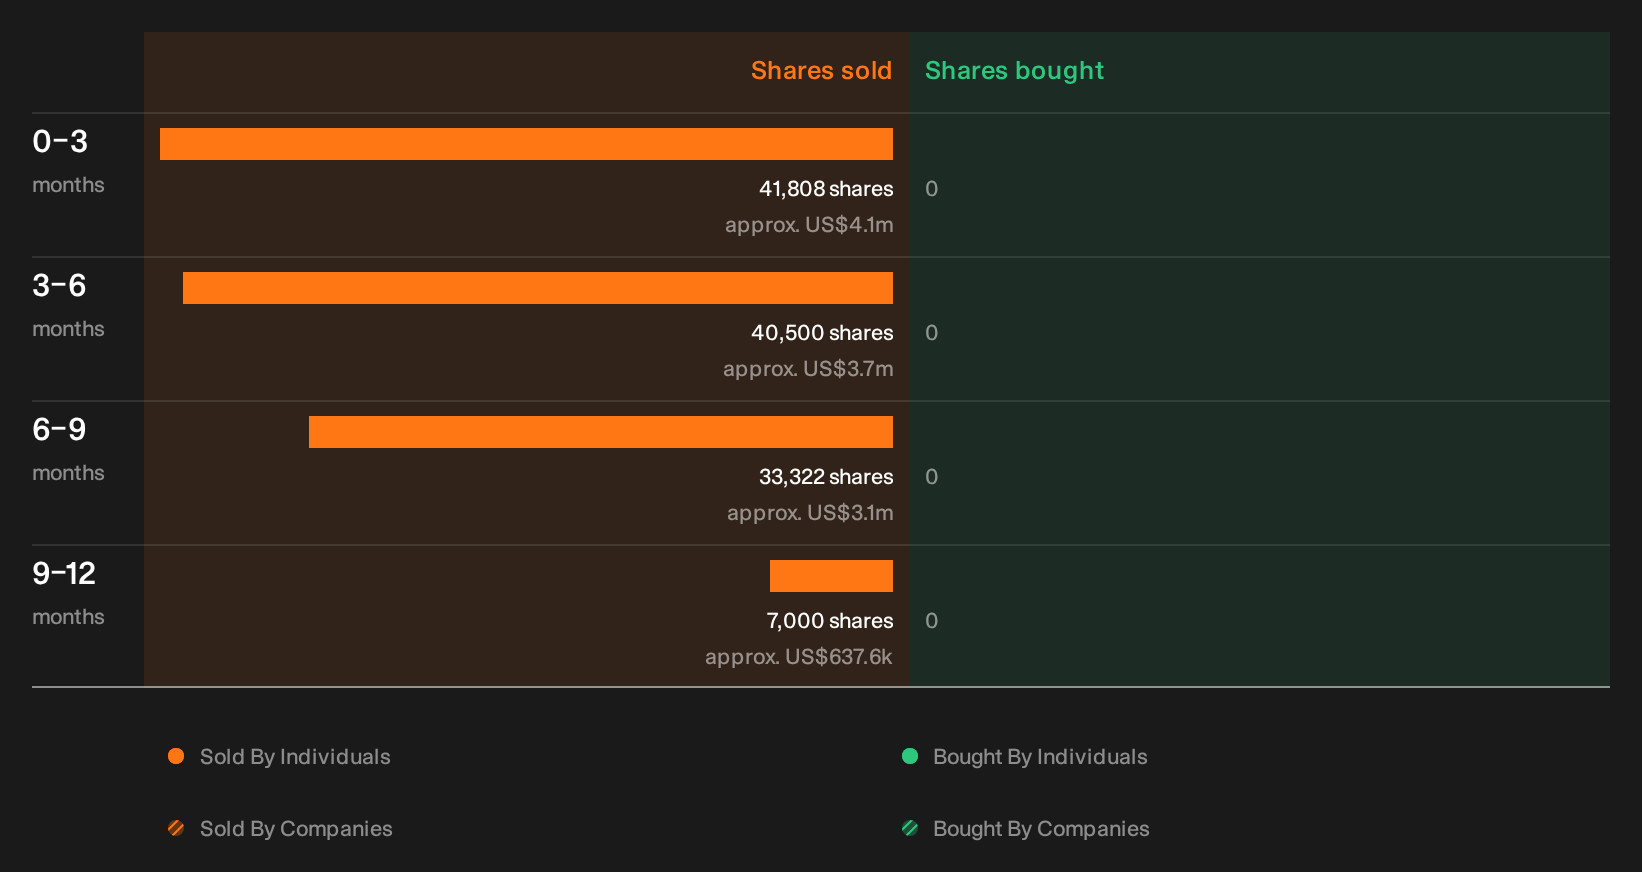
Valuation only tells part of the story, and recent share dealings by people inside BJ's Wholesale Club Holdings add another piece that is worth examining in its own right. See the recent insider selling flagged for BJ's Wholesale Club Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com