
Is Return To Profit Altering The Investment Case For NCR Voyix Stock (VYX)?
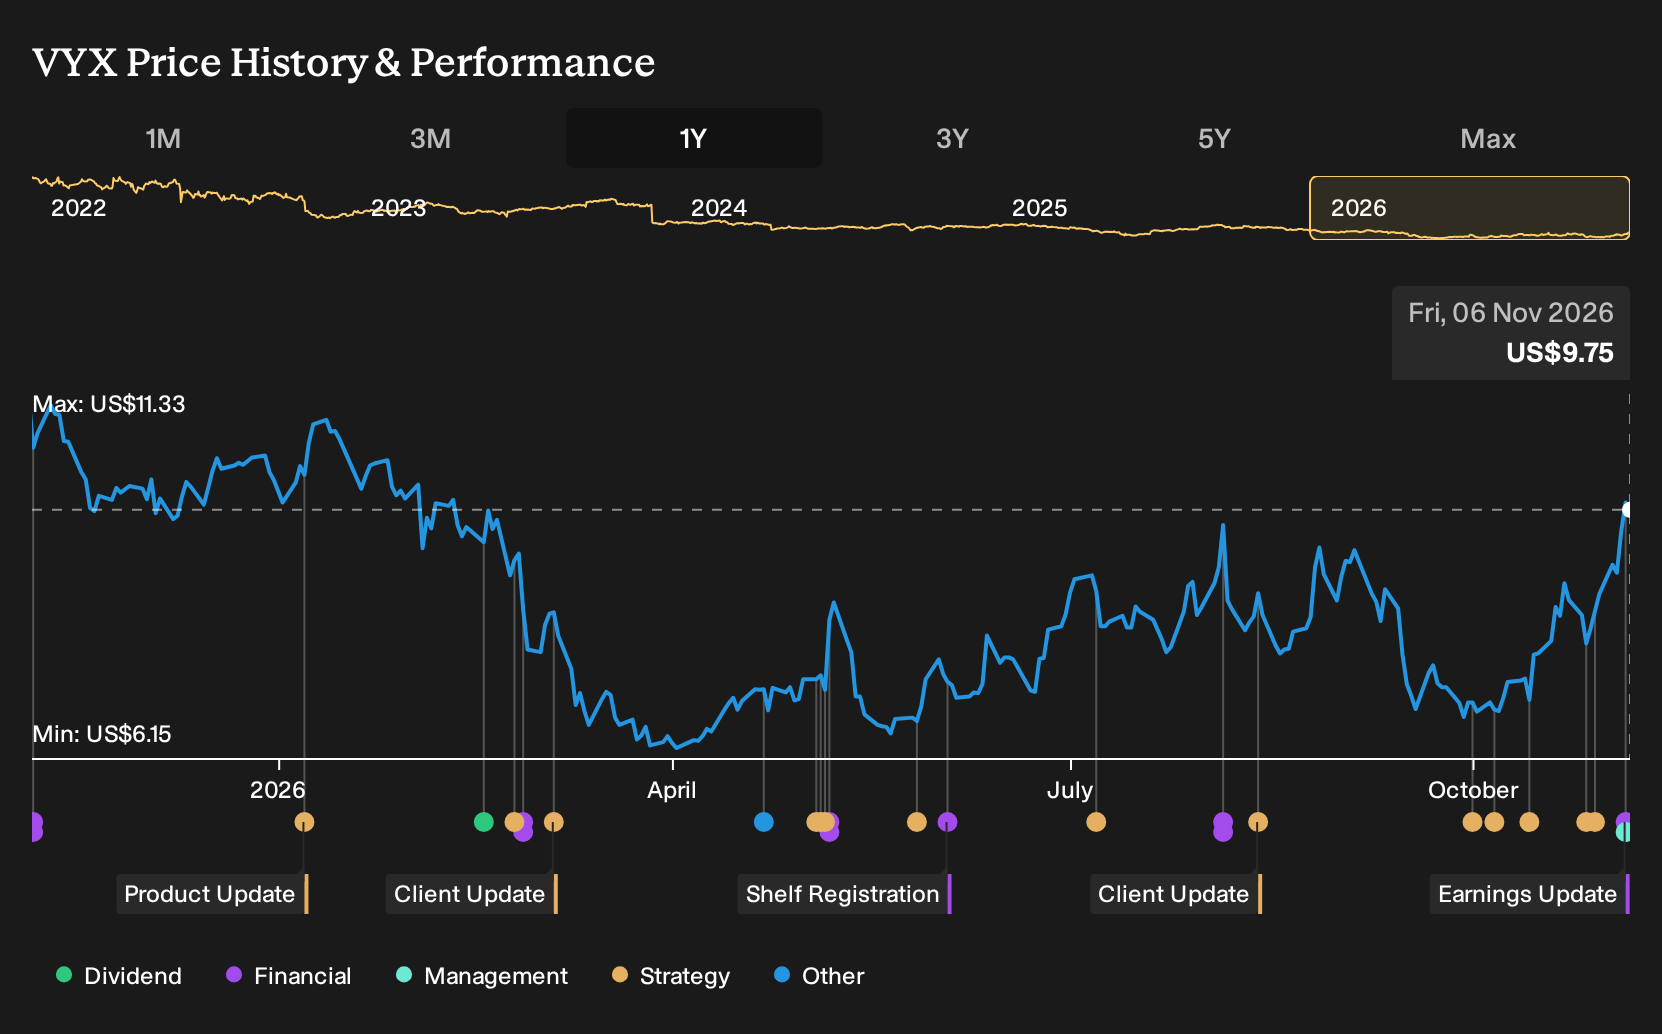
- NCR Voyix reported third quarter 2026 revenue of US$539 million compared with US$677 million a year earlier, with net income of US$24 million instead of a loss, alongside new leadership appointments and fresh multi‑year restaurant client agreements.
- The mix of improved profitability, leadership reshuffle and long term deals with First Watch and Bruster’s highlights NCR Voyix’s focus on cloud POS and payments execution rather than hardware centric solutions.
- The focus now shifts to how this renewed profitability and fresh leadership bench might influence NCR Voyix's longer term investment narrative.
NCR Voyix Investment Narrative Recap
To own NCR Voyix, you need to be comfortable with a story where legacy hardware shrinks in importance while software, cloud POS and payments do more of the heavy lifting. The latest quarter showed revenue at US$539 million compared with US$677 million a year earlier, with a move to a US$24 million profit. That mix reinforces a thesis built more on earnings quality than sheer size.
The near term catalyst many investors will watch is simple: can management keep profitability intact while revenue remains under pressure during the business model shift? The biggest risk is that transition costs, interest expense and tariff or supply chain pressures could squeeze margins again if recurring software and payments income does not ramp fast enough.
The First Watch multi year agreement sums up the operational catalyst from this earnings update. A large, single restaurant group committing to Aloha Next and Voyix Kitchen across nearly 600 locations gives NCR Voyix a clearer path to recurring software and payments usage, rather than just a one off hardware refresh.
That contract also concentrates risk. Execution now depends on delivering reliable rollouts, keeping uptime high and proving that integrations stay simple for store teams. Any stumble here could feed competitive pressure from other cloud based POS and payments providers, which is already one of the key threats around NCR Voyix's enterprise focused restaurant strategy.
NCR Voyix's current earnings sit at US$42.0 million, while analysts project revenues of US$2.0b and earnings of US$5.6 million by 2029. This reflects a 10.1% yearly revenue decline and a US$36.4 million decrease in earnings from today.
Uncover why NCR Voyix's fair value indicates a 32% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame the NCR Voyix story around cost execution rather than restaurant softness. Before this earnings release, the bullish group was pencilling in 2029 revenue of about US$2.1b and earnings near US$31.1 million. That is a very different angle to the consensus, and this quarter’s leadership changes and new restaurant deals may nudge both views.
Explore 3 other NCR Voyix fair value estimates, including one that suggests potential upside of up to 378% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NCR Voyix research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NCR Voyix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCR Voyix's overall financial health at a glance.
Looking For More Ideas Beyond NCR Voyix?
If you want to stress test your NCR Voyix thesis against other opportunities, the Simply Wall St Screener can help you line up comparable stocks and see which ones genuinely fit your risk and return preferences.
- For investors who care most about capital strength and resilience, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without relying on heavy leverage.
- If capital preservation ranks high on your checklist, filter for 29 resilient stocks with low risk scores and see which businesses pair steadier risk scores with more predictable fundamentals.
- When you want something a bit less crowded, scan through 19 high quality undiscovered gems that have strong underlying metrics but receive far less attention from the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com