
Why Annaly Capital Management (NLY) Is Back In The Spotlight
Annaly Capital Management (NLY) just moved above its 20 day moving average after a run of upward earnings estimate revisions, a combination that has pushed investor attention firmly back onto the mortgage REIT.
Short-term traders have leaned back in after the recent break above the 20 day moving average. However, Annaly Capital Management’s share price is still down about 18% over the past 90 days and roughly 18% year to date. At the same time, the 3 year total shareholder return of about 66% and 5 year total shareholder return of about 9% paint a steadier long haul picture that hints recent weakness may reflect shifting views on interest rate risk and dividend durability rather than a simple growth story falling apart.
Scan beyond Annaly Capital Management’s breakout and compare it with a hand picked 8 dividend fortresses that also combine income potential with sturdier looking fundamentals.
Annaly Capital Management has the earnings revisions, income focus and long record as a mortgage REIT that many investors look for. The real tension now is whether the recent bounce leaves the stock reasonably priced or already full.
Price-to-Earnings of 15.5x: Is it justified?
On a simple earnings yardstick, Annaly Capital Management trades on a P/E of 15.5x, which lines up with the global Mortgage REIT average but sits above the 13.8x peer group level. This means the market is paying a premium to similar stocks even though the broader sector is priced at a similar multiple.
The P/E ratio compares the current share price to annual earnings per share and gives a shorthand view of how much investors are willing to pay for each dollar of profit. For a mortgage REIT like Annaly Capital Management, where earnings are closely tied to funding costs and asset yields, that multiple often reflects how confident investors are that current profit levels and the dividend profile can be maintained through interest rate cycles.
Analysts forecast earnings to grow about 51.1% per year and revenue to advance roughly 20.2% per year, so a headline P/E of 15.5x can be read as the market assigning a relatively full price to those expectations. At the same time, the estimated fair P/E of 26.8x sits meaningfully higher than the current multiple. This points to scope for the ratio to move closer to that level if those growth forecasts and cash flow assumptions hold up.
Compared with the global Mortgage REIT average P/E of 15.5x, Annaly Capital Management trades in line with the sector. Yet against its closer peer set on 13.8x it screens as more expensive, suggesting investors are granting it a richer tag than direct comparables while still leaving a gap to the fair P/E estimate of 26.8x.
Explore the SWS fair ratio for Annaly Capital Management.
Result: Price-to-Earnings of 15.5x (UNDERVALUED)
Still, the story around Annaly Capital Management can change quickly if funding costs rise faster than asset yields or if credit losses eat into that dividend cushion.
Find out about the key risks to this Annaly Capital Management narrative.
Another View: What The SWS DCF Model Says About Annaly Capital Management
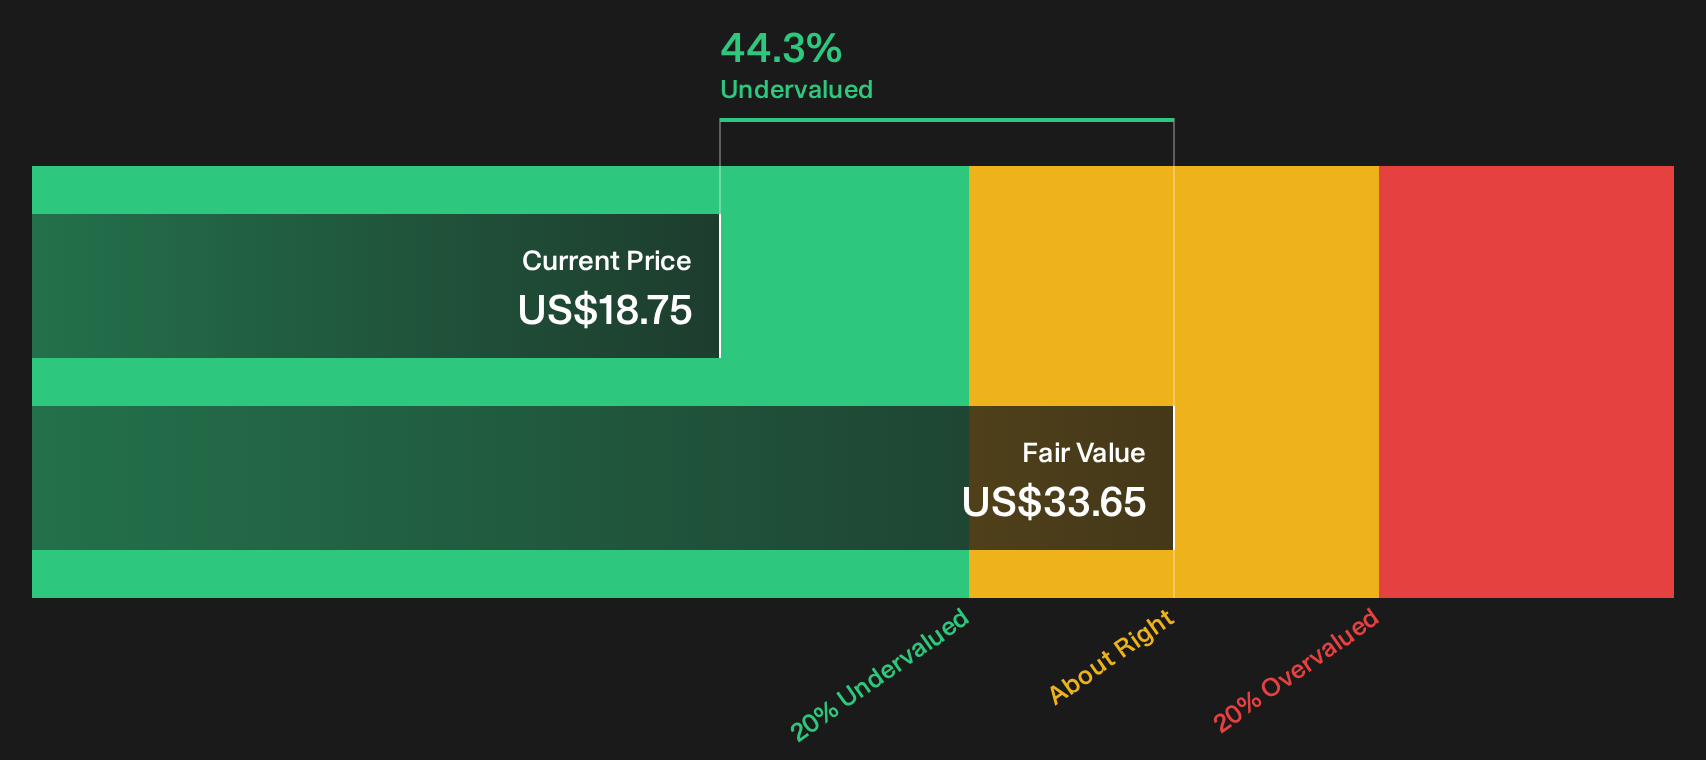
The P/E points to Annaly Capital Management trading on a richer tag than close peers, yet the SWS DCF model suggests the opposite story. On that cash flow view, an $18.75 share price compares with an estimated future cash flow value of $33.65, which screens as undervalued.
A gap of roughly 44% between price and that DCF estimate leaves room for very different outcomes depending on how book value, spreads and dividend policies evolve from here. For an income focused REIT like Annaly Capital Management, which lens matters more to you when the signals disagree this sharply?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Annaly Capital Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these around Annaly Capital Management rarely stay unresolved for long. Consider reviewing the data yourself and weighing both sides of the story with the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Annaly Capital Management?
If you only stop at Annaly Capital Management, you risk missing other opportunities that fit your style even better, so broaden your watchlist using targeted screeners.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that can help you sidestep weaker businesses.
- Zero in on mispriced opportunities by reviewing a focused 39 high quality undervalued stocks that combines quality metrics with attractive entry points.
- Prioritise steady income by tracking a refined 8 dividend fortresses designed to spotlight payouts supported by healthier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com