
What Megaworld Holders Bought Into
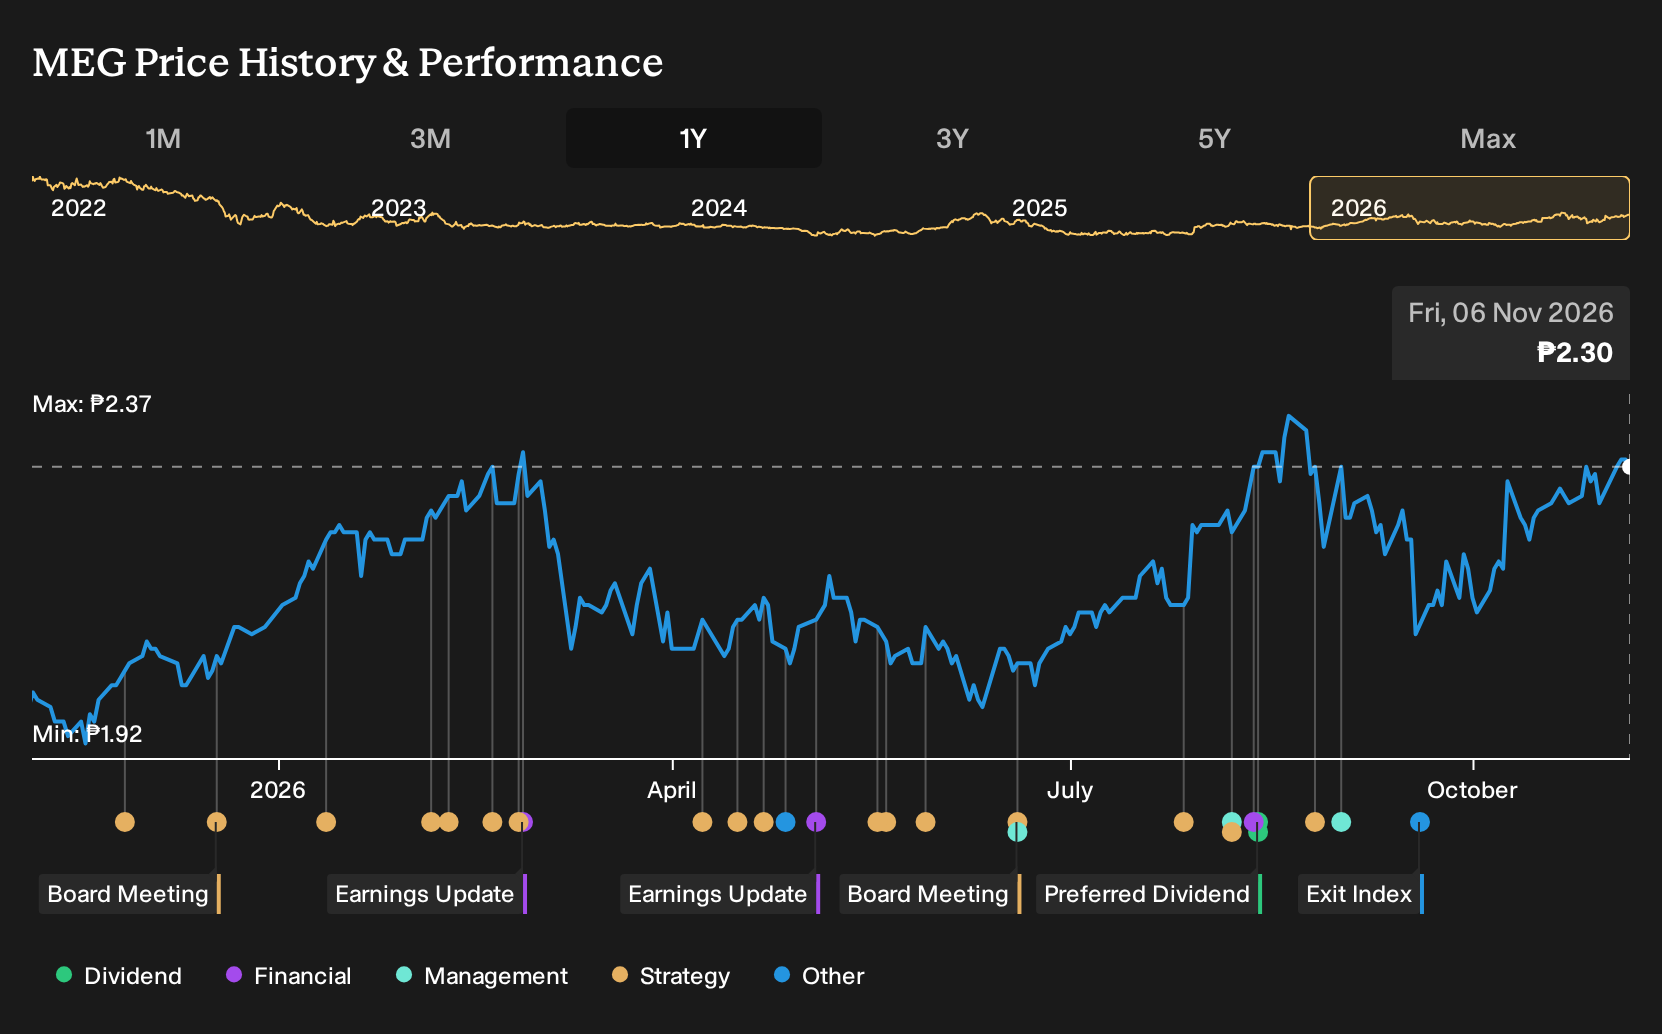
Investors who held Megaworld over the past year are up 22.4%, including dividends. If you had been deciding on 6 November 2025 whether to buy, you were looking at bullish research arguing that tourism led townships and high end projects could justify a Fair Value 32% above the start price, and a bearish view flagging remote work, oversupply and heavy floating rate debt. Which of those trade offs would have guided your own call?
If the move has made Megaworld harder to judge, start where the gap is still open and scan 224 high quality undervalued stocks.
The Two Megaworld Stories Investors Had To Choose
The shares cost ₱1.99 at the start of the period, and Megaworld sat between two very different but plausible stories about its future.
On the optimistic side, the Fair Value was set at ₱2.62, a price that only made sense if bullish assumptions played out. Supporters leaned on 1.9% assumed annual revenue growth and a 26.3% profit margin, helped by tourism led townships, high end buyers and a future P/E of 6.4x.
The cautious view pointed to a Fair Value of ₱1.79 based on more downbeat expectations. Critics focused on remote and hybrid work undermining BPO heavy offices, as well as the risk that aggressive expansion, oversupply and sizeable floating rate debt would pressure earnings.
What The Results Changed For The Megaworld Debate
The clearest new datapoint for Megaworld was the Q2 2026 report. Revenue moved from ₱20,798.36 million in Q2 2025 to ₱21,263.26 million, and net income edged up from ₱5,602.82 million to ₱5,654.36 million. Net margin slipped from 26.9% to 26.6%. That combination of higher sales and profit but a slightly thinner margin cut both ways for the bullish and cautious theses.
The key lesson is simple. When a story hinges on profitability resilience, do not just track earnings. Watch whether net margin trends in the same direction as revenue and test any margin claim against that line each quarter.
What Megaworld's Recent Gain Asks You To Believe Now
Megaworld now trades at ₱2.3, with this Narrative’s Fair Value sitting below that quote and framing the recent 22.4% one year gain as fully pricing in a lot of the good news.
The Narrative hangs on hotels and provincial townships offsetting office and residential strain. You would be assuming recurring rental cash flows stay resilient even if remote work, demographics and oversupply keep leaning on office and condo demand.
"Shifting work patterns and demographic challenges threaten demand for Megaworld's core office and residential segments, risking slower growth and compressed margins. Aggressive expansion, high debt, and environmental risks expose the company to refinancing challenges, higher costs, and pressure on future earnings and asset values."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 22% below our estimate - expands its sales force to win more recurring elevator maintenance contracts.
- Company 2 - 49% below our estimate - scales modular housing and energy projects while tightening margin focused project bidding.
- Company 3 - 40% below our estimate - bets on AI data centre chips remaining tied to its proprietary software stack.
That is three of the list. See the full list of 193 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com