
Raised Earnings Outlook Will Impact Naturgy Stock Investors
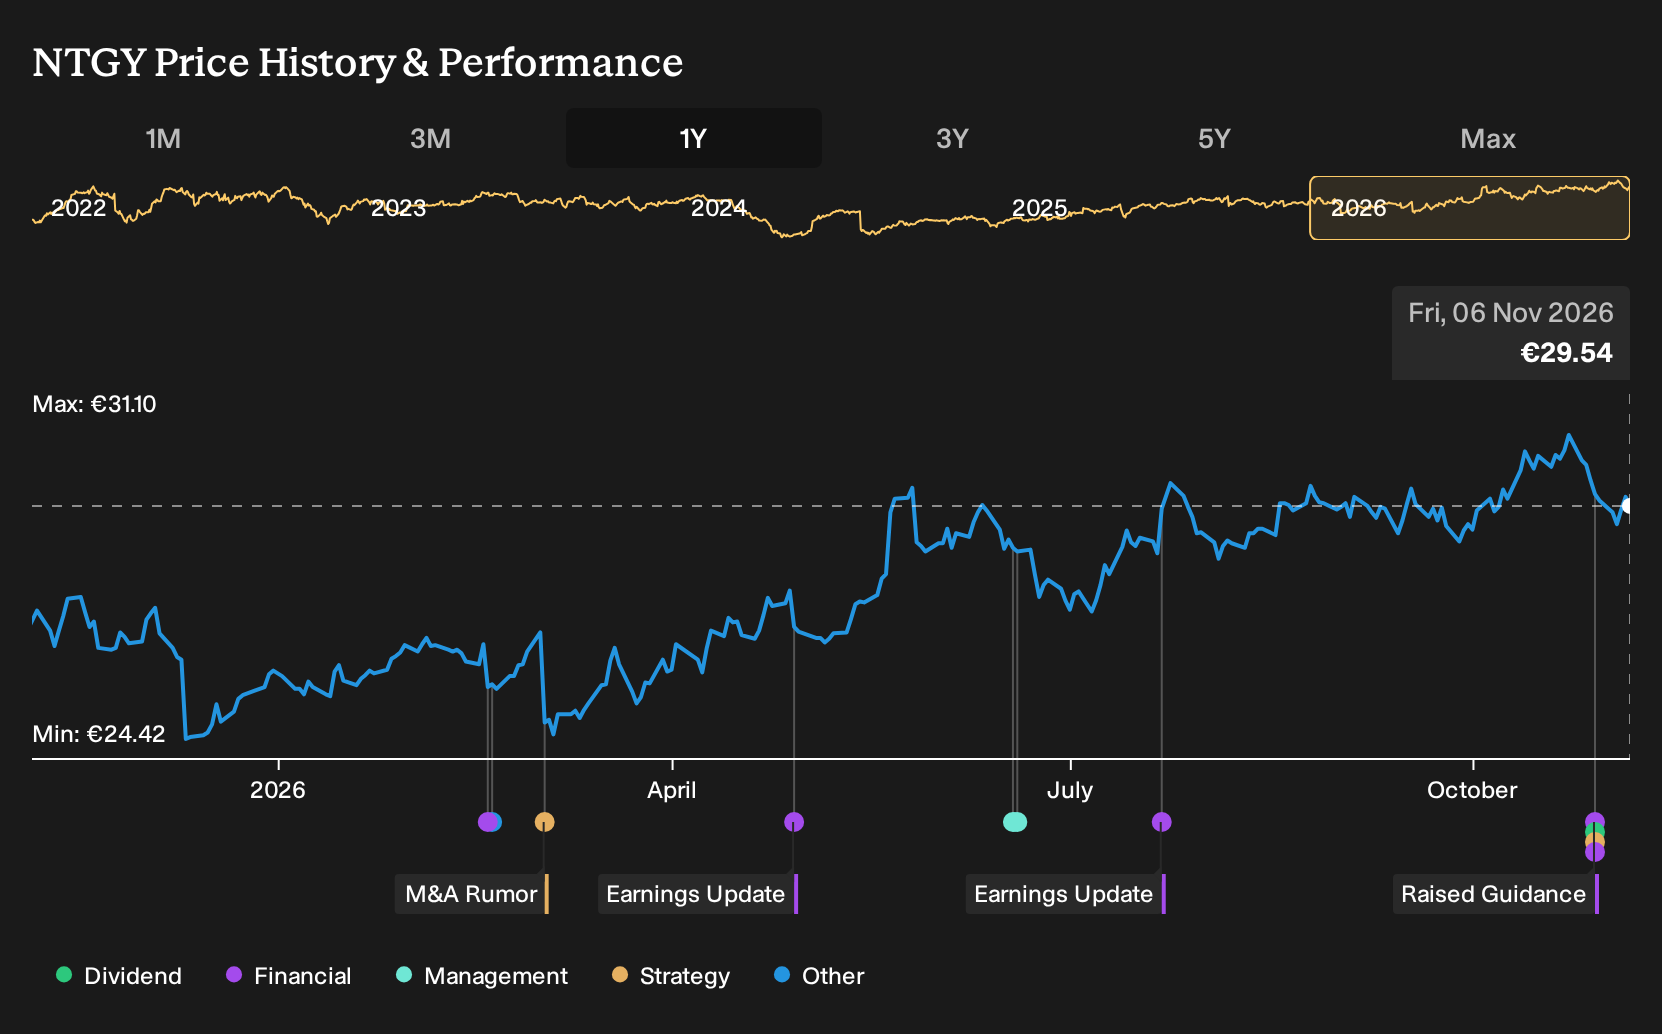
- Naturgy Energy Group confirmed a 2026 dividend of €1.8 per share and reported nine month 2026 sales of €15,374 million and net income of €1,758 million, alongside higher net income guidance of about €2.2 billion for the full year.
- The combination of firm dividend commitments and a higher earnings outlook signals management confidence in Naturgy Energy Group’s cash generation, even as it reviews a shortlist of potential M&A deals under strict return and discipline criteria.
- The market will now assess how Naturgy Energy Group’s upgraded earnings guidance could influence the existing investment narrative around resilient cash flows.
Spot other income-focused utilities showing similar conviction to Naturgy Energy Group by scanning our hand picked 232 dividend fortresses alongside this latest dividend affirmation and updated earnings outlook.
Naturgy Energy Group Investment Narrative Recap
To own Naturgy Energy Group, you need to be comfortable with a steady, cash focused utility that relies on its integrated gas and power model and regulated networks to support earnings, rather than on aggressive expansion. The raised 2026 net income outlook to about €2.2b reinforces that message, so the headline near term catalyst remains Naturgy delivering on that guidance.
The flip side is clear. Pressure in the supply and renewables segments, together with a more selective renewables build out, keeps execution risk on margins and growth. The latest dividend affirmation does not change that; it highlights Naturgy’s ability to keep cash generation resilient while those headwinds play out.
The most relevant update here is Naturgy Energy Group’s confirmation of a €1.8 per share dividend for 2026, including a second interim €0.60 payment in early November, alongside an ex dividend of €0.486 on 30 October. That commitment rests on the same earnings base that management now expects to reach roughly €2.2b this year.
For you as an investor, that link between payout and profit is where the main catalyst sits. Delivery against the upgraded guidance, while keeping debt manageable and handling weaker spots in supply and renewables, will be the practical test of how secure that dividend path appears compared with the risks flagged around high leverage and softer medium term earnings forecasts.
Naturgy Energy Group is currently expected to generate €19.4b of revenue and €2.0b of earnings by 2029, based on analyst consensus that assumes broadly flat top line performance and a move from €2.1b of earnings today. This implies an earnings decline of €0.1b between now and the 2029 forecast period.
Uncover how Naturgy Energy Group's fair value indicates a 5% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster tightly between €31.01 and €35.13, so private investors there currently see Naturgy Energy Group in a relatively narrow price band. Set that against rising earnings guidance, firm dividend plans and potential M&A, and you can judge how widely opinions might diverge.
Explore 2 other Naturgy Energy Group fair value estimates, including one that indicates up to 19% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Naturgy Energy Group research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Naturgy Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Naturgy Energy Group's overall financial health at a glance.
Looking for more Naturgy Energy Group style investment ideas?
If Naturgy Energy Group has you thinking about income, resilience and clear payout policies, it can help to scan a broader set of opportunities using the Simply Wall St Screener.
- For investors who want income that looks more robust on paper, check out a curated set of potential 232 dividend fortresses that combine yield with balance sheet strength.
- If your priority is cushioning portfolio volatility, consider broadening your watchlist with a group of 212 resilient stocks with low risk scores that score well on consistency and financial resilience.
- To hunt for opportunities that may be flying under the radar, review a focused collection of 588 high quality undiscovered gems backed by stronger fundamentals than their visibility might suggest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com