
3 Defensive Dividend Stocks Investors Are Watching As Rate Hike Fears Persist
Fed officials are hinting at more rate hikes, yet markets are still pricing hope into anything that looks steady and cash generative. That mix of higher-for-longer policy talk and investor anxiety around volatility is creating a quiet scramble for large, resilient dividend payers. This piece walks through three US large-cap defensive dividend stocks from our screener that appear closely tied to this rate story and merit closer examination now.
The three stocks covered below are a small sample of what fits this defensive dividend brief, and the full screen surfaced 26 more large caps with income stories that are not covered here but are cut from the same quality focused cloth. If you want to identify, analyze, and pressure test your own ideas around this theme, head straight to the US Large-Cap Defensive Dividend Stocks screener.
Elevance Health (ELV)
Elevance Health fits the screener brief as a large, dividend paying healthcare player that leans on recurring premium income and fee based services, which can look relatively steady when rate headlines are pushing money toward more defensive cash flows.
Elevance Health runs a broad US health benefits and services platform, with around US$170.4b from Health Benefits, US$45.1b from CarelonRx and US$30.1b from Carelon Services, supported by unallocated net investment income of US$3.0b. This gives it a roughly US$93.3b market value and a profile that aligns with the defensive dividend theme.
"Planned exits from Medicaid markets where Elevance Health does not see a path to sustainable performance, combined with efforts to improve rate alignment and mature care management in remaining contracts, is intended to move Medicaid operating margins higher from the expected 2026 trough and support longer term earnings quality."
The real swing factor for Elevance Health is how one still developing pressure on its cost structure ultimately shapes future margin stability.
That margin question is exactly what the full narrative for Elevance Health unpacks, highlighting where Elevance Health could see earnings quality accelerate and where risks might still be masking pressure.

Becton Dickinson (BDX)
Becton Dickinson is a global medical supplies and diagnostics group that fits this defensive dividend theme as a large healthcare player with a long history of paying income to shareholders and a roughly US$58.2b market value anchoring it in the large cap bracket.
For income investors, Becton Dickinson offers exposure to everyday hospital and lab equipment that tends to be used regardless of where interest rates go, while management keeps working on squeezing more output and cash from its manufacturing base.
"The BD Excellence operating system continues to drive roughly 8% plant productivity and is being extended into commercial, R&D and AI enabled supply chain."
The key question is how that productivity push interacts with one unresolved pressure that could either reinforce margins or quietly eat into them.
That unresolved pressure is exactly where the full narrative for Becton Dickinson picks up, showing how Becton Dickinson’s productivity push could be quietly accelerating or masking the real earnings story.
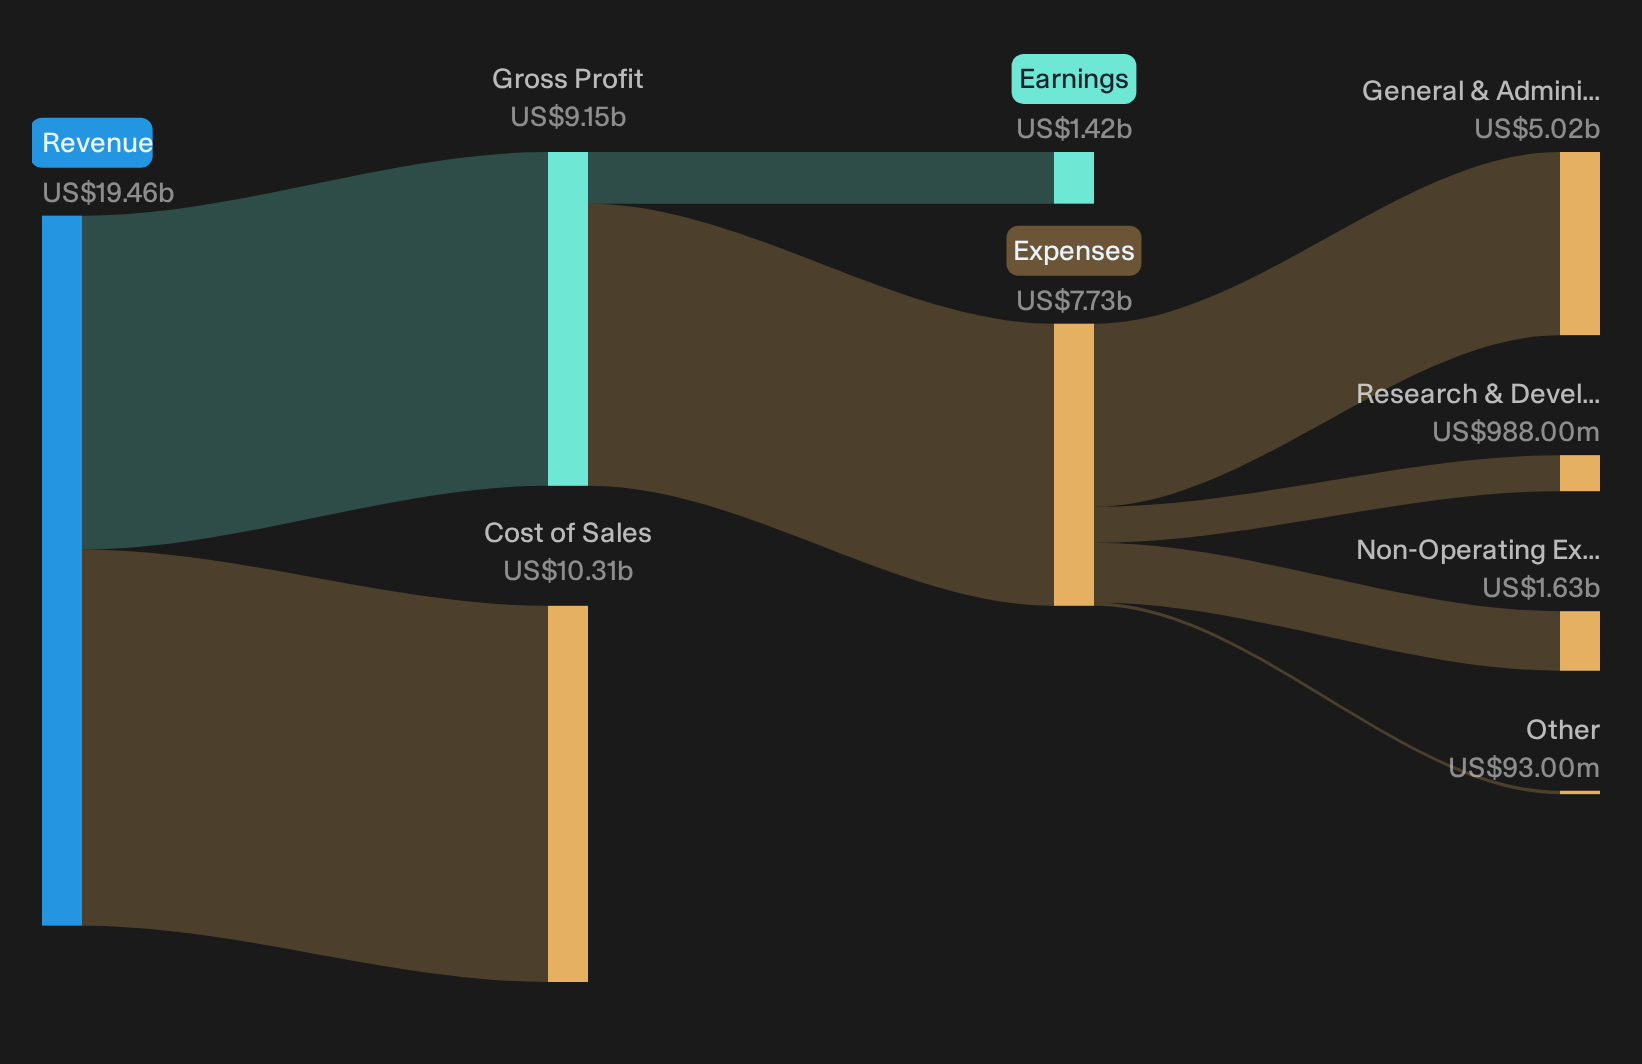
Cigna Group (CI)
Cigna Group combines a large US healthcare insurance platform with a growing set of pharmacy and care services. This gives it the kind of diversified, recurring cash flows that appeal in a defensive dividend screen focused on stability and income rather than excitement.
Cigna Group runs health insurance, pharmacy benefit management, and related care services for employers, individuals, and globally mobile workers. With a market value of about US$79.4b, it lands firmly in the large cap defensive healthcare bracket for dividend focused investors.
"Cigna Group is capitalizing on the growing demand for specialty pharmacy and care services, with recent 22% pretax earnings growth in Specialty & Care Services and a larger contribution from this segment, which points to further scaling potential that could support revenue growth and higher consolidated earnings."
That raises a key question for this income-focused story: what happens if one important part of the pharmacy benefits model changes how much profit ultimately reaches the bottom line?
If that profit share really starts to shift, the full narrative for Cigna Group shows where earnings power could be accelerating and which pressure points might still be quietly masking it.
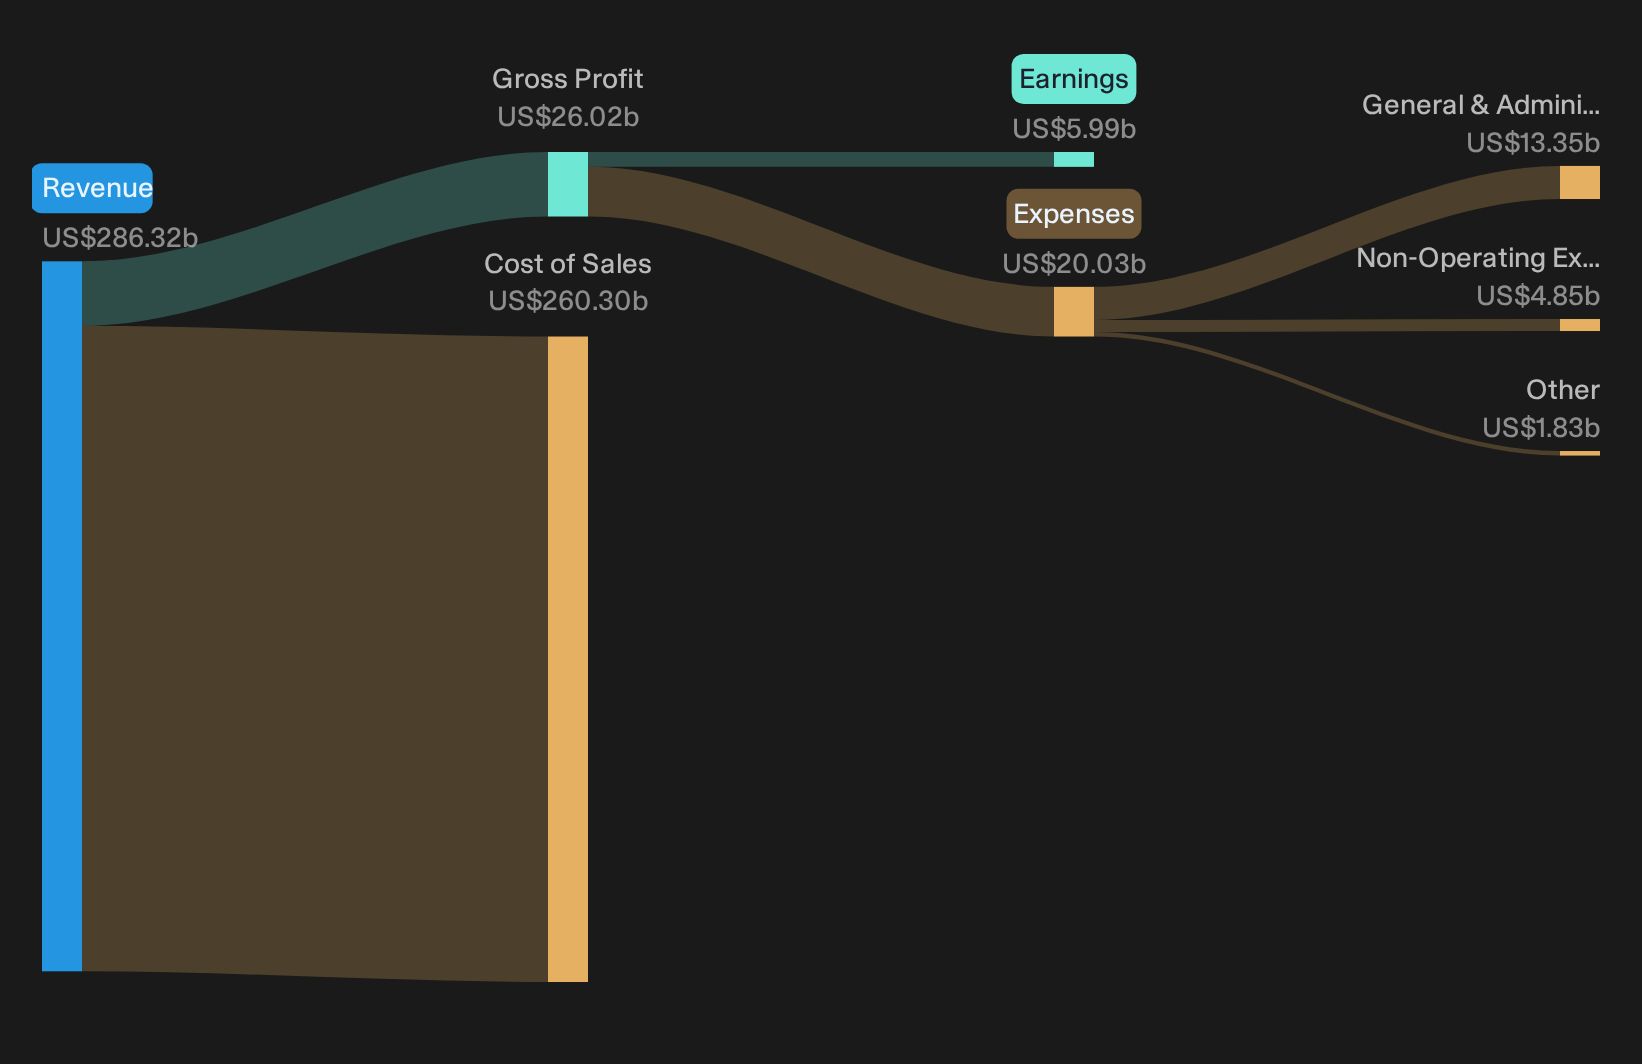
Seeking Alternatives Before The Crowd?
Fresh themes keep moving while attention lingers on yesterday's winners. Catch potential breakouts and shifting momentum under the radar for now. Window's open, act now.
- Target resilient cash generators that can still surprise the market by screening for list of solid balance sheet and fundamentals (24 results) before everyone else chases the same tickers.
- Ride powerful structural shifts by zeroing in on 42 power grid technology and infrastructure stocks as the grid upgrades story unfolds and capital starts flying toward infrastructure plays.
- Position ahead of the metals cycle by scanning 16 top copper producer stocks while sentiment is still mixed and quality operators quietly build momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com