
Eton Pharmaceuticals (ETON) Swings To Q3 Profit, Is The Stock Fully Priced?
Q3 earnings jolt for Eton Pharmaceuticals
Eton Pharmaceuticals (ETON) just posted a sharp turn in its third quarter of 2026, with revenue of US$57.93 million and net income of US$35.25 million replacing a loss a year earlier.
The strong Q3 headline has arrived after a steep rerating in Eton Pharmaceuticals’ stock, with a 1 day share price return of 19.75% and a year to date share price return of 247.23%, feeding into a very large 3 year total shareholder return of about 14x. Recent gains build on earlier momentum, with a 90 day share price return of 26.59% and a 1 year total shareholder return of 234.08%. The latest earnings swing is being read as a meaningful shift in both growth prospects and perceived risk around the rare disease portfolio.
Scan other fast moving rare disease and healthcare specialists by checking the hand picked 35 healthcare AI stocks.
Eton Pharmaceuticals now has the financial story to match its rare disease portfolio, yet a share price that is up more than 14x in three years sets a different test. Does the current tag still make sense?
Most Popular Narrative: 20% Undervalued
Eton Pharmaceuticals last closed at $56.46, compared with a widely followed fair value narrative of $71 per share that applies a 7.24% discount rate. That gap frames the current debate around whether the share price now fully reflects the rare disease portfolio and the new profitability profile.
Eton's investments in digital patient support platforms, targeted education campaigns, and specialist distribution (e.g., Eton Cares) are removing historical barriers to access and supporting higher therapy adoption and retention, driving increased penetration in niche markets and supporting recurring revenues.
See why 18 investors see Eton Pharmaceuticals as 20% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the story around Eton Pharmaceuticals can change quickly if key rare disease products face tougher pricing pressure or if planned label expansions encounter regulatory delays.
Find out about the key risks to this Eton Pharmaceuticals narrative.
Another View: Eton Pharmaceuticals on Earnings Multiples
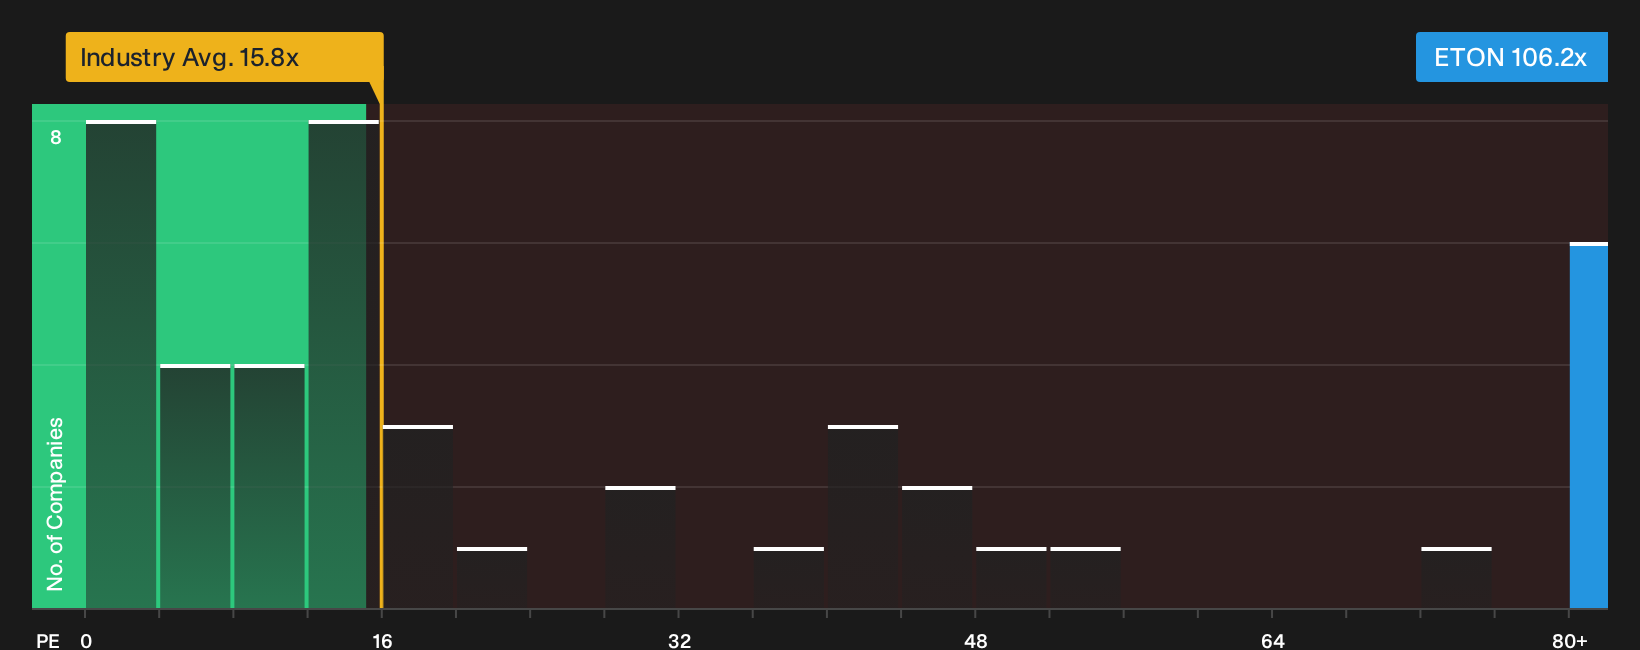
The fair value story around Eton Pharmaceuticals looks very different once earnings multiples come into focus. The stock trades on a P/E of 106.2x, compared with 15.8x for the US Pharmaceuticals industry, 33.8x for peers, and a fair ratio of 30.1x that the market could move toward over time.
Such a wide gap can signal optimism about future profits, but it also concentrates a lot of expectation into today’s tag. How comfortable are you with that trade off if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big move, bold story, and now the real work is deciding what it means for you. Put the recent swing in Eton Pharmaceuticals into context by weighing both the upside and the red flags through the 4 key rewards and 3 important warning signs.
Ready for more investment ideas beyond Eton Pharmaceuticals?
If Eton Pharmaceuticals has sharpened your focus, now is the moment to line up a broader watchlist using focused screeners built around quality, value, and resilience.
- Target potential bargains with proven fundamentals by scanning the 39 high quality undervalued stocks that pair healthier balance sheets with price tags that may not fully reflect those strengths.
- Prioritise resilience over excitement by reviewing a 29 resilient stocks with low risk scores that filters for companies with steadier risk profiles when market mood suddenly shifts.
- Hunt for off-the-radar opportunities by tracking a 19 high quality undiscovered gems that focuses on quality businesses yet to draw broad market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com