
Kratos (KTOS) Stock Jumps As Q3 Results Fuel Revenue Optimism
Kratos Defense & Security Solutions came into this Q3 2026 report with a bruised chart and a bullish story, after the stock fell over the past week, month and quarter. Then the new numbers hit and the script flipped. The shares rose 5.2% to about US$35 on Friday as investors focused on one thing above all else: another quarter of heavy revenue, with Q3 sales at US$471.8 million in a defense market that emphasizes dependable top line and funded programs.
Like the revenue momentum at Kratos Defense & Security Solutions but want more ideas anchored by strong funding visibility and balance sheets in the defense and infrastructure space? Scan the list of solid balance sheet and fundamentals stocks (24 results) for a curated set of stocks built around that same profile.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$471.8 million vs. US$347.6 million (large increase in quarterly sales)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): loss of US$0.2 million vs. profit of US$8.7 million (swing into a small loss)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$0.0011 per share vs. earnings of US$0.0510 per share (moved from profit to a slight per share loss)
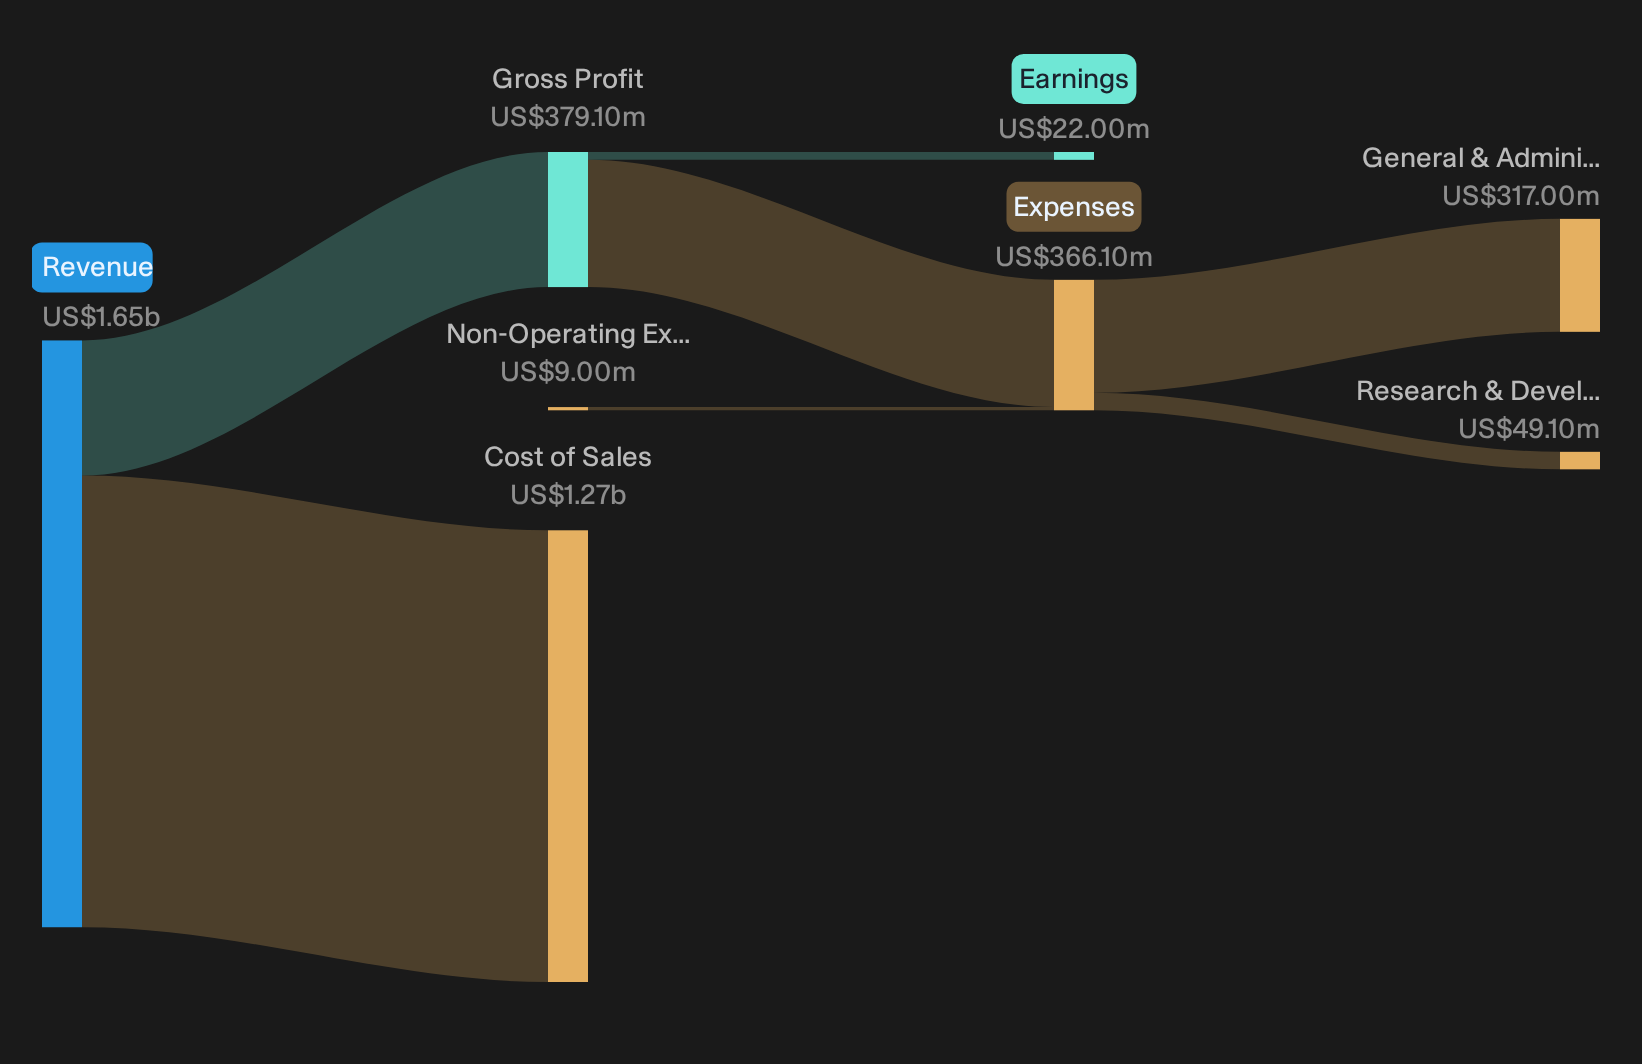
- Trailing 12-Month Net Income (to Q3 2026 vs. to Q3 2025): US$22.0 million vs. US$20.0 million (modest improvement in full year earnings power)
Revenue is racing ahead while the stock trades below modeled value. Ask Charlie what makes Kratos’ growth look underpriced.
Kratos Q3 Print Tests The Growth Engine Story
The bullish pitch around Kratos Defense & Security Solutions hinges on turning big program wins into real throughput and cash. That vision is summed up here.
"The key requirement is that Kratos converts its heavy upfront investment in new facilities, engines, and hypersonic capacity into sustained production volumes and cash generation, despite working capital pressure and foreign exchange headwinds."
Q3 shows tangible progress on the first half of that sentence. Revenue reached US$471.8 million, hypersonics and unmanned platforms helped drive a 2.2x book to bill, and backlog climbed to a record level. Adj. EPS of US$0.24 beat expectations, yet reported earnings hovered around breakeven, so cash generation and margin lift remain unproven.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Kratos Bear Case: Cash Strain More Than Theory
Critics argue that Kratos Defense & Security Solutions is over committing to capacity and inventory ahead of firm production, putting cash and margins at risk.
"While Kratos is positioning affordable unmanned systems and loitering munitions as high volume production businesses, large upfront engine and airframe component orders for thousands of units risk locking in inventory and fixed costs ahead of firm orders, which may keep working capital consumption elevated and delay any improvement in operating cash flow."
Q3 results reflect parts of that concern. Revenue reached US$471.8 million and adjusted EPS exceeded expectations, yet GAAP results were roughly breakeven and trailing 12 month profit of US$22.0 million remains modest relative to the scale of ongoing facility builds and inventory commitments.
Hunt Quiet Setups Before They Run
Kratos Defense & Security Solutions just showed how a headline revenue story can mask mixed earnings quality. The real opportunity is spotting companies that could be undervalued before stronger fundamentals get fully recognized.
- Company 1 - 48% below our estimate - use a purpose-built digital platform to deepen primary small business banking relationships while scaling loans and deposits.
- Company 2 - 33% below our estimate - expand a coconut-based drinks category as a former niche product becomes mainstream across branded and private label shelves.
- Company 3 - 49% below our estimate - grow an asset-light hotel network while attaching a retail ecosystem that rides rising guest traffic through franchise locations.
Those are three of them. See all 41 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com