
Magnite (MGNI) Following Its Q3 Earnings Beat And Raised Outlook Has Valuation Back In Focus
Magnite (MGNI) recently reported third quarter 2026 earnings that exceeded revenue and profit expectations, improved connected TV metrics, and prompted management to raise full-year guidance across several key performance measures.
The latest earnings beat has been met with sharp buying interest, with Magnite’s 1-day share price return of 20.75% and 7-day share price return of 28.06% lifting the stock to US$27.52. That move builds on year-to-date share price gains of 71.36%, and a much longer track record reflected in a 3-year total shareholder return of 275.44%. This frames today’s reaction as part of a broader rerating story rather than a one-off spike.
Scan how Magnite’s surge compares with other advertising and media platforms by reviewing the hand-picked 42 high quality undervalued stocks, which combine momentum with stronger fundamentals.
After a 71% year to date climb and a sharp jump on earnings, Magnite now presents a simple choice: lean into this momentum today or wait for a cooler entry and risk missing it.
Most Popular Narrative: 7% Undervalued
Magnite's most followed narrative pegs fair value at $29.67, a touch above the latest $27.52 close. This puts the recent rally in the context of a still modest valuation gap built on specific connected TV and data monetization assumptions.
Magnite is positioned to benefit from the accelerating shift of ad spend from traditional TV to digital and connected TV platforms, with recent CTV contribution ex TAC of US$97 million at 51% of total contribution ex TAC and top 10 CTV accounts growing in the mid to high 40% range, which directly affects future revenue mix and contribution ex TAC.
See why 13 investors see Magnite as 7% undervalued.
Result: Fair Value of $29.67 (UNDERVALUED)
Still, Magnite’s reliance on a concentrated group of large CTV streamers and ongoing pressure on open web display could quickly weaken the current CTV-led narrative.
Find out about the key risks to this Magnite narrative.
Another Look At Magnite’s Valuation
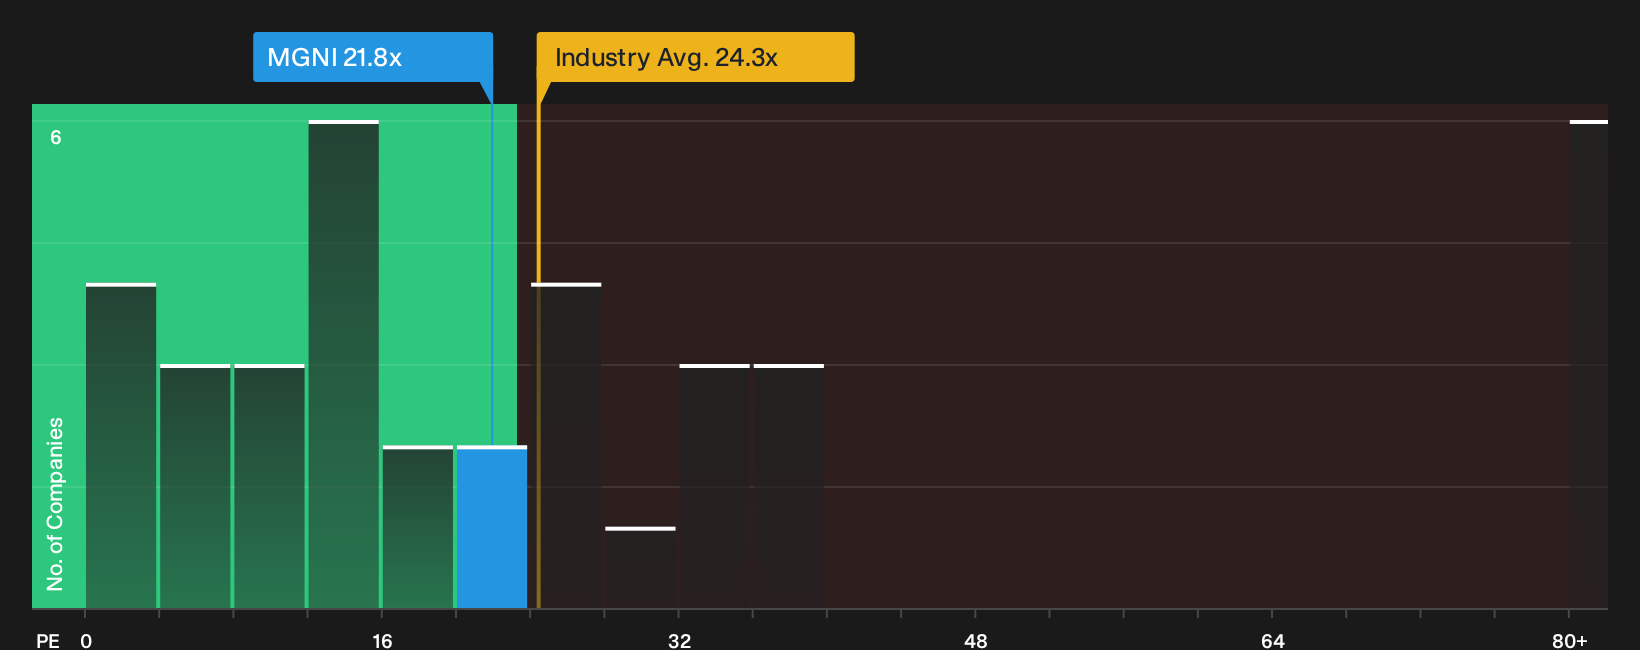
On simple P/E math, Magnite screens cheaper than both peers and the wider US Media group at 21.8x vs 34.8x, yet it trades above an estimated fair ratio of 14x. That gap hints at either opportunity or valuation risk. Which side do you think the market is slowly pricing in?
For a closer view of how this pricing compares with similar businesses and where the fair ratio suggests the market could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Magnite for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Magnite’s valuation and business drivers create a split verdict, so move quickly, interrogate the numbers for yourself, and weigh the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Magnite?
If Magnite has sharpened your appetite for opportunities, do not stop here. Broaden your watchlist with fresh ideas that match your risk, income, and quality preferences.
- Target higher upside potential by scanning the 9 elite penny stocks with strong financials that pair early-stage growth stories with stronger balance sheets and fundamentals.
- Zero in on resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without constant refinancing or dilution pressure.
- Prioritise income and durability by focusing on 6 dividend fortresses that combine meaningful yields with healthier payout support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com