
Western Digital (WDC) Growth Story Faces New AI Datacenter Rule Risk
- Western Digital (NasdaqGS:WDC) is facing new concern after a Democratic election win raised the prospect of tighter AI datacenter rules in early November 2026.
- Investors are weighing whether potential federal scrutiny of large scale server farms could affect future storage demand tied to AI training and inference.
- Early policy discussions have focused on energy use, grid impact, and siting approvals for new hyperscale facilities that consume significant power.
- The fresh political push around AI datacenter oversight is only part of the story for Western Digital's AI driven storage outlook. We have also spotted 4 other big wins worth knowing about at Western Digital.
This regulatory theme reaches far beyond Western Digital and affects a wider group of stocks tied to AI infrastructure buildouts. 53 AI infrastructure stocks
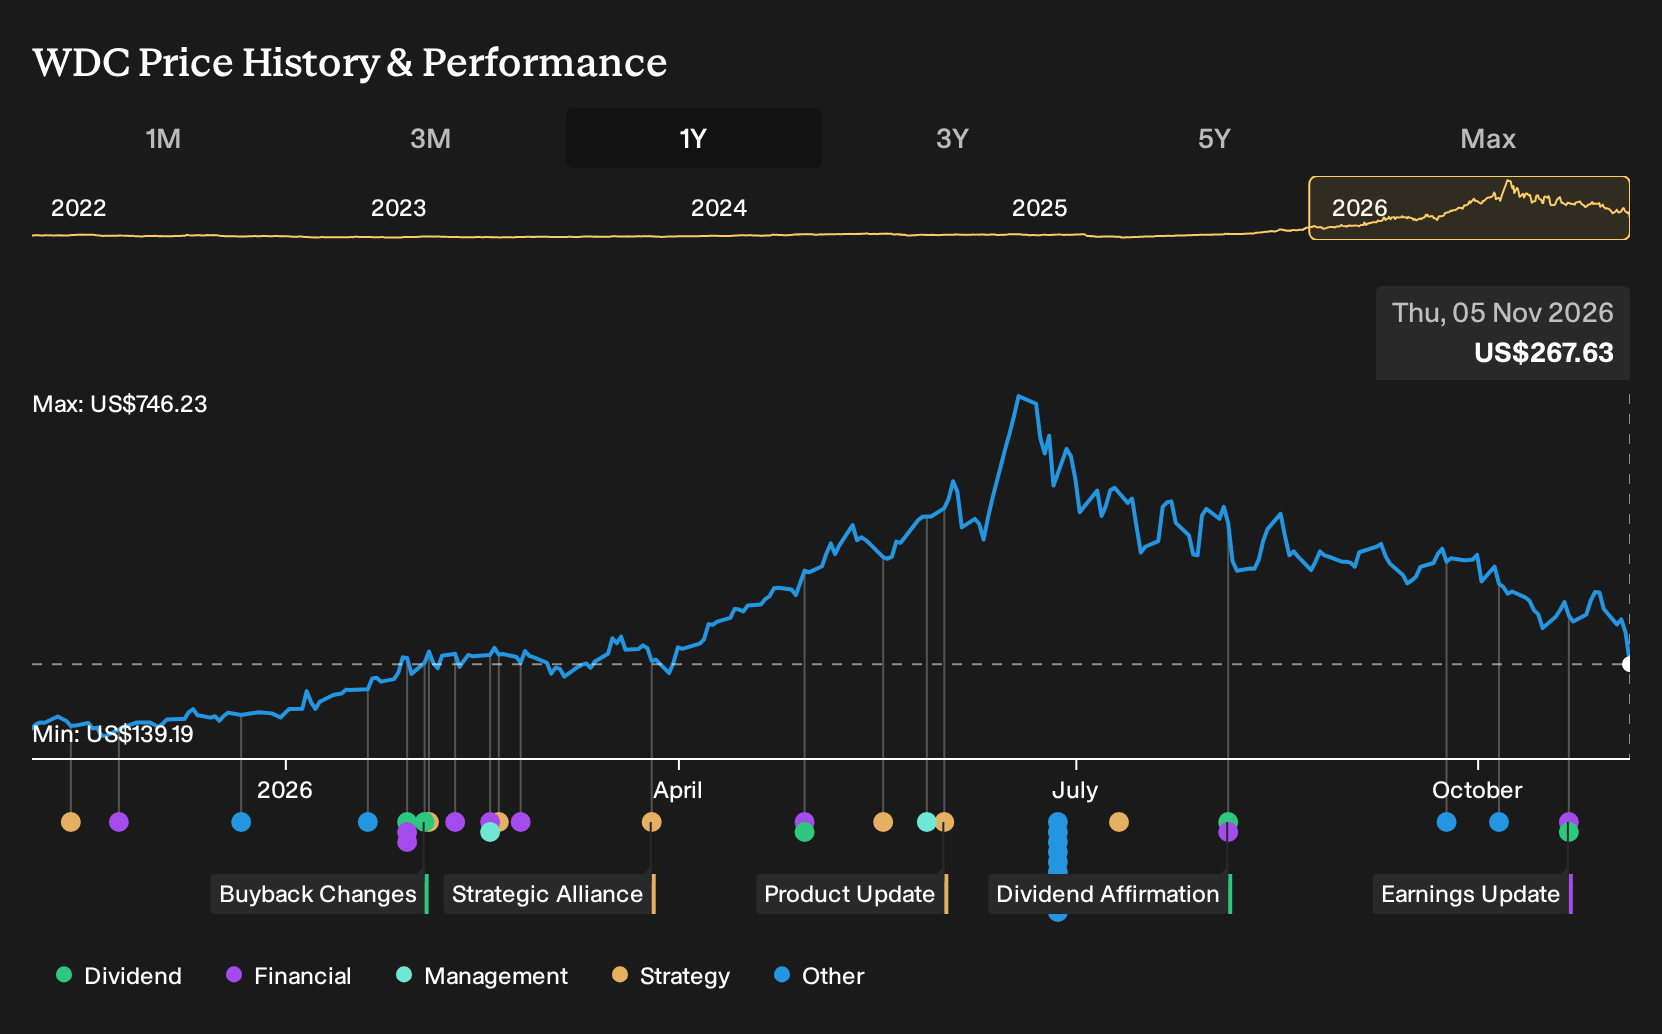
Western Digital, a US based Tech group with a market cap of $121.2b, develops and sells hard disk drive based storage hardware that sits inside the servers powering AI workloads. That direct link to physical datacenter buildout is what puts the business in the crosshairs of any new infrastructure rules.
See how Western Digital's balance sheet measures up.
Regulatory heat on AI datacenters presses Western Digital’s Narrative where it is strongest
The Western Digital Narrative assumes AI workloads keep demanding ever more HDD capacity while the firm steadily cuts cost per terabyte and funds shareholder returns from that cash engine. Tighter AI datacenter oversight questions how smooth that storage buildout really is.
"The explosive increase in unstructured data generated by AI applications, Agentic AI, and cloud-based services across industries is still driving unprecedented storage needs…"
See how the full story points towards a $613 fair value for Western Digital.
The regulatory push spotlights a key bullish pillar. Western Digital’s multi-year cloud agreements and high-capacity ePMR and UltraSMR drives are tied directly to hyperscale build plans that could face new siting, energy use or permitting hurdles. If AI datacenter rollouts slow or shift geographically, the timing of exabyte shipments in that Narrative becomes less straightforward.
There is also a bear-side echo. Analysts already flag HAMR transition risk and the threat of HDD oversupply from rivals like Seagate or Toshiba. Extra compliance costs or caps on large server farms would add another constraint just as Western Digital is managing higher capital needs and non-cash-heavy earnings, which could sharpen scrutiny of how durable its current profitability really is.
For you as an investor, this regulatory story only really matters in how it changes the version of Western Digital’s long-term storage demand and margin path that you choose to believe.
One big Western Digital question this article has not touched
The unresolved piece is what Western Digital might be worth if you only follow the money and build a view from its future cash streams, then line that up against today’s share price. Find out exactly what Western Digital is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com