
Is Gorman Rupp (GRC) Fully Priced On Strong Q3 Results And A Dividend Raise?
Why Gorman-Rupp Is Back On Investor Screens
Gorman-Rupp (GRC) is drawing fresh attention after reporting year-over-year gains in third quarter sales and net income, along with a higher quarterly dividend that extends its long record of annual payout increases.
Recent trading tells a mixed story. Gorman-Rupp’s share price has retreated sharply in the short term, with the stock down 11.82% over the past month and 18.74% over ninety days. At the same time, the year-to-date share price return of 41.44% sits alongside a 1-year total shareholder return of 53.60% and a 3-year total shareholder return of 136.83%, suggesting longer term momentum remains strong while the latest earnings and dividend news reset expectations around growth potential and risk.
Scan other income and dividend stories that echo Gorman-Rupp’s profile by reviewing our curated list of 6 dividend fortresses.
Gorman-Rupp now appears to be a stronger enterprise based on recent results, yet the share price has pulled back sharply in the short term. Is this quality business trading at a fair price today, or not?
Preferred P/E Multiple Of 24.4x: Is It Justified For Gorman-Rupp?
At a last close of $68.09, Gorman-Rupp trades on a P/E of 24.4x, which points to a richer valuation than its own estimated fair P/E yet only a fractionally higher level than the wider US Machinery group.
The P/E ratio compares the current share price with earnings per share. For a manufacturer like Gorman-Rupp, that figure gives you a quick look at how much investors are currently paying for each dollar of profit, which matters when earnings are already established rather than highly speculative.
On this measure, the stock is described as good value against a peer average of 28.7x, which suggests the market is not pricing its profits at the top of the sector range. At the same time, the current 24.4x multiple is labeled expensive versus an estimated fair P/E of 18.4x, a level that signals where valuation could shift if sentiment or growth expectations cool from here.
Compared with the broader US Machinery industry at 24.3x, Gorman-Rupp trades on virtually the same headline earnings multiple, so any edge for investors is more likely to come from how profits, debt and cash flows evolve rather than a clear-cut discount or premium on this single metric.
Explore the SWS fair ratio for Gorman-Rupp.
Result: Price-to-earnings of 24.4x (ABOUT RIGHT)
Still, Gorman-Rupp faces pressure if demand for industrial and construction projects softens, or if higher borrowing costs weigh on capital spending and valuation multiples.
Find out about the key risks to this Gorman-Rupp narrative.
Another View On Gorman-Rupp’s Value
The P/E of 24.4x presents Gorman-Rupp as roughly in line with Machinery peers, yet the SWS DCF model points in a different direction. On that framework, the shares trade at $68.09 compared with an estimated future cash flow value of $119.33, which implies a wide valuation gap. This raises the question of whether the cash flow perspective may be highlighting something that the earnings multiple does not capture.
Look into how the SWS DCF model arrives at its fair value.
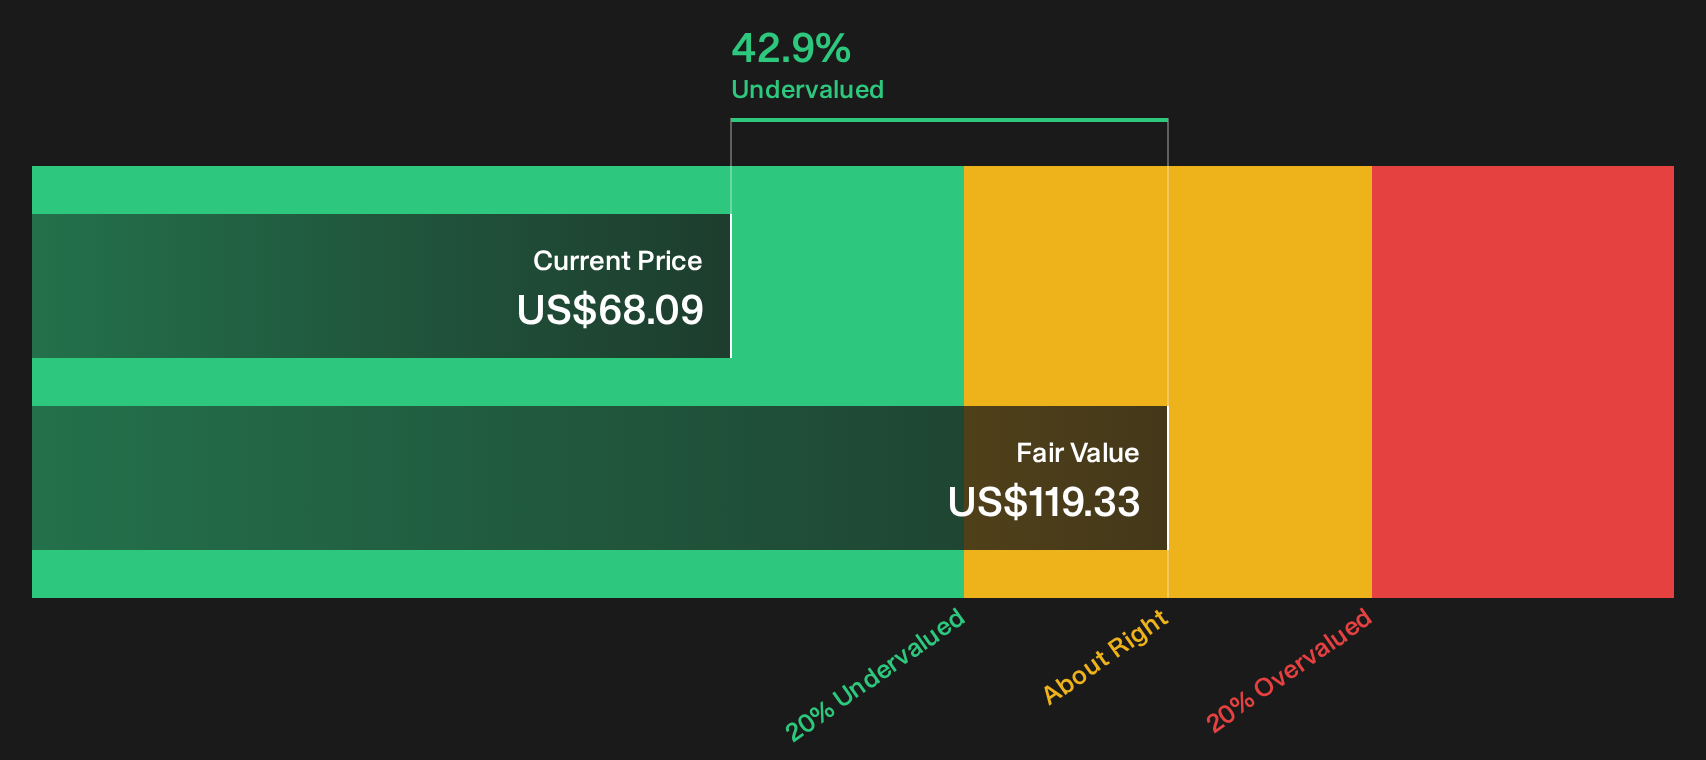
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Gorman-Rupp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Gorman-Rupp so far. Short term pullback, longer term strength, plus both flagged risks and potential rewards mean your own judgment matters now. To weigh those trade-offs and see what stands out most for you, start with a clear view of the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Gorman-Rupp?
If Gorman-Rupp has sharpened your focus on quality and price, do not stop here. The next opportunity on your list could already be live on Simply Wall Street’s tools.
- Target resilient balance sheets and steadier fundamentals by reviewing a curated list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio.
- Hunt for potential mispriced opportunities by scanning a focused 42 high quality undervalued stocks that applies consistent rules instead of gut feel.
- Stack your income ideas by running through a hand picked 21 high quality undiscovered gems before the wider market pays closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com