
What Yalla Group Doubters Saw Before The Drop
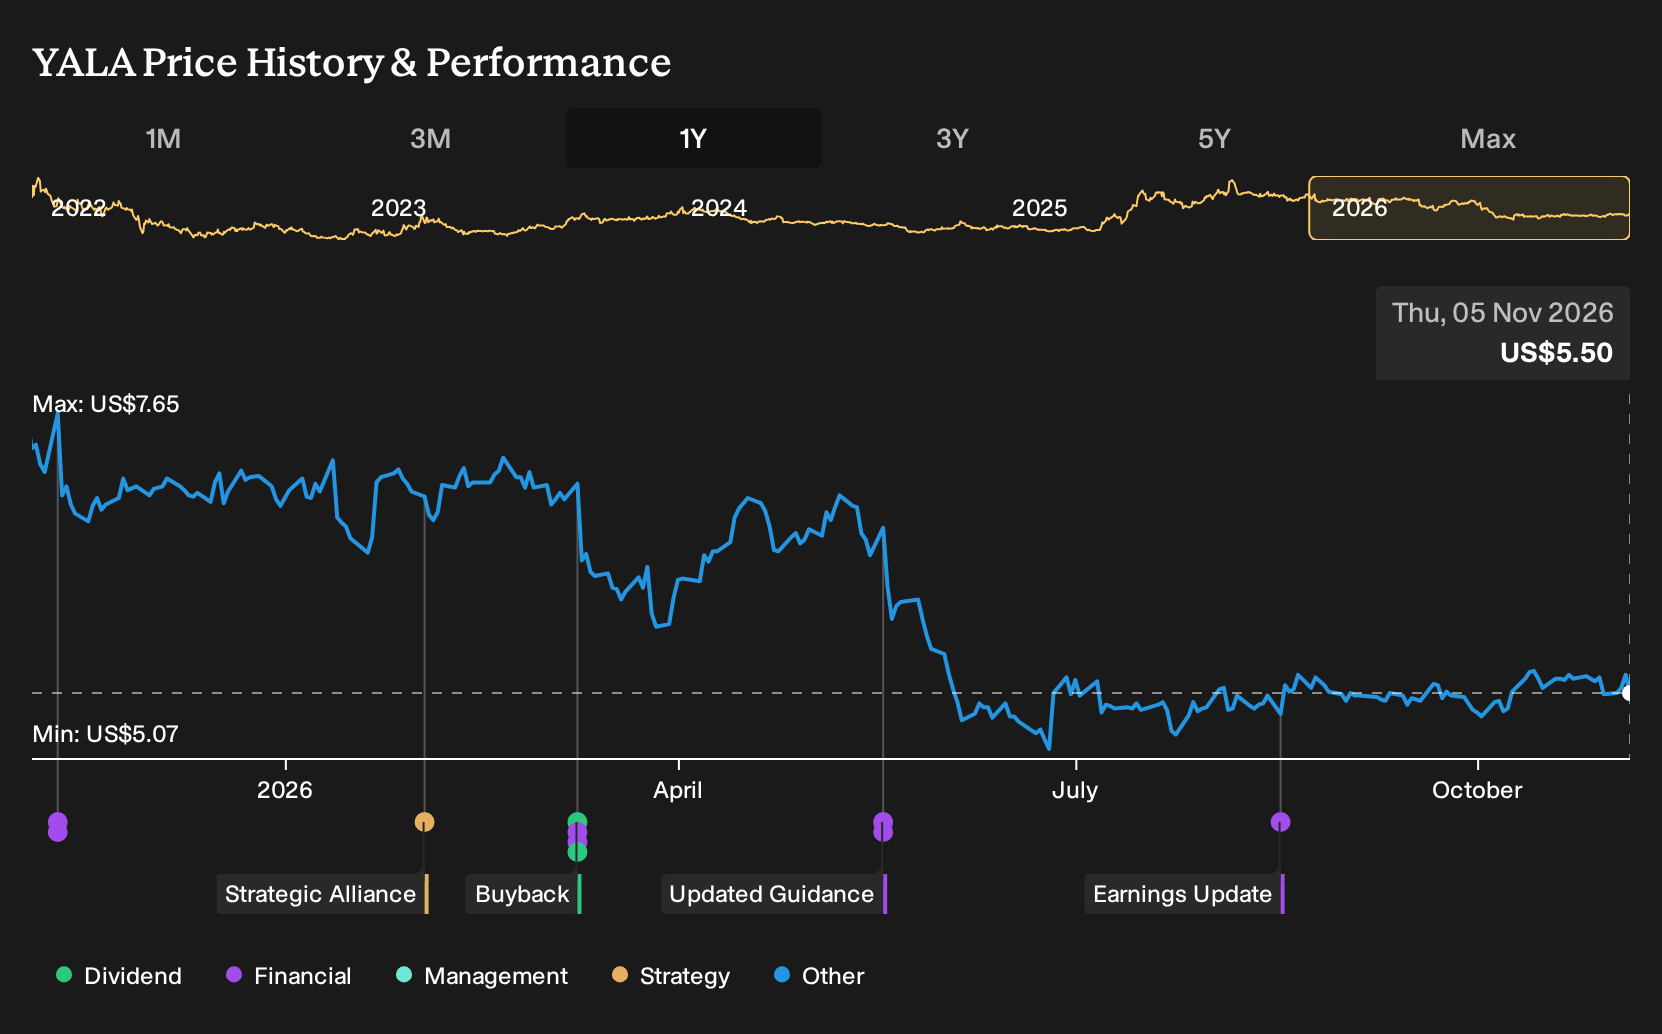
Yalla Group’s latest update was Q1 2026, when it reported softer revenue and earnings alongside geopolitical pressure in its core MENA markets, but highlighted traction in newer gaming titles and a fresh US$150 million buyback plan. Investors who held Yalla Group over the past year are down 24.2%, including dividends. If you had locked in a position back on 5 November 2025, how should that mix of user growth, margin pressure, and capital returns now be weighed?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The move put Yalla Group in the middle of this trade. Scan 18 cryptocurrency and blockchain stocks for other companies exposed to it.
The Two Stories Investors Were Weighing On Yalla Group
The shares cost US$7.41 at the start of the period, which left investors choosing between two very different stories about where Yalla Group might be headed.
On the optimistic side, the bullish narrative put fair value at US$9.27, based on revenue growth assumptions of 5.4% a year and profit margins settling at 39.6% over a 3 year window.
The bearish view anchored fair value at US$6.5, stressing rising MENA regulatory scrutiny, higher compliance costs, and pressure on data privacy that could squeeze profits and limit flexibility.
What The Results Changed For The Yalla Group Story
The Q2 2026 report showed Yalla Group with revenue of US$82.6 million and net income of US$31.8 million, both lower than Q2 2025. Net margin slipped from 43.5% to 38.5%, which challenged the bullish assumption that profitability would settle closer to 39.6% while staying resilient.
The key lesson is simple. When a thesis rests on margin strength, you should track net margin alongside growth claims and compare each new quarter to the profitability path that was originally assumed.
What You Are Paying For In Yalla Group Today
Today Yalla Group trades at US$5.5, with the selected Narrative arguing that its Fair Value sits above that level based on newer gaming titles, AI tools, and continued buybacks offsetting pressure on older social products.
For that higher figure to make sense, a buyer now would need confidence that new games and AI supported services turn heavier spending into resilient margins and a larger earnings base.
"The key factor is that investment in new games and AI tools converts higher marketing and R&D spending into game services that can represent a larger share of the revenue mix while margins remain resilient."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond Yalla Group’s Apps
Yalla Group leans heavily on engagement and digital attention. That same attention can matter one step upstream.
Advertisers and enterprises still need places where users search, watch, and work. Another giant ecosystem offers that mix at broad global scale.
This other platform turns everyday queries, video viewing, and online collaboration into paid digital advertising and paid cloud services.
Its push into AI tools across productivity software and data infrastructure keeps those revenue engines closely linked.
If your thesis on Yalla Group centers on user time online, this broader gateway to search, video, and enterprise AI may deserve closer study.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 53% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com