
Unusual Machines (UMAC) After Q3 Loss And Sales Update Is The Selloff A Buying Chance
Unusual Machines (UMAC) is back in focus after its third quarter 2026 update, reporting sales of US$13.9 million and a net loss of US$25.04 million, reshaping the risk profile for investors.
The sharp 1 day share price return of down 17.57%, on top of a 7 day share price move of down 37.85% and a 30 day share price return of down 51.97%, suggests Unusual Machines’ recent earnings release and acquisition headlines are being treated as raising execution and funding risks. This is occurring even though the 1 year total shareholder return is roughly flat at down 0.09% and short term momentum has clearly faded from earlier in 2026.
Scan how other defense and robotics players are reacting to similar funding and earnings shocks by reviewing our hand-picked 88 robotics and automation stocks alongside Unusual Machines’ latest moves.
After a drop this steep, either Unusual Machines is finally resetting closer to its real worth, or most of the easy upside has already been given back. The valuation work now matters a lot more.
Most Popular Narrative: 72.5% Undervalued
Analysts following Unusual Machines frame a fair value of $39.00 against the last close of $10.74, which signals a big gap that hinges on ambitious growth, profitability, and discount rate assumptions rather than recent price swings alone.
Significant government policy changes and increasing U.S. federal investment in drone technology are set to unlock material new demand for domestically sourced drone components. Unusual Machines' expectation of imminent and sizable government orders, including multiple customers vying for contracts like the $500 million PBAS program, positions the company to capture a large share of a rapidly expanding market, which is likely to drive sequential revenue growth over the next several quarters.
See why 40 investors see Unusual Machines as 72% undervalued.
That fair value of $39.00 is built on a discount rate of 8.84%, rapid revenue expansion assumptions, and a move from current losses toward a positive profit margin profile over the coming years. The same narrative points to a future P/E multiple above the wider U.S. Electronic sector, which means the gap to the $10.74 share price rests heavily on the belief that Unusual Machines can convert government interest, domestic manufacturing buildout, and higher margin enterprise sales into durable earnings.
Result: Fair Value of $39.00 (UNDERVALUED)
Still, the whole Unusual Machines narrative leans heavily on timely U.S. government orders and smooth factory expansion, so contract delays or scale up missteps could quickly challenge it.
Find out about the key risks to this Unusual Machines narrative.
Another View: What Multiples Say About Unusual Machines
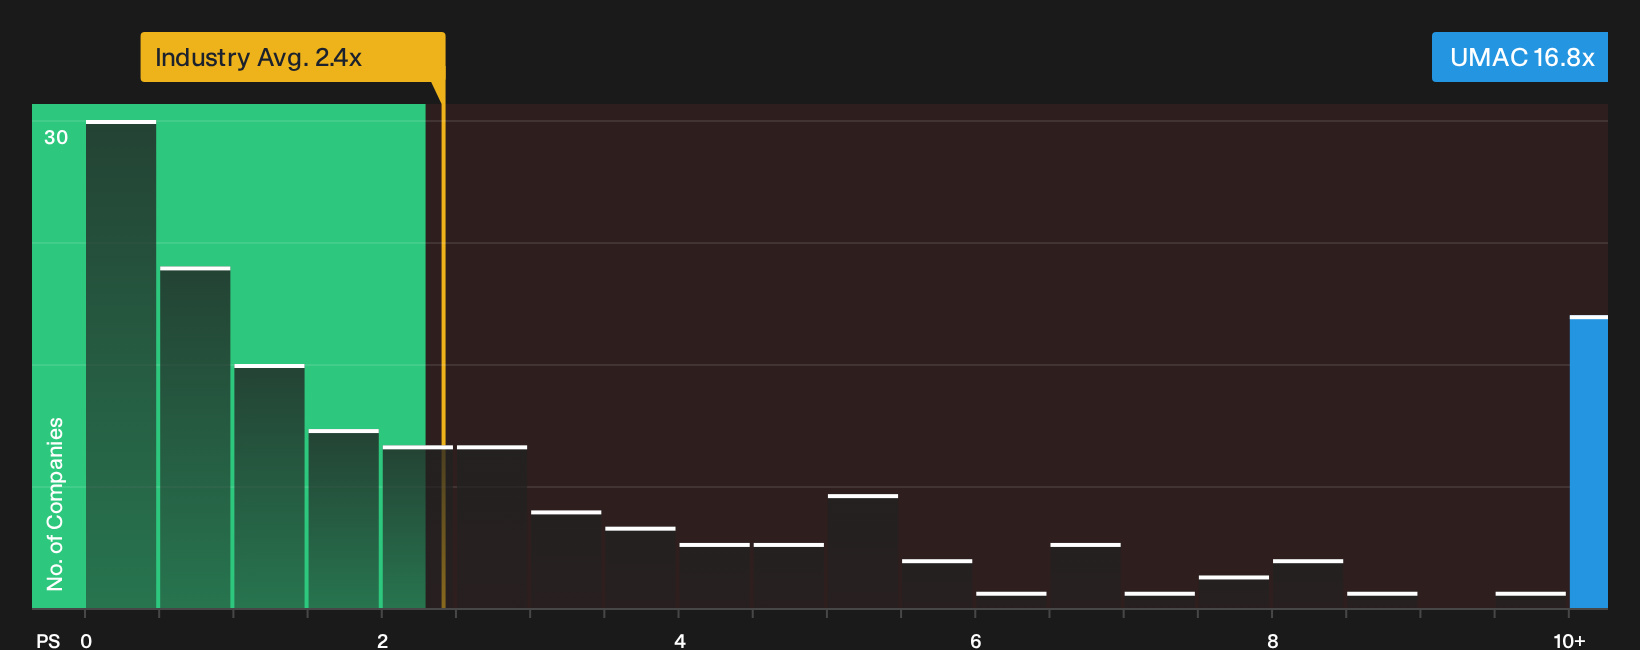
There is a very different signal when Unusual Machines is viewed through its P/S ratio. The stock trades at about 16.8x sales, while the US Electronic industry sits near 2.4x and the fair ratio for UMAC is estimated at 4x. That gap points to rich expectations. The question is whether you think the story justifies paying that kind of premium.
To see how this pricing gap fits into a fuller valuation picture, including how peers are trading on similar metrics, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Unusual Machines is split right now, so move quickly, review the latest data yourself, and weigh both the risks and potential upsides. To see a concise breakdown of both sides of that ledger, including the key issues investors are watching, 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Unusual Machines?
If Unusual Machines has sharpened your focus on risk and reward, do not stop here. The strongest portfolios often come from comparing several clear, data backed ideas side by side.
- Target higher quality at reasonable prices by scanning a curated pool of companies using the 42 high quality undervalued stocks, which filters for both strength and potential mispricing.
- Build a steadier core in your portfolio by zeroing in on income focused opportunities with the 6 dividend fortresses, which highlights companies offering yields from 5% and above.
- Limit downside shocks by focusing on sturdier balance sheets through the 32 resilient stocks with low risk scores, which spots resilient businesses with lower risk scores before others catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com