
Earnings Miss Might Change The Case For Ziff Davis Stock
- Ziff Davis reported third quarter 2026 sales of US$289.33 million, compared with US$306.53 million a year earlier, alongside a net loss of US$28.69 million from continuing operations and basic and diluted loss per share of US$0.85.
- Across the first nine months of 2026, Ziff Davis generated US$843.71 million in sales and US$618.03 million in net income, with very high basic and diluted earnings per share of US$17.22 that contrast sharply with the loss per share from continuing operations.
- We will look at how Ziff Davis's investment narrative holds up in light of weaker quarterly sales and a larger loss from continuing operations.
Compare Ziff Davis with a curated group of peers that currently screen well on fundamentals using our hand picked 21 high quality undiscovered gems as a starting list for your next idea.
Ziff Davis Investment Narrative Recap
To stay invested in Ziff Davis, you need to believe the mix shift toward subscription, cybersecurity and martech can offset pressure on ad driven properties over time. The latest quarter adds tension to that view. Sales from continuing operations softened and the loss from those activities widened, which keeps the core profitability question very much open.
The key near term catalyst is how management deploys the sizeable cash and balance sheet capacity after the Connectivity sale, including acquisitions and buybacks. The biggest risk is that search driven and healthcare related media assets stay under pressure, so incremental capital fails to lift revenue or margins meaningfully against those headwinds.
RetailMeNot’s 20th National Cash Back Day event is a useful real time test of Ziff Davis’s Shopping and affiliate ecosystem. The promotion spans more than 3,500 retailers and offers elevated cash back rates, so it gives a live read on consumer engagement, advertiser appetite and how well the RetailMeNot platform converts traffic into monetizable transactions.
If these types of events keep users active and brands spending through the holidays, they can support the push toward more performance oriented digital advertising and e commerce that analysts have focused on as a catalyst. If uptake is weaker than hoped, it would underline the risk that Tech & Shopping properties remain under structural pressure from search changes and tougher competition.
Ziff Davis' current earnings are a loss of US$29.7 million, while analysts expect earnings to reach US$34.8 million by 2029. This implies an earnings swing of about US$64.5 million, alongside a projected annual revenue decline rate of 7.2% and forecast revenues of US$1.2 billion in 2029.
Uncover why Ziff Davis' fair value indicates a 17% potential upside to its current price before other investors close that gap.
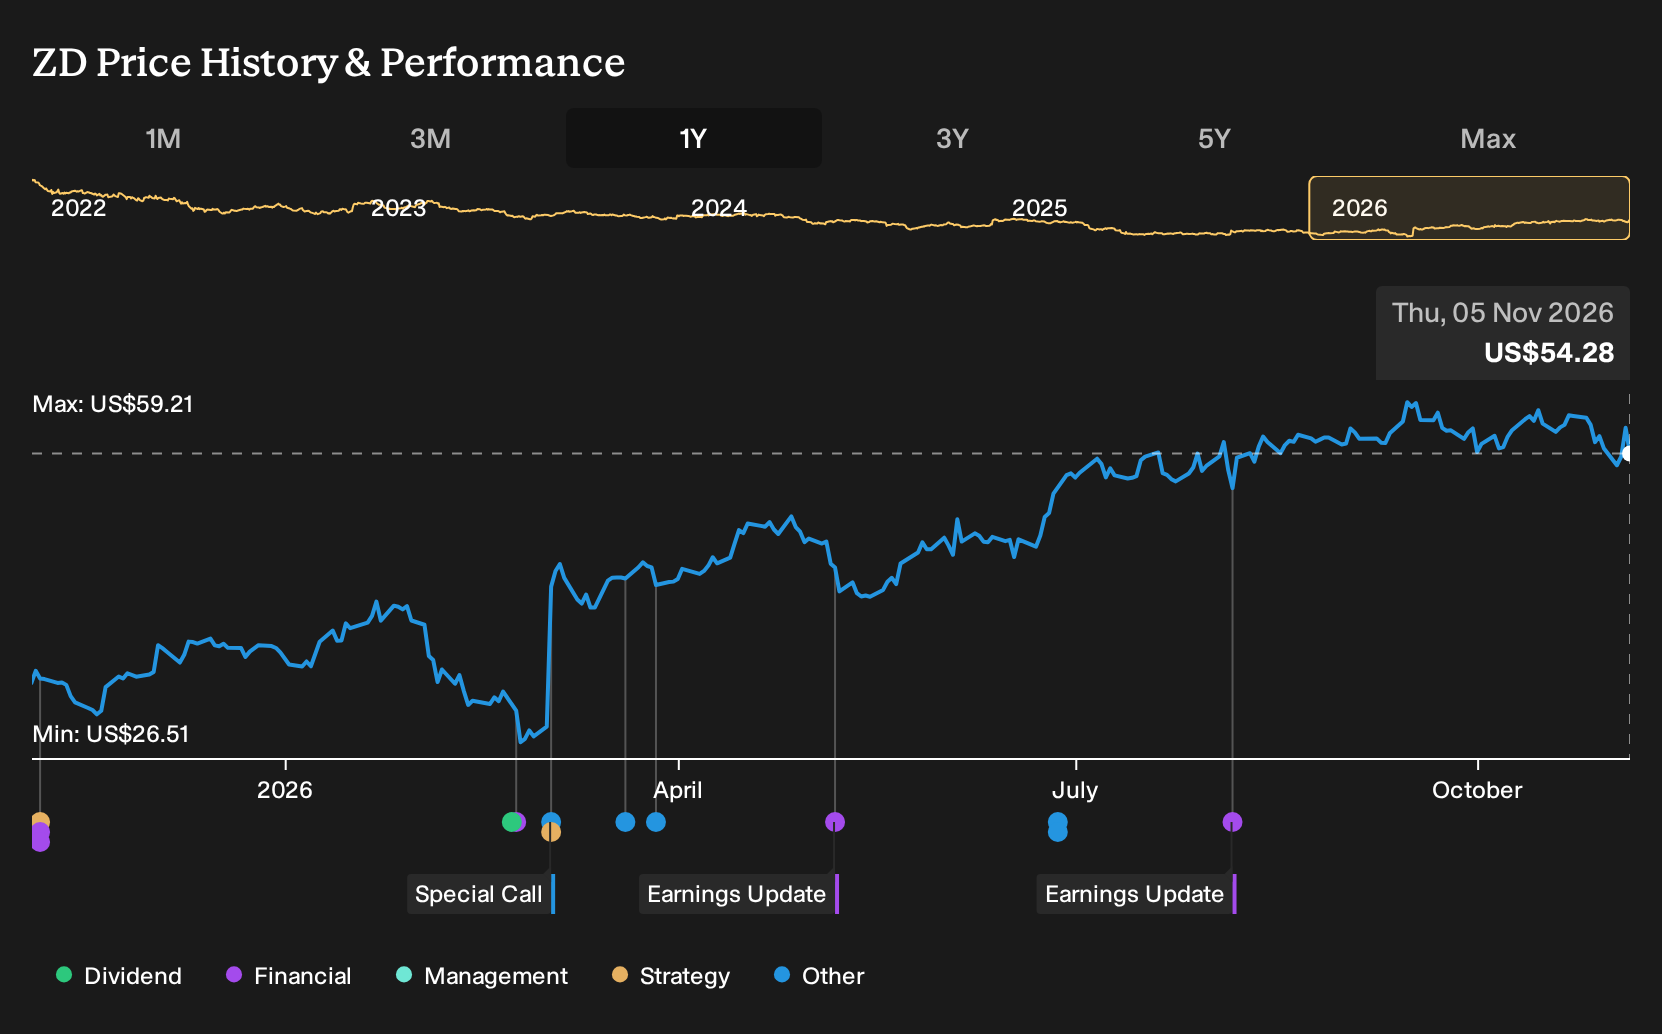
Exploring Other Perspectives
One alternative view focuses less on buybacks and more on the risk that Ziff Davis cannot fully offset weaker ad driven income. The most cautious analysts already assumed revenue of about US$1.2b and earnings near US$52.2 million by 2029 before this earnings miss, so their story now looks much tougher than the consensus path. These forecasts were all set before the latest quarter, so you should expect opinions, and possibly the numbers behind them, to move around as new data comes through.
Explore another Ziff Davis fair value estimate, including one that suggests it could be worth just $63.67.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ziff Davis research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ziff Davis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ziff Davis' overall financial health at a glance.
Looking For More Ideas Beyond Ziff Davis?
If the Ziff Davis story leaves you wanting a broader watchlist, it can help to line it up against other businesses that already screen well on quality, value or resilience. The Simply Wall St Screener offers curated starting points so you can quickly focus on stocks that better match your risk tolerance and income goals.
- For investors who care most about financial strength and solid fundamentals, start with this list of solid balance sheet and fundamentals (24 results) as a way to focus on sturdier businesses.
- If your priority is finding attractively priced opportunities, use the 42 high quality undervalued stocks to zero in on stocks that currently combine quality with appealing valuations.
- For readers who want income that feels more robust, the 6 dividend fortresses can help you concentrate on companies offering higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com