
Did Raised Revenue Guidance Just Shift Howmet Aerospace (HWM) Stock's Investment Narrative?
- Howmet Aerospace reported third quarter 2026 sales of US$2,703 million and net income of US$567 million, with basic earnings per share from continuing operations of US$1.42. The company also reported higher nine month sales and profit compared with the same period in 2025.
- The business lifted its 2026 revenue guidance baseline to about US$10.3b and outlined 2027 revenue expectations of roughly US$11.5b, highlighting management confidence in demand across aerospace and industrial gas turbine markets.
- This article examines how Howmet Aerospace's raised 2026 and 2027 revenue guidance reshapes the investment narrative built around capacity expansion.
Scan beyond Howmet Aerospace and see which peers are also leaning into high performance alloys and aerospace demand with our curated 21 high quality undiscovered gems.
Howmet Aerospace Investment Narrative Recap
For a shareholder in Howmet Aerospace, the core belief is pretty simple. You need to think demand for advanced engine parts, fasteners and industrial gas turbine components stays healthy enough for the current capacity build to remain well used. The raised 2026 baseline revenue guidance of about US$10.3b and the new 2027 outlook around US$11.5b feed directly into that view.
The main near term catalyst is execution on this high capex expansion while keeping margins and cash generation on track. The biggest operational risk is that aerospace or turbine demand proves less resilient than recent quarters suggest, which could expose the business to higher cyclicality and make the high P/E multiple harder to justify.
The most relevant update is management’s lift to 2026 guidance and the fresh 2027 revenue view. Expected fourth quarter 2026 revenue of US$2,740 million to US$2,760 million, versus a prior baseline of US$2,570 million, ties directly into what matters most for you as an investor: capacity utilization and mix.
That outlook leans on catalysts already in play, such as record aircraft backlogs, strong industrial gas turbine demand linked to power needs, and a higher contribution from aftermarket spares that reached roughly 22% of sales in the first half of 2026. The key watchpoint now is whether Howmet Aerospace can continue converting that demand into durable margins while managing a high level of debt and heavier capital spending.
Howmet Aerospace’s analyst narrative points to 2029 revenue of US$13.9b and earnings of US$3.4b. This view is anchored on an assumed 12.7% yearly change in revenue and an earnings increase of about US$1.3b from the US$2.1b reported today by that forecast year.
Uncover why Howmet Aerospace's fair value indicates a 53% potential upside to its current price, which could narrow quickly.
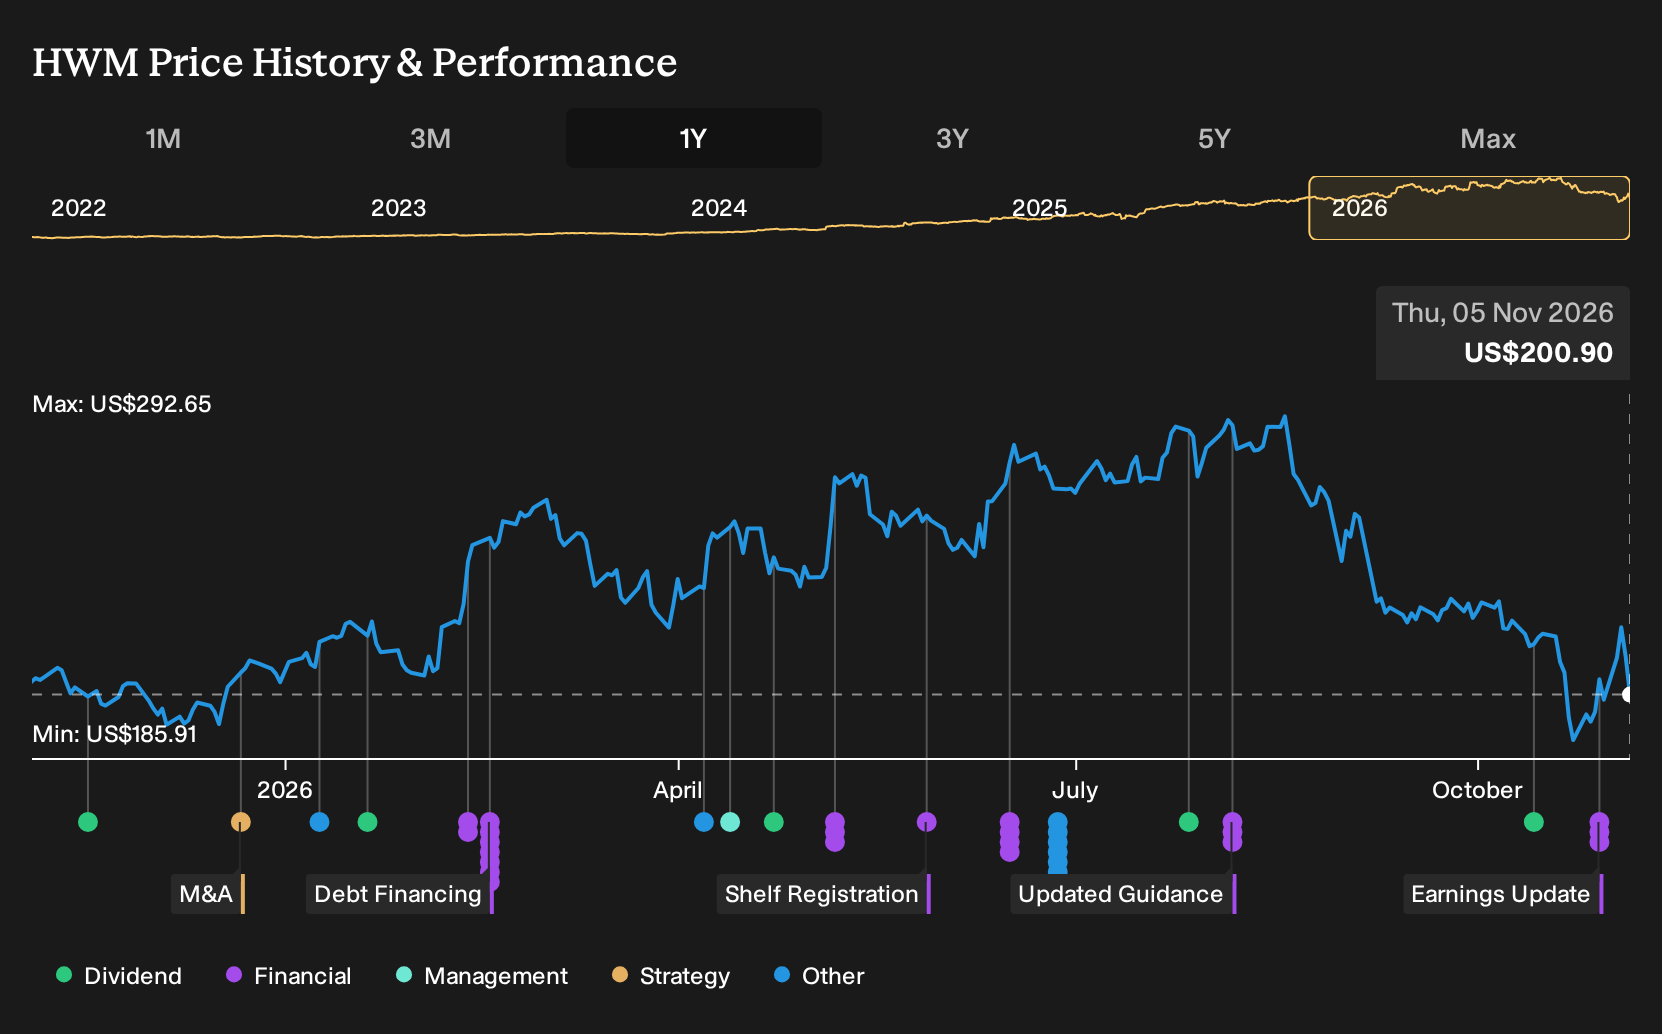
Exploring Other Perspectives
One bullish twist on Howmet Aerospace focuses on aftermarket spares as the real swing factor. The most optimistic analysts were already pencilling in roughly 17% annual revenue growth and earnings of about US$3.9b by 2029 before this guidance update. You can treat this quarter’s stronger figures as a fresh data point that may reshape those pre news views, so it is worth comparing a few different scenarios before deciding what feels reasonable to you.
Explore 5 other Howmet Aerospace fair value estimates, including one that suggests there could be as much as 87% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Howmet Aerospace research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Howmet Aerospace. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Howmet Aerospace's overall financial health at a glance.
Looking For More Investment Ideas Beyond Howmet Aerospace?
If Howmet Aerospace sharpened your thinking on capacity, cash flow, and risk, use that same lens on a wider watchlist. The Simply Wall St Screener can help you line up other stocks against the factors that matter most to you.
- If you want potential upside with a margin of safety, start by scanning a 42 high quality undervalued stocks that pair stronger fundamentals with prices that still look restrained.
- For a focus on resilience, filter for companies with sturdy finances using our list of solid balance sheet and fundamentals (24 results) to see which businesses carry less balance sheet stress.
- If income is your priority, then put cash returns front and centre by reviewing a 6 dividend fortresses and see which stocks currently offer higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com