
How Raised Earnings Estimates At BancFirst (BANF) Has Changed Its Investment Story
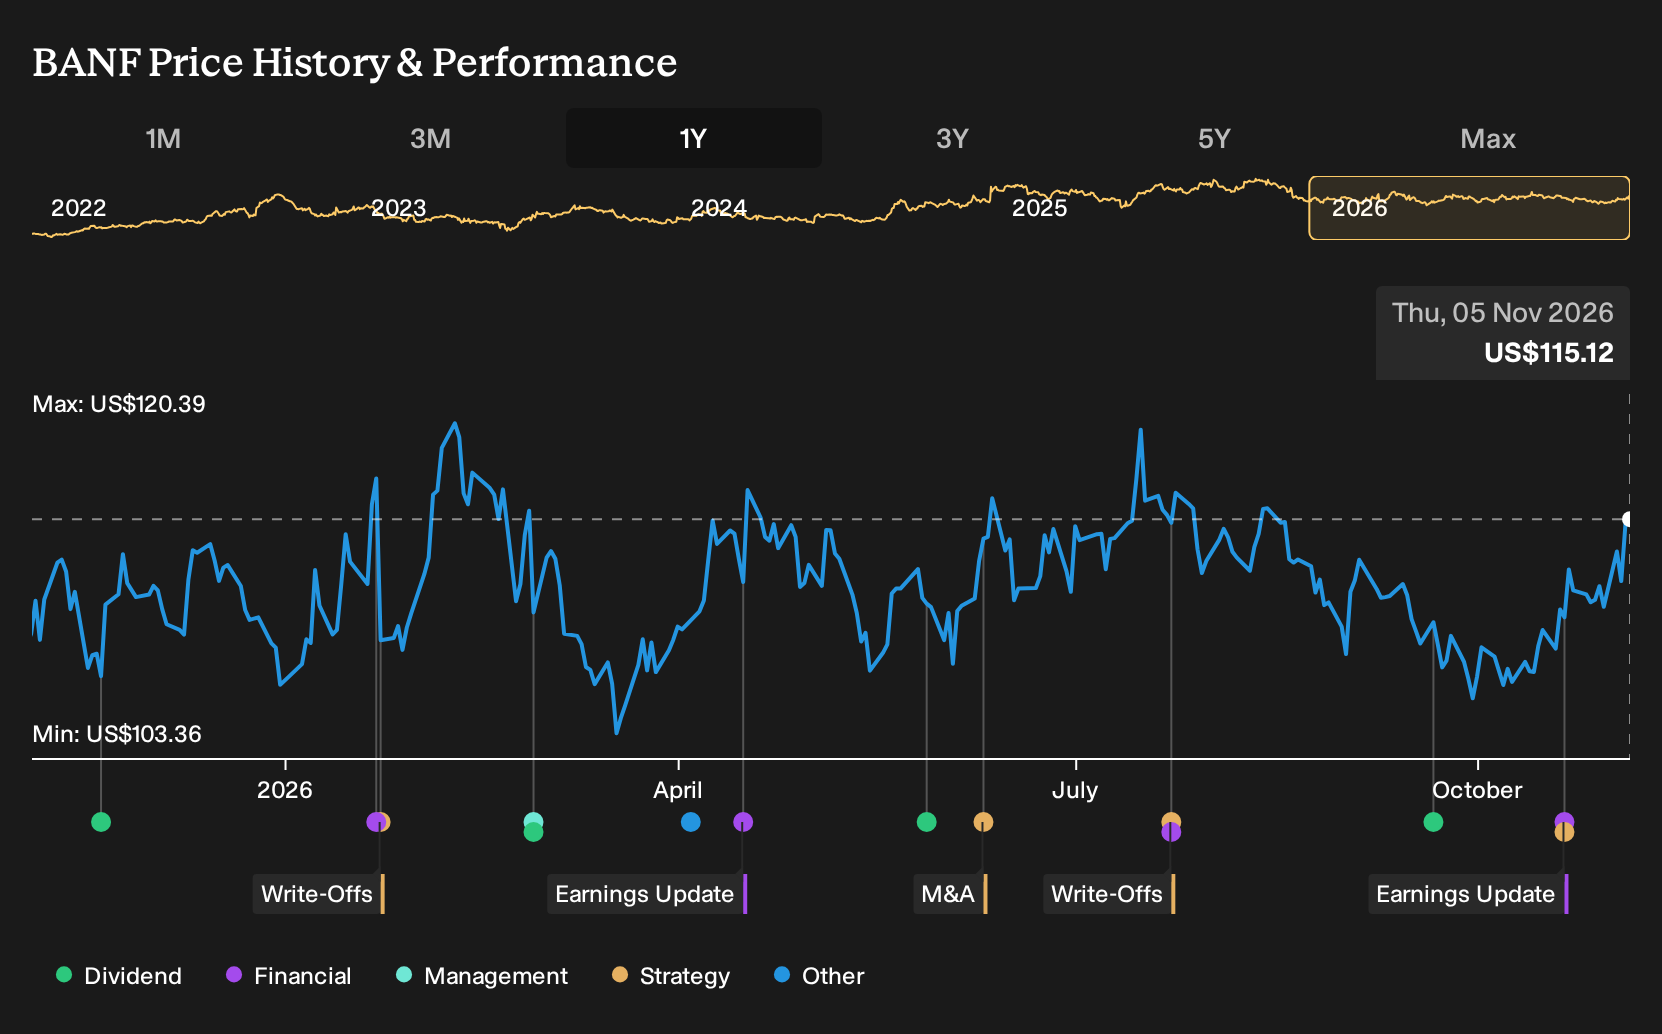
- BancFirst is currently rated Zacks Rank #2, with analysts lifting full year earnings estimates in recent months and the bank posting an 8.6% year to date return compared with 3.7% for the broader Finance sector.
- The 1% upward move in the Zacks Consensus Estimate for BancFirst’s full year earnings in the past quarter points to analysts revisiting assumptions around its mix of interest and non interest income, as well as how efficiently recent Tulsa market acquisitions might be contributing to earnings power.
- We will look at how BancFirst's improving earnings estimates feed into the existing investment narrative around profitability and acquisitions.
Compare how BancFirst’s setup stacks against other regionals by scanning a curated group of list of solid balance sheet and fundamentals (24 results) that may be handling earnings expectations with similar discipline.
BancFirst Investment Narrative Recap
An investor in BancFirst has to be comfortable with a relatively steady, regional banking model that leans on Oklahoma markets, a mix of interest and non interest income, and disciplined capital levels rather than rapid expansion. The recent uptick in earnings expectations highlights the same core bet: Can the Tulsa acquisitions, fee businesses and balance sheet strength offset only moderate expected revenue growth?
The near term swing factor is whether integration of the Tulsa deals and cost control can keep net margins firm even as growth expectations are described as mediocre. The biggest risk remains that efficiency drifts higher, revenue momentum stays modest and the market questions BancFirst’s premium P/E and price to tangible book multiples.
With no fresh corporate announcements tied directly to this earnings estimate move, the most relevant context is BancFirst’s ongoing Tulsa market consolidation through the completed American Bank of Oklahoma integration and the planned Spirit BankCorp acquisition. Those deals increase the branch footprint, loans and deposits in a key metro, which is exactly where investors will be watching for execution.
The logic is straightforward for you as a shareholder: if those acquired assets are used productively, they can support higher earnings even if system wide growth is not fast. If integration is slow, or costs tied to those branches run hotter than expected, then efficiency could worsen and amplify the risk that already elevated valuation multiples come under pressure.
Forecast earnings path for BancFirst
BancFirst's analyst narrative centers on a measured growth outlook that still assumes the Tulsa acquisitions can be absorbed without eroding the bank’s return profile too sharply. Consensus models bake in 7.0% yearly revenue growth for the next three years and a modest squeeze in profit margins from 35.3% today to 32.8% by year three. This effectively assumes some pressure on efficiency as the footprint expands.
On the income line, the projections move from current earnings of US$251.8 million to a forecast of US$286.7 million by 2029. That is an increase of about US$34.9 million in total profit, paired with expected earnings per share of US$8.21 once share count growth of roughly 0.79% a year is factored in.
BancFirst's narrative projects US$874.9 million revenue and US$286.7 million earnings by 2029. This requires 7.0% yearly revenue growth and an earnings increase of about US$34.9 million from US$251.8 million today.
Uncover why BancFirst's fair value suggests a potential upside of 8% from its current price before the market adjusts to close that gap.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between about US$122.33 and US$124.33, which shows how closely some retail investors are thinking about BancFirst today. Your own view may differ, especially if you focus more on risks around efficiency slipping or on Tulsa acquisition execution as a potential earnings catalyst.
Explore another BancFirst fair value estimate, including one that suggests up to 8% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BancFirst research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BancFirst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BancFirst's overall financial health at a glance.
Looking for more BancFirst sized investment ideas?
If the BancFirst story has sharpened your thinking around quality, valuation and execution risk, you can use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors focused on financial resilience, start by reviewing a list of solid balance sheet and fundamentals (24 results) that may better align with your comfort level on debt and liquidity.
- If your priority is finding mispriced quality, spend time on a curated 21 high quality undiscovered gems that might not yet be heavily followed.
- Income seekers can zero in on stability and payouts by working through a targeted 6 dividend fortresses that fit your yield and balance sheet preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com