
Ondas Stock Has The Bull Case Changed After Contract Wins
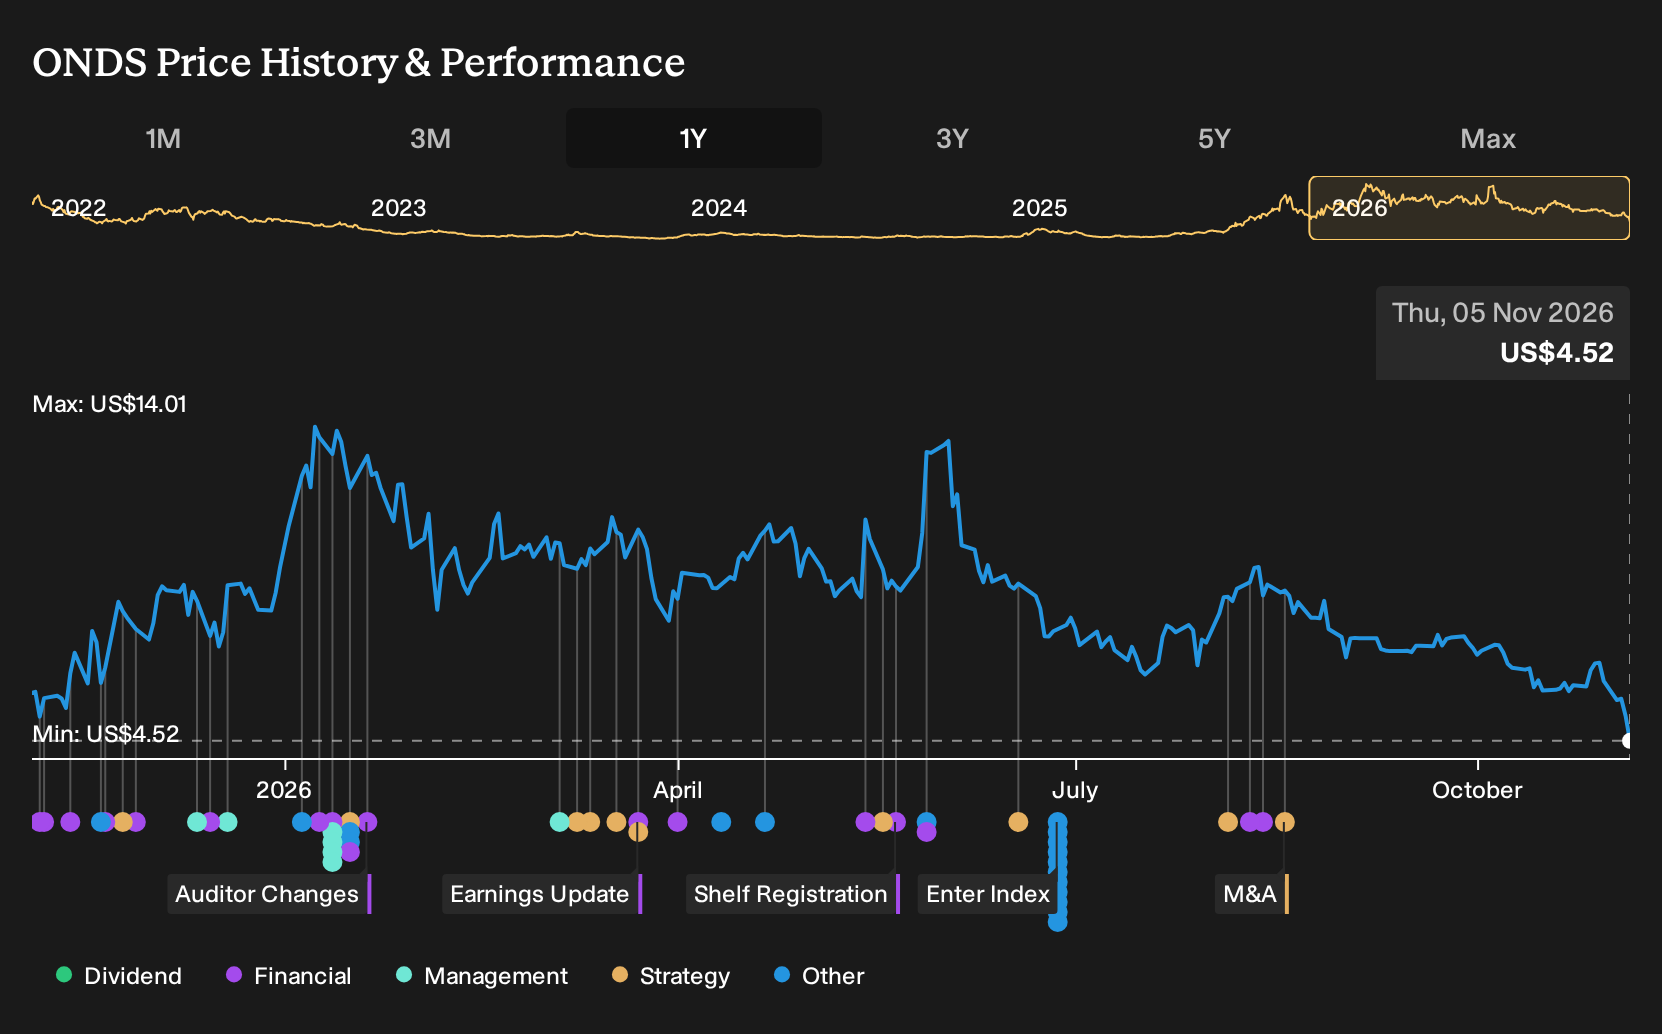
- Ondas has recently secured multi million dollar government contracts in Europe and Asia for its Counter UAS portfolio and moved to expand ULTRA ISR aircraft production in the U.S. through a planned acquisition of airframe supplier Stemme GmbH.
- The combination of international defense orders, a larger ULTRA production plan and onshoring of key manufacturing points to heavier execution demands on Ondas’ cost base, supply chain and program delivery over the next few years.
- We will now look at how Ondas’ investment narrative could be affected by its Stemme acquisition and stepped up ULTRA production.
Ondas Investment Narrative Recap
To own Ondas, you need to believe the company can turn a large backlog and multi year pipeline in ISR, precision strike and Counter UAS into dependable revenue while tightening a heavy cost base. Recent government contracts and ULTRA demand shine a light on that thesis, because they increase the operational load on an organisation still working toward profitability.
The key near term catalyst remains Ondas’ ability to convert signed orders into delivered systems and cash, without cost overruns eroding margins. The biggest risk is that elevated operating expenses, supply chain constraints and ambitious guidance collide, leaving losses wider for longer. The latest contract wins and ULTRA ramp raise the stakes rather than changing that equation.
The planned acquisition of Stemme GmbH, ULTRA’s airframe supplier, is the announcement that matters most for this Counter UAS and ISR story. Ondas is not just winning more work. It is also pulling a critical piece of the ULTRA manufacturing process in house in the U.S., which directly touches the execution question investors care about.
Bringing Stemme into Ondas could tighten control over schedules, costs and design changes on the long endurance ISR line, which is central to the multi year revenue outlook. It also concentrates risk. If integration stumbles, or if new U.S. production targets stretch the vendor ecosystem too far, the same move that supports the growth catalyst can pressure margins and cash flow.
Ondas' current analyst narrative points to revenues of US$1.6b and earnings of US$31.0 million by 2029, off a base of US$85.8 million of earnings today. That profile assumes revenue growing at 110.2% per year and an earnings decrease of US$54.8 million from current earnings to reach the 2029 consensus figure.
Discover how Ondas' fair value indicates a 318% potential upside to its current price. This opportunity may not last much longer.
Exploring Other Perspectives
You also have a very different read if you worry about Ondas’ funding needs. The most cautious analysts were assuming roughly US$1.4b of 2029 revenue and about US$155.9 million of earnings even before this Stemme deal and ULTRA push. That gap shows how far opinions stretch and why exploring multiple scenarios can help you stress test your own view.
Explore 8 other Ondas fair value estimates, including one that suggests it could be worth just $7.89!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ondas research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ondas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ondas' overall financial health at a glance.
Looking for more Ondas investment ideas?
If you want to pressure test your view on Ondas and broaden your watchlist, the Simply Wall St Screener can help you line up similar opportunities with different risk and return profiles.
- For investors who care about balance sheet strength and financial resilience, scan a list of solid balance sheet and fundamentals (24 results) to compare alongside Ondas.
- If you want income on top of potential capital gains, sift through a focused set of 6 dividend fortresses and see how their cash returns stack up.
- When you are hunting for future leaders that are not yet widely followed, shortlist a group of 21 high quality undiscovered gems and build your own bench of ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com