
SL Green Realty (SLG) Stock May Be A Bargain On Cash Flow
SL Green Realty has put up a sizeable run in recent years, which naturally raises a simple question for you as a shareholder or potential buyer. Is the current share price at around US$51.55 aligned with the cash flows the business is expected to produce over time, or has sentiment moved ahead of the underlying numbers?
- The stock has returned 96.8% over the past 3 years, so a lot of future cash flow is already being reflected in the price and that makes the quality and durability of those cash flows critical.
- As a real estate owner and operator, SL Green Realty relies heavily on rental income and asset recycling, which can shape both the timing and stability of the cash flows that feed into any intrinsic value estimate.
- What if you looked at SL Green Realty through its sales instead? See why SL Green Realty's 3.4x P/S tells a different valuation story.
The issue now is whether those cash flows, when discounted through a Discounted Cash Flow (DCF) lens, can fully support where SL Green Realty shares are trading today.
If you are weighing SL Green Realty against other opportunities that are also framed around cash generation, it can help to compare its setup with 42 high quality undervalued stocks.
Is SL Green Realty a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash SL Green Realty can return to shareholders over time. Latest twelve month free cash flow on this adjusted funds from operations basis is about $275.5 million, so you are looking at a business already generating meaningful cash today rather than a distant promise of profitability.
Analyst and model estimates used in the DCF point to growing free cash flow in future years, with projections extending into the mid 2030s. That profile, when discounted back, produces an estimated intrinsic worth that sits substantially above the current share price of $51.55. This implies the market is placing a cautious value on those future rents and asset sales relative to the cash they are expected to produce. Find out what SL Green Realty could be worth using our Discounted Cash Flow (DCF) estimate.
The SL Green Realty Narrative: What Would Justify Today's Price?
Narratives for SL Green Realty pick up where the DCF question leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price. They sit on Simply Wall St’s Community page. Each scenario links a fair value estimate to a clear storyline about SL Green Realty's possible catalysts and risks so you can track over time which version is closest to reality.
Community views on SL Green Realty split between investors who see scarcity value in Midtown and those who worry cash coverage still looks thin.
Bull case: 7% undervalued
"Broad-based Manhattan leasing from finance, tech, AI and other tenants, with 2026 deals already lifting leased occupancy to 95% and rent mark-to-market around 15% to 16%..."
Discover why this Narrative puts SL Green Realty at 7% undervalued.
Bear case: 14% overvalued
"Although SL Green Realty is reporting higher leased and economic occupancy with strong cash mark to market on recent leases, heavy leasing capital outlays planned through 2027 defer cash realization from net operating income growth..."
Explore why this Narrative puts SL Green Realty at 14% overvalued.
One More Piece Of The SL Green Realty Puzzle
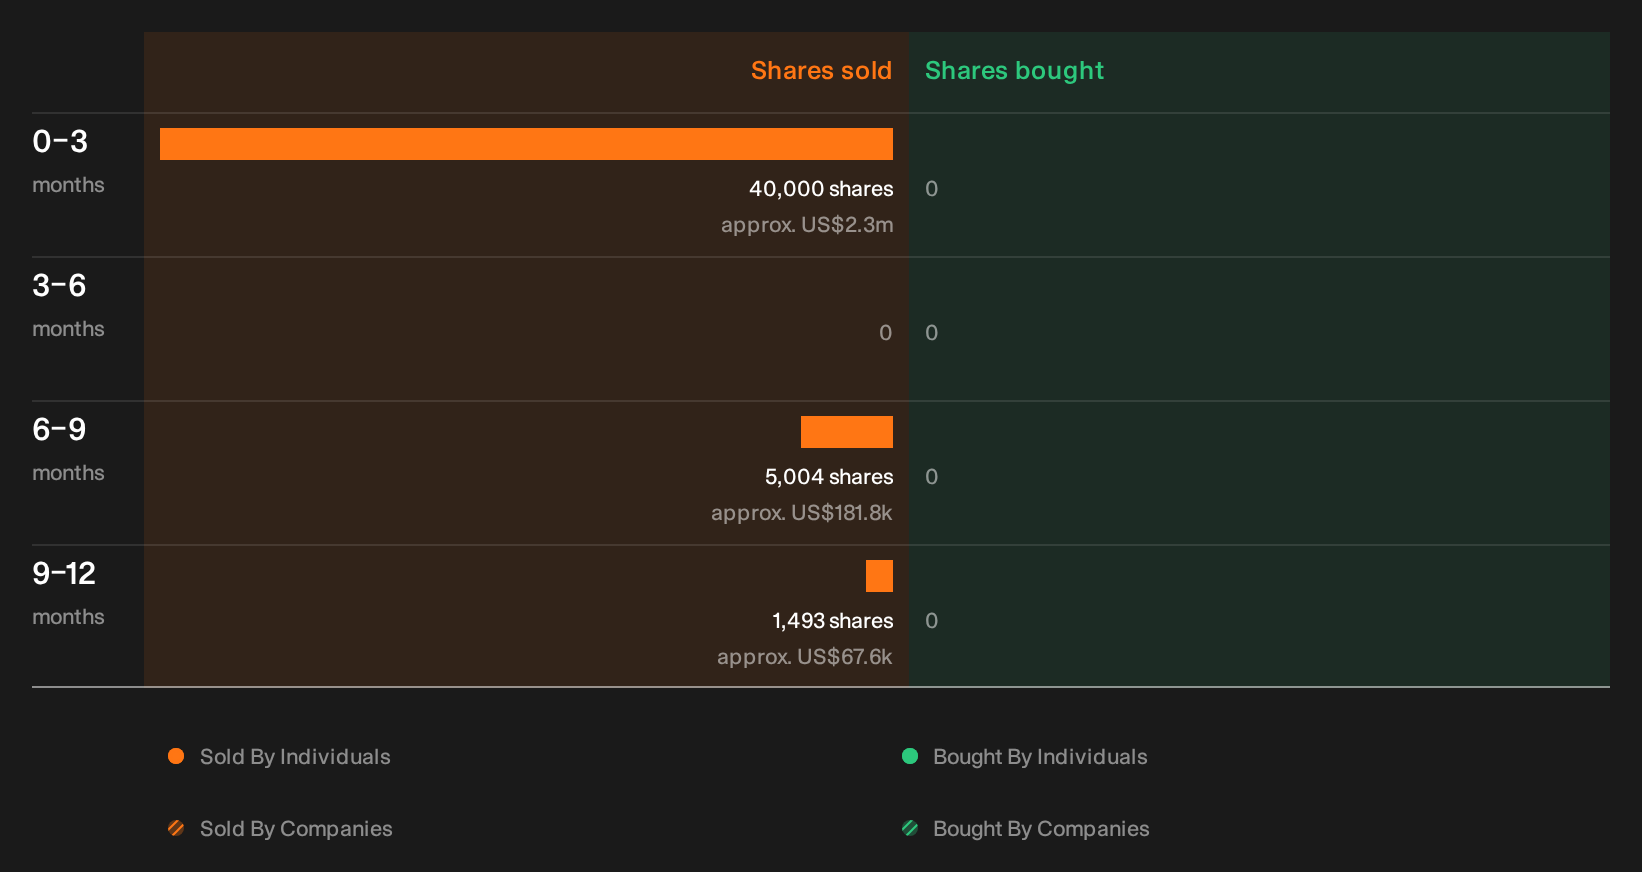
There is one gap that matters for anyone tracking SL Green Realty. Recent trades by people inside the business have been flagged by our checks, and the who, how much and why are still for you to unpack. See the recent insider selling flagged for SL Green Realty.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com