
Brookfield (TSX:BN) After Its UK AI Data Center Bet Looks Undervalued To Bulls
Brookfield’s AI data center bet in the UK
Brookfield (TSX:BN) has drawn fresh attention after outlining plans for a large AI focused data center complex in England, with potential investment topping £20b and an initial 100 megawatt phase targeted by early 2028.
Brookfield’s recent AI data center announcement comes amid a mixed price picture, with the share price falling 2.79% in the last session but gaining 10.42% over 30 days, while the year-to-date share price return remains down 8.72% and the 3-year total shareholder return is a little over 2x.
Scan other infrastructure and AI related plays by reviewing our curated list of 53 AI infrastructure stocks that could benefit from similar data and compute demand trends.
Short term traders may focus on Brookfield’s recent bounce, while long term investors might see the AI data center plan as a fresh anchor. Is today’s price already baking that in, or not yet?
Most Popular Narrative: 29% Undervalued
According to the most followed Brookfield narrative, the shares trade below an estimated fair value of CA$82, compared to the recent CA$58.50 close. That gap reflects a detailed cash earnings framework rather than a simple headline P/E view.
BN lets us own Brookfield Asset Management, a capital-light fee franchise we regard as a classic Pershing business, at a holding-company discount. Carried interest, Wealth Solutions and the operating assets add growth on top.
The return comes from compounding earnings; any narrowing of the discount is the accelerant, not the engine.
See why 10 investors see Brookfield as 29% undervalued.
Result: Fair Value of CA$82 (UNDERVALUED)
Still, Brookfield’s Wealth Solutions exposure to related-party assets and the gap between accrued and realised carry are two fault lines that could challenge this thesis.
Find out about the key risks to this Brookfield narrative.
Another View on Brookfield’s valuation
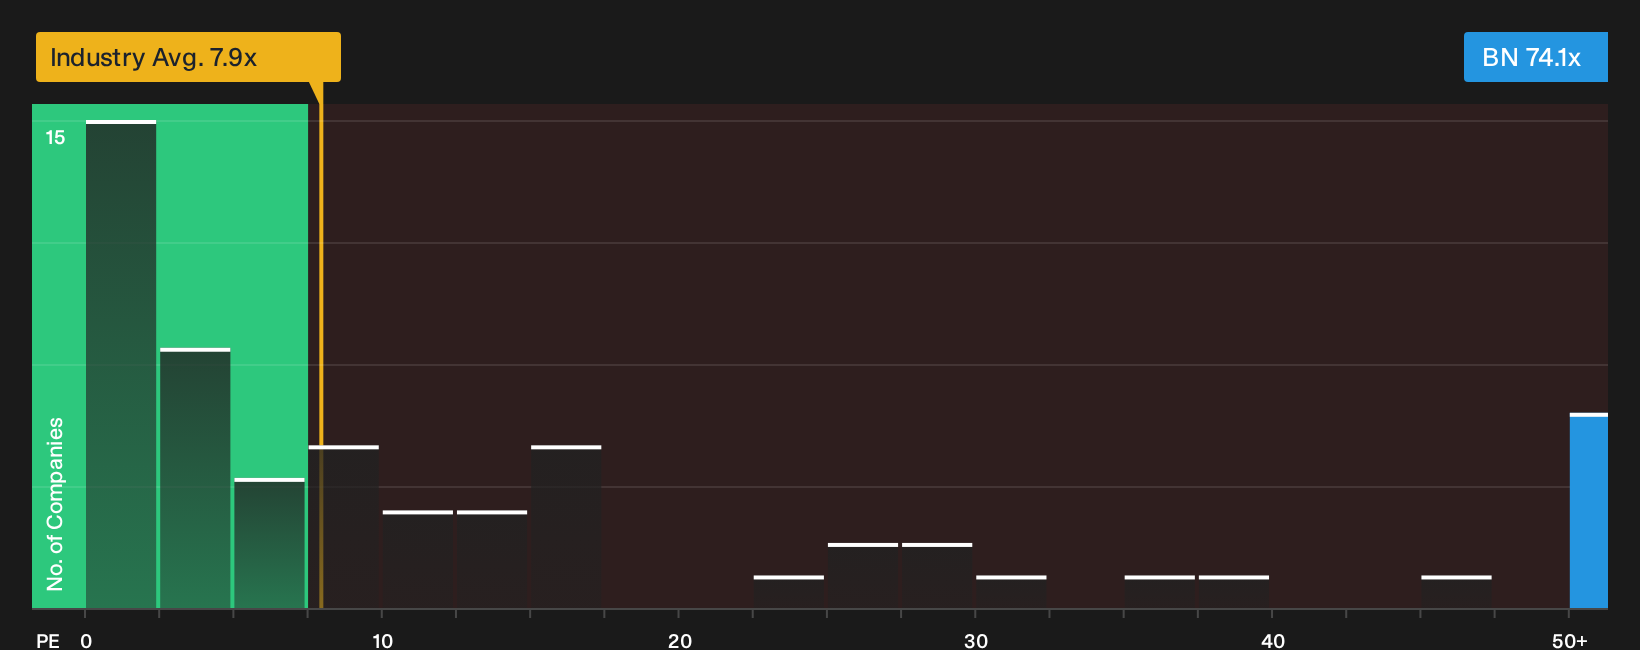
The first lens on Brookfield leaned on cash earnings and a CA$82 fair value. A very different picture appears when you look at the plain P/E. On reported numbers, BN trades on a 74.1x P/E, while the Canadian Capital Markets group sits around 7.9x and close peers near 17x.
That kind of gap points to potential valuation risk if earnings ever disappoint or normalise closer to sector levels, since a high multiple leaves less room for error than a single cash flow model might suggest. Which signal do you put more weight on: the earnings yield story or the rich headline multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Brookfield feels familiar, that is the point; investors are weighing real upside against real risk. Act fast on your curiosity and pressure test the full picture by reviewing the 1 key reward and 2 important warning signs
Looking for more Brookfield sized investment ideas?
You have already done the work on Brookfield. Do not stop there when other opportunities could suit your goals and risk appetite even better.
- Target future upside potential by scanning a curated mix of quality opportunities through the 7 high quality undiscovered gems.
- Focus on resilience under pressure by filtering companies that pass balance sheet and fundamentals checks with the list of solid balance sheet and fundamentals (5 results).
- Stack the odds toward attractive entry points by reviewing a data backed shortlist of potential value ideas using the 6 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com