
Canadian Imperial Bank Of Commerce (TSX:CM) Dropped, So What Is Driving Attention Now?
Canadian Imperial Bank of Commerce (TSX:CM) has been active in the bond market, issuing several new senior unsecured fixed rate notes with maturities stretching from 2028 to 2039. That refinancing activity gives equity investors fresh context.
Recent trading has been choppy for Canadian Imperial Bank of Commerce, with the share price falling 3.15% over the last session and easing 2.56% over the past week. This comes even though the year to date share price return of 28.32% sits alongside a 1 year total shareholder return of 40.58%, and a multi year total shareholder return that is very large at roughly 2.5x over 3 years and 1.7x over 5 years. This points to momentum that has cooled in the short term, while the bond issuance, core banking awards and upcoming results keep investors focused on how much risk is now being priced into that longer run performance.
Spot opportunities across the banking sector by comparing Canadian Imperial Bank of Commerce with a curated 8 resilient stocks with low risk scores list that has been filtered for resilience and balance sheet strength.Bulls see Canadian Imperial Bank of Commerce pricing in too much fear after the recent pullback. Bears argue that rich past returns already reflect the good news. Which side does the current valuation lean toward?
Most Popular Narrative: 5% Undervalued
Canadian Imperial Bank of Commerce last closed at CA$161.97, compared with a narrative fair value estimate of about CA$170.50 that points to a modest gap between price and expectations. That small discount puts the spotlight on what really has to go right inside the business for that view to hold.
Continued growth in Canadian Imperial Bank of Commerce mass affluent and wealth franchises, supported by 20% to 24% AUA and AUM growth and strong mutual fund net sales, can keep lifting fee based revenue and smooth earnings compared with more rate sensitive lines.
Scaling of Canadian Imperial Bank of Commerce AI tools such as AdvisorAssist, which has already delivered 3 million hours of productivity savings and cut adviser administrative time by up to 50%, can further improve operating leverage and support net margin resilience.
See why 122 investors see Canadian Imperial Bank of Commerce as 5% undervalued.
Result: Fair Value of CA$170.50 (UNDERVALUED)
Still, the narrative around Canadian Imperial Bank of Commerce can change quickly if Canadian mortgage delinquencies worsen or capital markets earnings soften relative to current analyst assumptions.
Find out about the key risks to this Canadian Imperial Bank of Commerce narrative.
Another View on Canadian Imperial Bank of Commerce Valuation
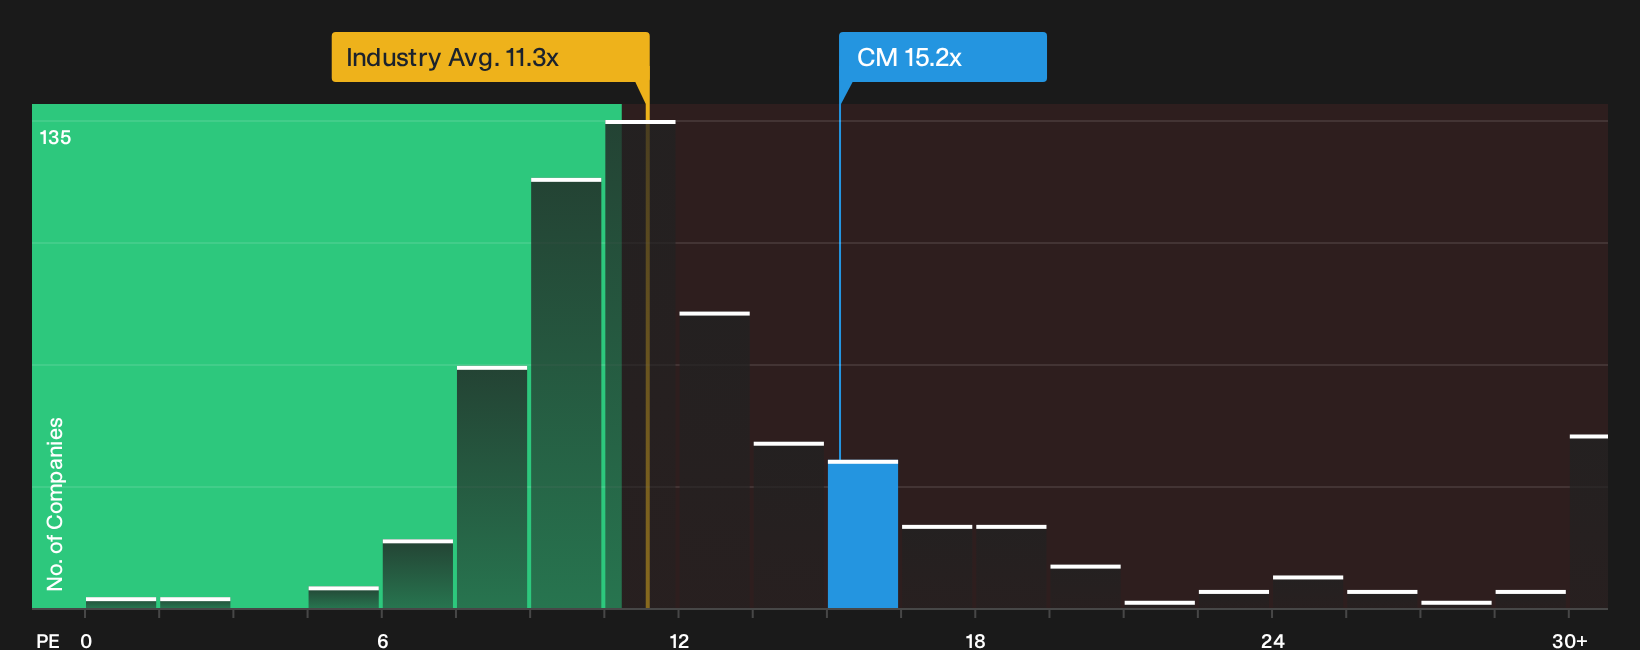
The first story presents Canadian Imperial Bank of Commerce as modestly undervalued at CA$161.97 versus a CA$170.50 narrative fair value. A different lens tells a cooler story. On a P/E of 15.2x, the stock trades richer than the North American banks group at 11.3x, yet below its own fair ratio of 18.4x. That combination of a premium to peers but a discount to its fair ratio suggests both room for optimism and the risk that expectations are already demanding a lot. Which side of that trade off appears more realistic to you?
To see how this pricing gap could close in practice, including how earnings, sector moves and sentiment might push the multiple toward or away from that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Confident that the crowd has this story right, or think Canadian Imperial Bank of Commerce is being misread after the recent swings? Take a few minutes to test the assumptions, stress test the upside and downside in your own model, then weigh that against the 4 key rewards.
Looking for more investment ideas beyond Canadian Imperial Bank of Commerce?
Do not stop your research with Canadian Imperial Bank of Commerce. Broaden your watchlist now so you are not relying on just one opportunity.
- Target resilience first and filter for balance sheet strength with a focused list of solid balance sheet and fundamentals (5 results) that helps you stress test quality under tougher conditions.
- Hunt for potential mispricing by scanning a curated 6 high quality undervalued stocks that narrows the field to companies with stronger numbers than their current tags suggest.
- Get ahead of the crowd by checking a purpose built 7 high quality undiscovered gems that highlights financially sound businesses still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com