
Weis Markets (WMK) Faces A 1% Fair Value Gap After Strong Earnings
Weis Markets earnings spark fresh attention
Weis Markets (WMK) just reported third quarter and nine month results showing higher sales, revenue, and net income than the same periods last year, putting the supermarket operator back in focus for income minded and defensive investors.
Weis Markets' share price has climbed 23.55% year to date, including a 9.10% 1 month share price return and 5.84% over the past week, suggesting momentum has picked up recently even as the latest session saw a small 0.51% pullback to US$79.21. The 1 year total shareholder return of 24.64% underlines how the stock has been quietly rewarding patient holders over a longer stretch.
Scan beyond Weis Markets and source a short list of income friendly defensives with steady financial profiles using our list of solid balance sheet and fundamentals (24 results) as a starting point.
After a quick 24.64% total return over the past year and a stronger earnings print, Weis Markets now forces a choice. Do you lean into the move, or wait for the valuation section to reveal a better entry point?
Price-to-Earnings of 18.7x: Is it justified?
Weis Markets trades on a P/E of 18.7x, which places a richer tag on its $79.21 share price compared with both its peers and the broader Consumer Retailing group.
The P/E ratio compares what investors pay today for each dollar of earnings. For a supermarket chain like Weis Markets, that yardstick often reflects how dependable the market thinks its cash generation and profit resilience are, rather than chasing rapid expansion.
WMK is described as expensive against a peer average P/E of 12.9x and a US Consumer Retailing industry average of 18.6x. That signals investors are currently willing to ascribe a premium price to each dollar of earnings compared with closer peers, while only a touch above the wider sector. The gap can indicate the market is pricing in steadier profit quality, income appeal, or simply crowding into a defensive retailer after a solid run.
The comparison against both peer group and industry is unusually tight. The language of "expensive" versus similar Consumer Retailing stocks suggests the market is leaning toward a full valuation for Weis Markets on current earnings rather than leaving obvious room for mispricing.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 18.7x (OVERVALUED)
Still, Weis Markets faces clear swing factors, including pressure on grocery pricing and any slowdown in customer traffic across its regional footprint.
Find out about the key risks to this Weis Markets narrative.
Another view on Weis Markets valuation
The P/E label says Weis Markets looks expensive, yet the SWS DCF model sketches a softer picture. With the shares at $79.21 and the future cash flow value at $79.65, the stock screens roughly 0.6% below that estimate, which reads more like fair value than froth.
When one yardstick says pricey and another points to a near match on cash flows, it leaves a simple question for you: Which signal do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
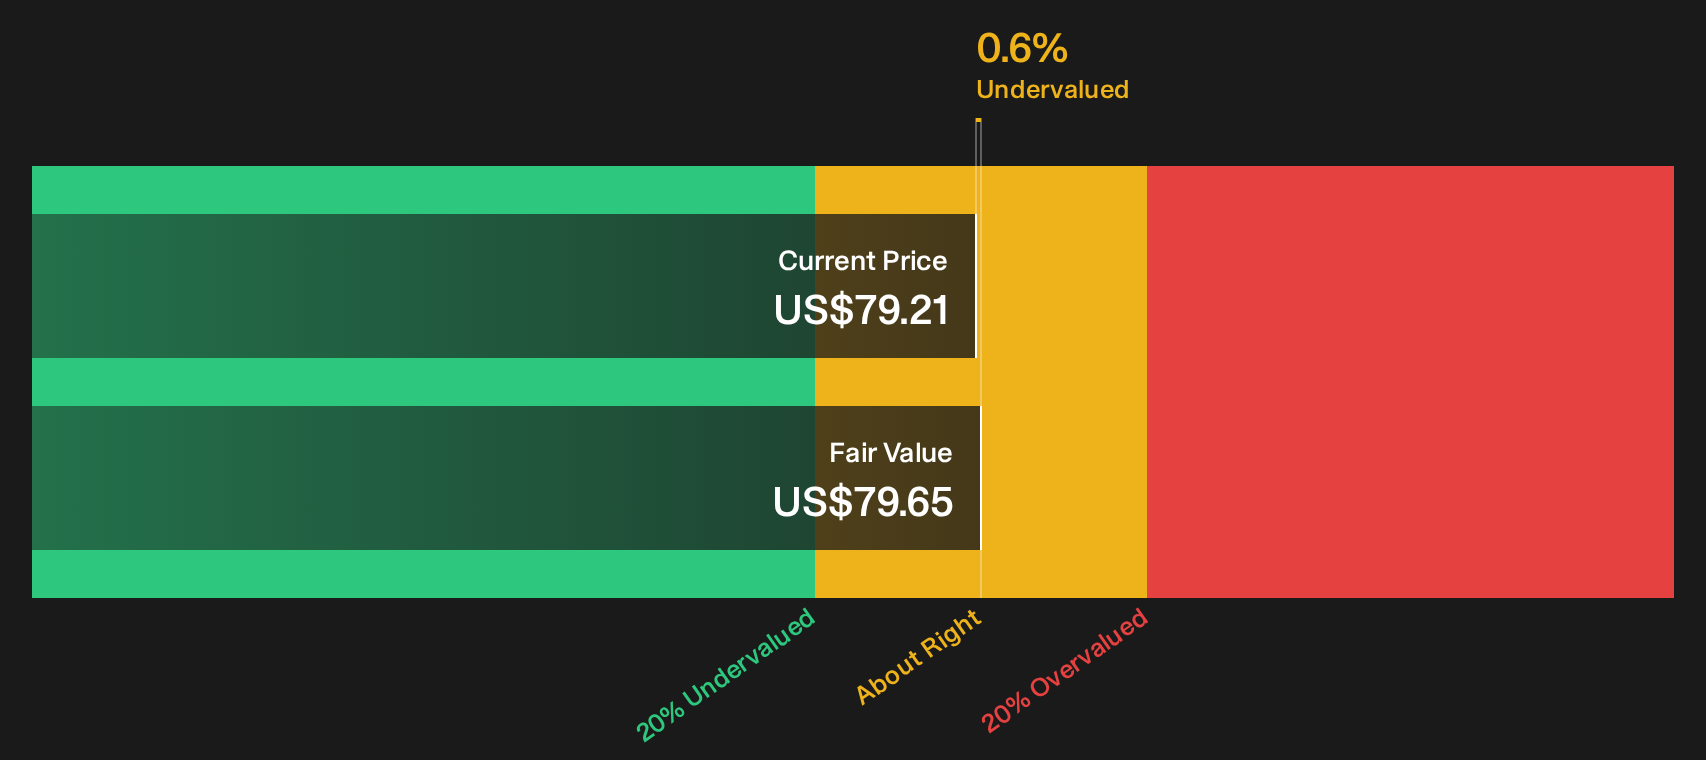
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Weis Markets for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Weis Markets so far. If you want your view to move faster than the headlines, consider both the upside and the red flags in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Weis Markets?
If Weis Markets has your attention, do not stop here. The screener tools can surface other opportunities that fit your income, value, or risk profile.
- Target reliable income streams by running through a curated set of stocks that pay out meaningful cash using the 6 dividend fortresses.
- Hunt for quality at a measured price and let the 42 high quality undervalued stocks filter for companies that pair solid fundamentals with potentially attractive entry points.
- Prioritize resilience first and use the 32 resilient stocks with low risk scores to focus on businesses with sturdier balance sheets and lower risk scores before committing fresh capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com