
Is Canberra Lighting Expansion Altering The Investment Case For Itron (ITRI)?
- The City and Environment Directorate has extended its collaboration with Omexom and Itron after seven years, planning to upgrade 16,000 more Canberra streetlights using Itron’s smart lighting controllers, Gen5 network and CityEdge platform.
- This Canberra extension underscores Itron’s role in long term smart city programs, where remote monitoring, adaptive lighting and data driven asset management support customers’ safety, efficiency and sustainability goals.
- Next, the focus shifts to how Itron’s investment narrative intersects with this expanded Canberra smart lighting rollout and long term municipal demand.
Scan how Itron’s smart city work in Canberra fits alongside other grid and infrastructure plays by reviewing the 40 power grid technology and infrastructure stocks in one focused shortlist.
Itron Investment Narrative Recap
Itron appeals to investors who believe utilities and cities will keep investing in smart infrastructure and who are comfortable with project timing driving quarterly swings. The Canberra renewal fits that belief, but it is incremental. The bigger near term swing factor still looks like how quickly large grid and metering deployments already in the backlog move into active rollout.
The key risk remains that budget pressure or regulatory delays stretch those programs further, which can hold back revenue and keep earnings tied to deployment timing. Canberra shows execution strength in smart cities, yet it does not materially change that central risk reward trade off.
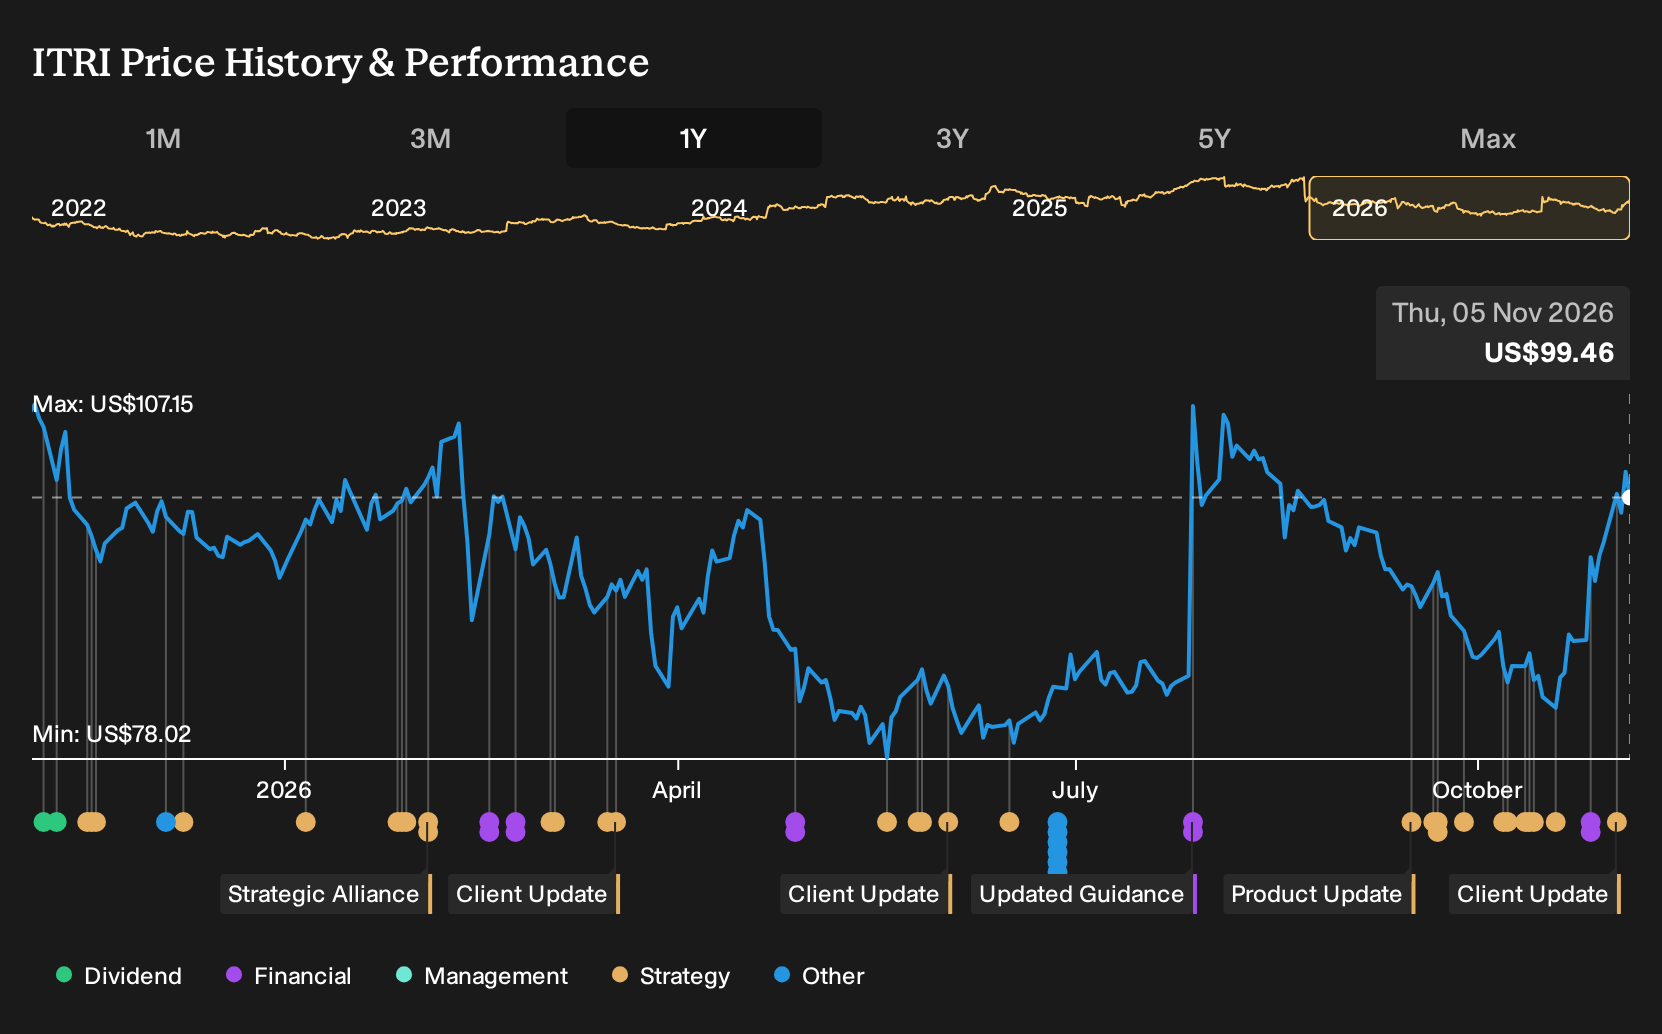
The earnings update for the quarter ended 30 September 2026 is the most relevant backdrop for this Canberra contract extension. Basic EPS from continuing operations was US$1.63 for the quarter compared with US$1.43 a year earlier, while basic EPS for the first nine months was US$4.03 compared with US$4.38 in the prior period.
Those figures sit alongside guidance that points to expected fourth quarter 2026 revenue between US$621 million and US$636 million and full year revenue of US$2.37b to US$2.385b. For a shareholder, the question is how consistently projects like Canberra convert into that guided revenue while managing the risk of further deferrals in larger networked programs.
Itron's narrative projects US$2.7b revenue and US$339.3 million earnings by 2029. This projection assumes 6.1% yearly revenue growth and an increase of about US$65 million in earnings from the current US$274.0 million level.
Uncover how Itron's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly US$71.5 to US$129.6 per share, so some retail investors see Itron as heavily discounted while others are far more cautious. When this is set against risks around delayed network projects and margin pressure, it results in a wide spread of expectations. Opinions clearly differ, so review several of these perspectives before deciding how Canberra’s contract extension and the broader smart grid backdrop might matter for you.
Explore 3 other Itron fair value estimates, including one that suggests as much as 28% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Itron research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Itron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Itron's overall financial health at a glance.
Looking For More Investment Ideas Beyond Itron?
Once you have a view on Itron, it can help to compare it with other opportunities that fit different risk, quality and income profiles. The Simply Wall St Screener is built for exactly that, giving you a fast way to filter by fundamentals and surface stocks that match what you want your portfolio to do next.
- If you want a starting point for quality at a reasonable price, scan a curated 42 high quality undervalued stocks that combine strong fundamentals with attractive valuations.
- For investors who care most about balance sheet strength and resilience, shortlist companies from a list of solid balance sheet and fundamentals (24 results) that can better withstand funding shocks and project delays.
- If you are hunting for opportunities the market may be overlooking, broaden your watchlist with a 21 high quality undiscovered gems that pair solid financial profiles with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com