
MetroCity Bankshares (MCBS) Could Be 55% Undervalued After Strong Q3 Earnings
MetroCity Bankshares (MCBS) just posted third quarter 2026 results that show higher net interest income and net income compared with the same period a year earlier, giving investors fresh data on the bank’s recent performance.
At a share price of $36.08, MetroCity Bankshares has delivered a 37.34% year to date share price return, while total shareholder return over the past year is 42.92%. This indicates momentum that has cooled in the very short term after the recent results but remains strong over multi year periods.
Compare MetroCity Bankshares' recent earnings strength with a hand picked group of resilient financials in the 32 resilient stocks with low risk scores, which screen for sturdier balance sheets and lower risk profiles.
After a sharp run and a recent wobble, MetroCity Bankshares now trades well below both analyst targets and some intrinsic value estimates. Does that gap still signal opportunity or has the share price already caught up?
Price-to-Earnings of 12x: Is it justified for MetroCity Bankshares?
MetroCity Bankshares trades on a P/E of 12x, which points to a richer valuation when set against several reference points, even though the last close sits at $36.08.
The P/E ratio compares the share price with earnings per share. For a regional bank like MetroCity Bankshares, that figure provides a quick indication of how much investors are willing to pay for each dollar of profit. This often reflects expectations around loan growth, fee income and credit costs.
In this case, the valuation leans toward a premium. The stock is described as expensive versus its estimated fair P/E of 10.5x, which is the level suggested by a fair value model. The current P/E of 12x also sits above the US Banks industry average of 11.3x and above a peer group average of 11.8x. This implies the market is paying more relative to both the broader sector and similar banks, even though the fair value analysis indicates a lower multiple level that the price could move toward.
Explore the SWS fair ratio for MetroCity Bankshares.
Result: Price-to-earnings of 12x (OVERVALUED)
Still, the MetroCity Bankshares story could be tested if credit quality weakens in its loan book or if funding costs rise faster than interest income.
Find out about the key risks to this MetroCity Bankshares narrative.
Another View: SWS DCF model points the other way
While the P/E of 12x paints MetroCity Bankshares as expensive, the SWS DCF model points to a different conclusion. On that framework, the stock trades at $36.08 against an estimated future cash flow value of $55.91, which frames the shares as undervalued. Which signal do you trust more for the long haul?
Look into how the SWS DCF model arrives at its fair value.
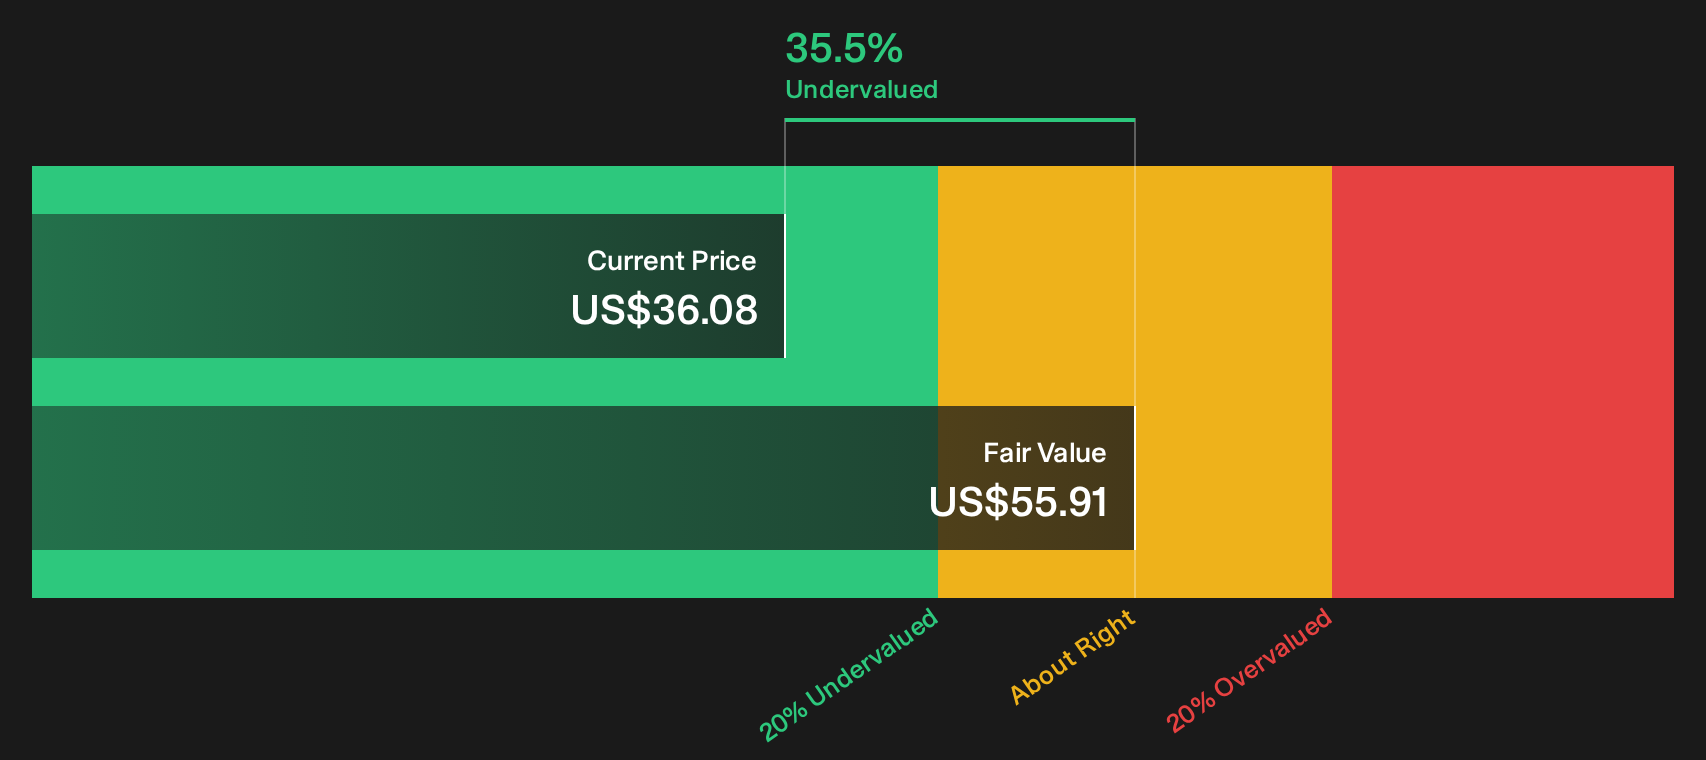
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MetroCity Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on MetroCity Bankshares valuation can spark debate, so act while the information is fresh and build your own view by weighing the 3 key rewards.
Looking for more MetroCity Bankshares sized investment ideas?
Do not stop with MetroCity Bankshares when the broader market is full of other opportunities that could fit your risk and return preferences.
- Target steadier potential outcomes by scanning a 32 resilient stocks with low risk scores that filters for companies with more resilient financial risk profiles.
- Hunt for price tags that look appealing relative to fundamentals by running through a 42 high quality undervalued stocks tailored to highlight mispriced businesses.
- Strengthen your income watchlist by reviewing a 6 dividend fortresses focused on companies offering higher yields with supportive balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com