
Learn Why The Bull Case For California Water Service Group Stock Could Change Following Strong Quarterly Earnings
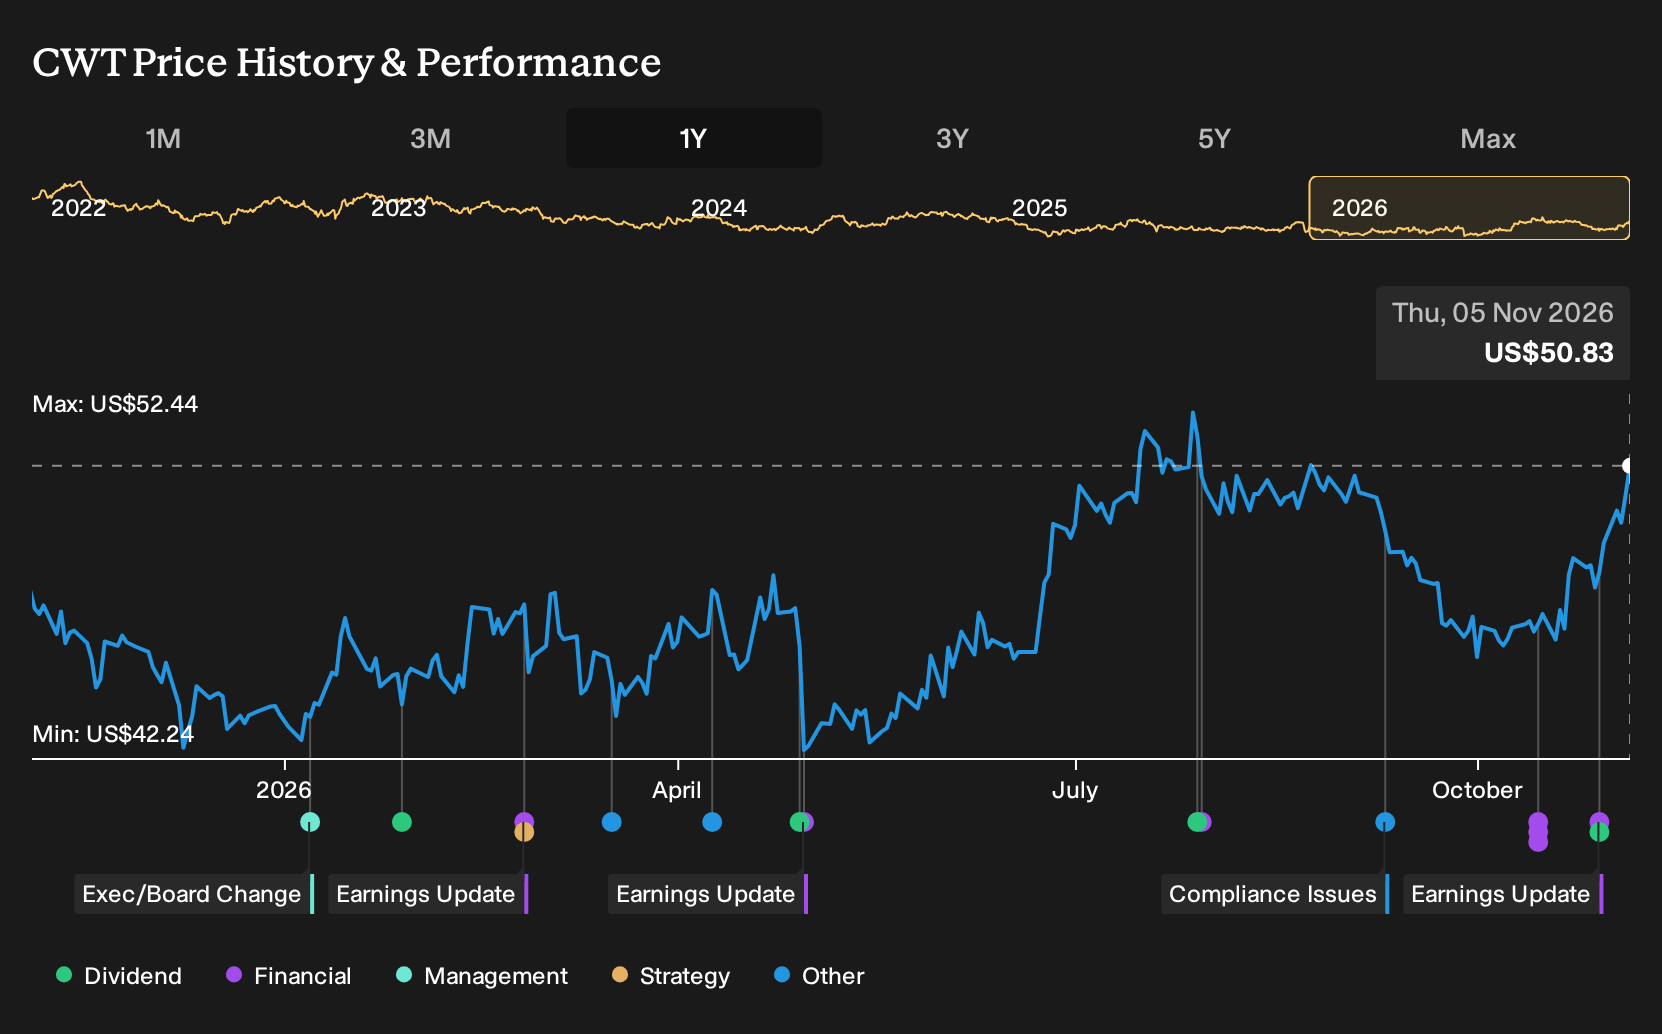
- California Water Service Group reported third quarter 2026 sales of US$332.17 million and net income of US$65.41 million, and confirmed its 327th consecutive quarterly dividend at US$0.335 per share, supporting an expected annual payout of US$1.34 per share for 2026.
- The combination of higher sales and earnings for both the quarter and year to date, together with a 59 year dividend increase streak, highlights how California Water Service Group is balancing capital intensive utility operations with consistent cash returns to shareholders.
- We will look at how California Water Service Group’s stronger quarterly earnings shape the existing investment narrative built around regulated expansion.
Scan beyond California Water Service Group and compare its long dividend record with hand picked income ideas in the 6 dividend fortresses.
California Water Service Group Investment Narrative Recap
To own California Water Service Group, you need to be comfortable with a regulated utility that leans heavily on long term capital projects and constructive rate decisions. The recent quarter showed higher sales and net income for both the three and nine month periods, which supports that investment case but does not fundamentally change it.
The short term swing factor still looks like how quickly regulators and new jurisdictions convert that capital spending and PFAS program into recoverable earnings and cash flow. The main risk remains pressure from depreciation, interest costs and taxes, which already weighed on earlier 2026 results and could do so again if recovery timings lag spending.
The most relevant update here is the third quarter 2026 earnings report, because it gives you a clearer view of how California Water Service Group is tracking against those capital intensive plans. Sales reached US$332.17 million for the quarter and US$855.34 million for the first nine months, with net income of US$65.41 million and US$125.91 million respectively.
That profitability, combined with diluted EPS from continuing operations of US$1.05 for the quarter and US$2.07 for the year to date, helps frame whether current earnings support the dividend stream and planned rate base expansion. It also sits alongside risks already flagged around debt coverage by operating cash flow and dividend coverage by free cash flow, which remain key items to monitor against any future catalysts.
California Water Service Group's narrative projects US$1.3b revenue and US$200.4 million earnings by 2029. This requires 6.9% yearly revenue growth and an earnings increase of about US$67 million from current earnings of US$133.2 million.
Uncover why California Water Service Group's fair value indicates a 6% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community brings three fair value views on California Water Service Group, ranging from US$41 to US$53.75 and distributed across ten price buckets. That spread sits alongside rising capital commitments, PFAS recovery efforts and multi state expansion, which could all influence how future earnings power and dividend resilience are evaluated. Investors clearly see this in very different ways, so it is worth comparing several of those viewpoints before deciding how the recent dividend affirmation and earnings numbers fit into your own framework.
Explore 2 other California Water Service Group fair value estimates, including one that suggests a potential 6% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your California Water Service Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for California Water Service Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate California Water Service Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond California Water Service Group?
Once you have a view on California Water Service Group, it can help to widen the lens and compare it with other companies that match your income, quality or risk profile using the Simply Wall St Screener.
- For investors who want income with staying power, compare California Water Service Group's record with a curated set of high yield payers in the 6 dividend fortresses.
- If valuation discipline is your priority, scan for companies that pair solid fundamentals with potentially attractive pricing using the 42 high quality undervalued stocks.
- To round out your watchlist with companies that combine resilience and lower risk scores, search through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com