
COMPASS Pathways Stock In Focus As FDA Filing Nears Completion
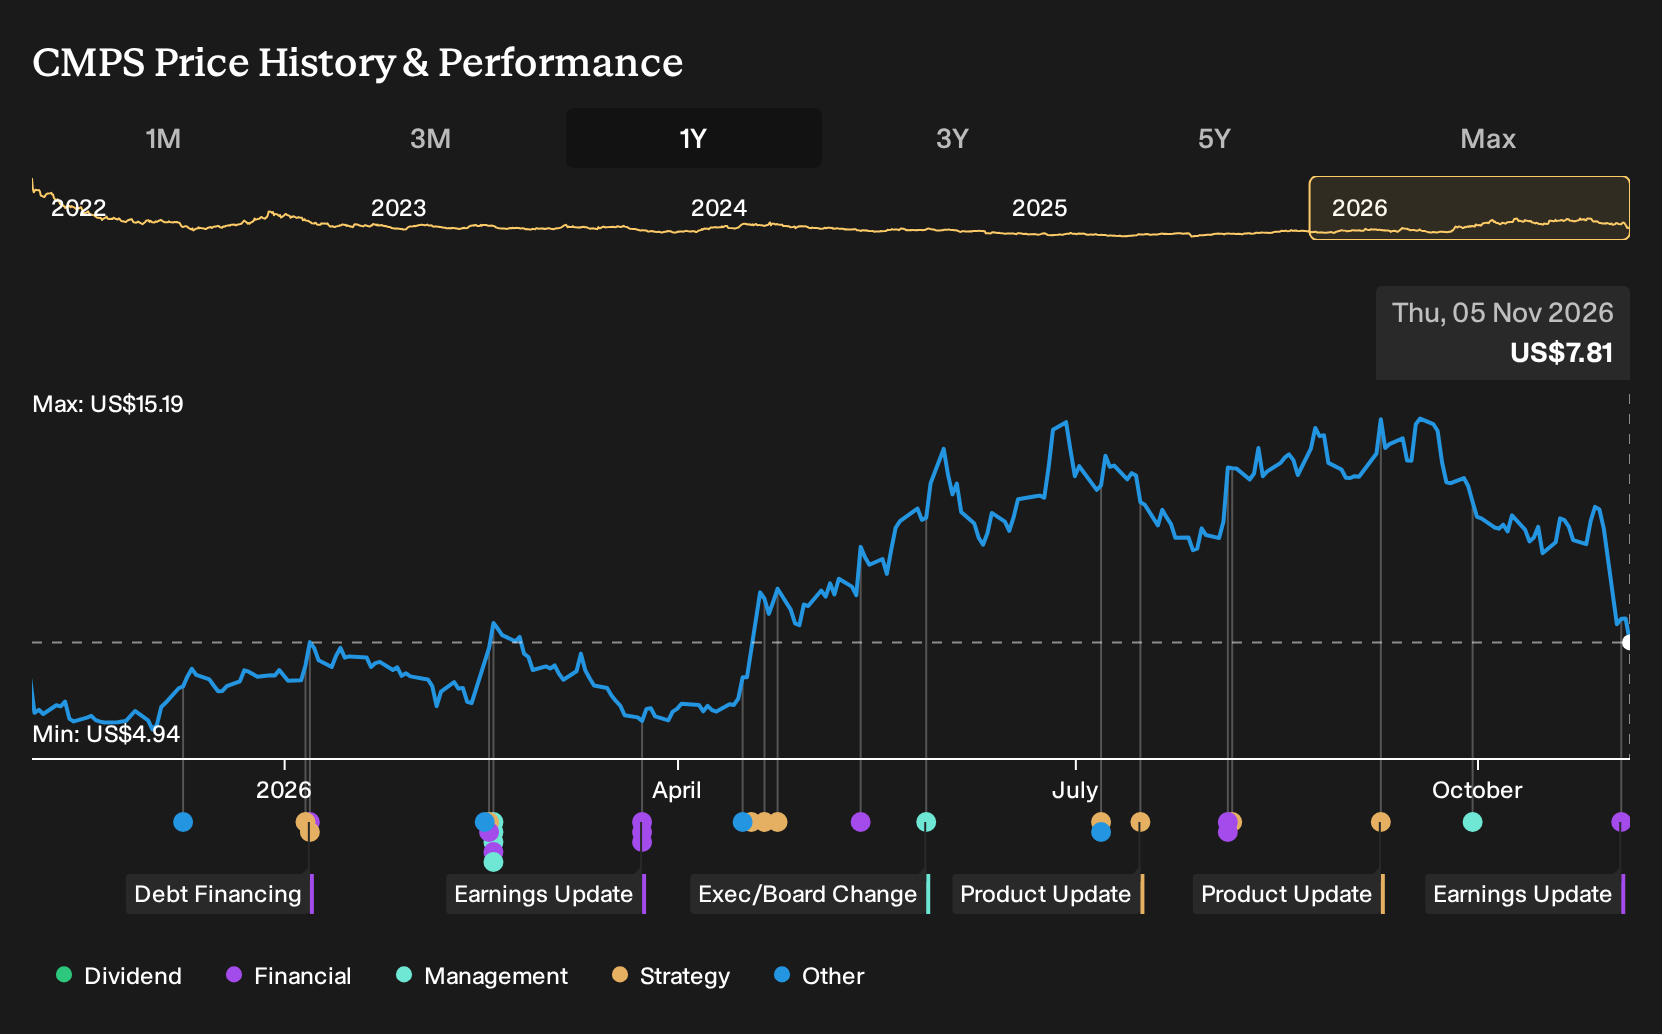
- COMPASS Pathways reported a net loss of US$9.83 million for Q3 2026 and US$172.42 million for the first nine months, alongside a plan to complete its rolling FDA submission for COMP360 psilocybin therapy and prepare for a potential commercial rollout.
- The sharp reduction in quarterly loss per share compared with the prior year, combined with management highlighting cash reserves that support operations into 2028, points to a business model shifting from pure clinical development toward a potential commercial footing for COMP360.
- We will now assess how COMPASS Pathways' rolling FDA filing for COMP360 could influence its investment narrative as commercialization approaches.
Scan beyond COMPASS Pathways and review other late-stage healthcare stories with solid balance sheets using our hand picked list of solid balance sheet and fundamentals (24 results) as potential comparables.
COMPASS Pathways Investment Narrative Recap
To own COMPASS Pathways, you need to believe COMP360 can move from late stage development into an approved, commercially adopted therapy supported by interventional psychiatry clinics. The sharp drop in quarterly loss and confirmation of cash runway into 2028 ease near term funding concerns. The key near term catalyst remains regulatory progress on the rolling FDA submission for treatment resistant depression.
The biggest risk still sits with clinical and regulatory outcomes, plus whether real world adoption and reimbursement line up with the commercial build out. The latest earnings do not remove those uncertainties. They mainly show COMPASS Pathways entering the launch preparation phase with tighter losses and a clearer operational plan.
The most relevant update is management’s plan to complete the rolling New Drug Application for COMP360 within roughly two weeks of the November 3 earnings call. That filing milestone lines up directly with the main catalyst investors watch, which is the transition from pure R&D to a potential first approved product in treatment resistant depression.
The same announcement also mentioned preparations to use existing interventional psychiatry clinics for delivery and pointed to cash resources that management expects to fund activity through the initial rollout and into 2028. For investors, the focus now is whether COMPASS Pathways can execute that commercial build without letting pre launch costs, slower than expected prescriber uptake, or any regulatory issues erode that runway.
COMPASS Pathways' current analyst narrative points to forecast revenue of US$284.9 million and earnings of US$53.9 million by 2029. This implies a move from no revenue today and a loss of US$192.4 million in current earnings to positive earnings, which represents an earnings increase of about US$246.3 million if the forecast is reached.
Uncover why COMPASS Pathways' fair value indicates a 213% potential upside to its current price that could close much faster than many investors expect.
Exploring Other Perspectives
One alternate view around COMPASS Pathways centers on how quickly revenue might scale once COMP360 is on the market. The most optimistic analysts were already modelling about US$743.4 million in sales and US$32.5 million in earnings by 2029, far above the consensus US$284.9 million and US$53.9 million figures. This shows how widely expectations differ and may shift after this latest update.
Explore 3 other COMPASS Pathways fair value estimates, including one that suggests potential upside of as much as 1967% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your COMPASS Pathways research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for COMPASS Pathways. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate COMPASS Pathways' overall financial health at a glance.
Looking for more investment ideas beyond COMPASS Pathways?
Once you have formed a view on COMPASS Pathways, it can help to compare that thesis with a wider watchlist of companies that share some of the qualities you care about, whether that is balance sheet strength, income potential, or mispriced opportunities the broader market has not focused on yet.
Use the Simply Wall St Screener to scan for stocks that fit those preferences and pressure test your COMPASS Pathways thesis against a broader set of potential candidates.
- If you are hunting for potential turnaround opportunities with higher risk and smaller market values, you can survey a focused group of 9 elite penny stocks with strong financials that might warrant a closer look.
- If quality at a reasonable price is your priority, compare COMPASS Pathways with a curated pool of 42 high quality undervalued stocks that pair solid fundamentals with more modest pricing.
- If portfolio income matters to you, balance growth stories like COMPASS Pathways with a short list of 6 dividend fortresses that already return cash to shareholders today.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com