
Select Water Solutions (WTTR) Stock Looks Overvalued On Current Earnings
Select Water Solutions has had a strong multi‑year share price run, and after a sharp recent pullback, the question is whether the current US$15.44 price is still in line with what its earnings can justify. With a busy deal calendar and fresh capital in place, the stock now invites a closer look through a pure earnings lens rather than just price moves.
- Over the past 5 years the stock has returned about 158.6%, which puts real pressure on the underlying earnings story to support that kind of compounding.
- The completed US$700 million acquisition of Pilot Water Solutions, backed by a new US$500 million revolving credit facility, can reshape earnings power by altering both operating scale and ongoing financing needs.
- Your read on Select Water Solutions is one view; the desks covering it have another. See what analysts think Select Water Solutions's shares could be worth.
For investors, the debate is whether Select Water Solutions' current share price is adequately supported by the earnings the business is generating today and is expected to produce over time.
If you are weighing whether Select Water Solutions' earnings justify the recent share price swings, it can help to compare it with other 42 high quality undervalued stocks as a second starting point for research.
Does Select Water Solutions Look Pricey on Earnings?
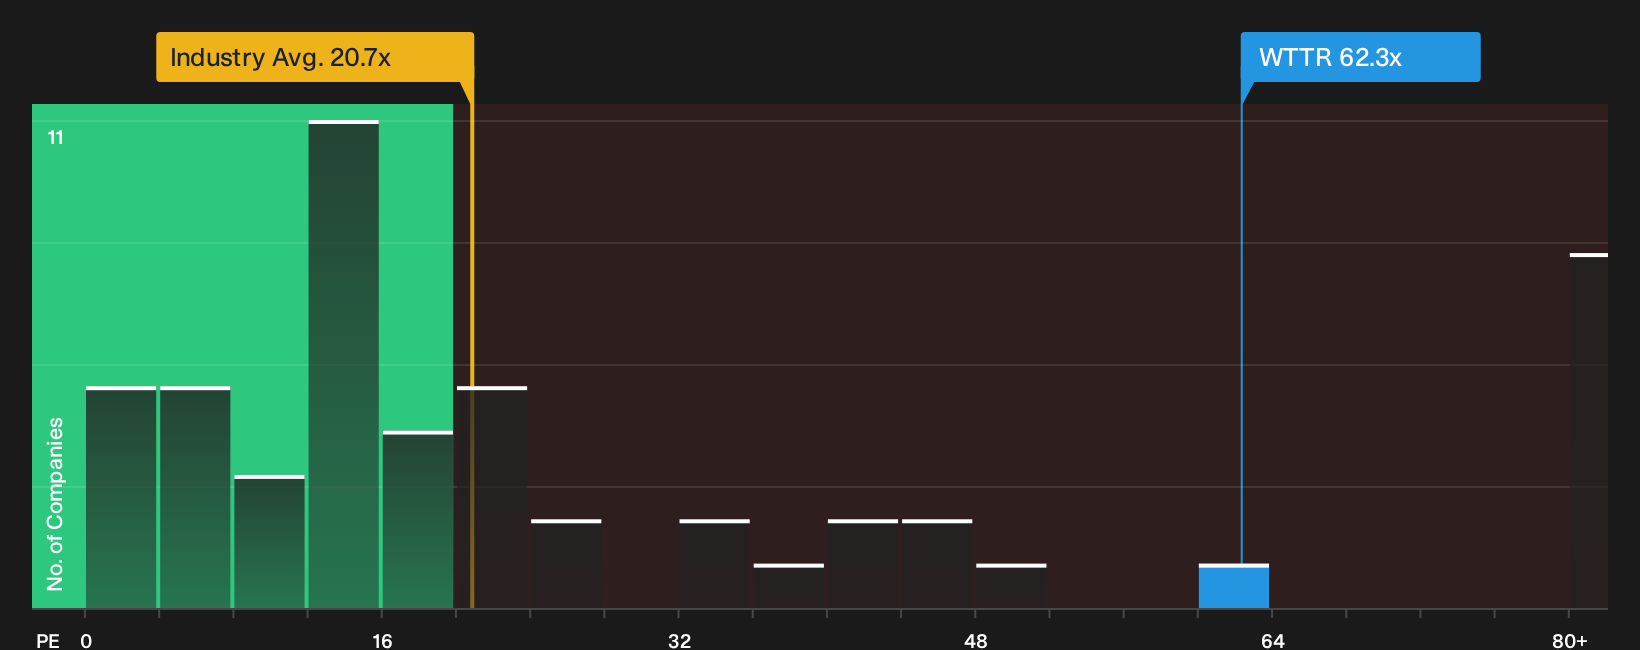
The P/E ratio fits Select Water Solutions because earnings are still the main anchor for how the market sizes up this kind of Energy Services business. On that measure, the stock trades at about 62.3x earnings, compared with an industry average near 20.7x and a peer group closer to 79.6x, so the valuation sits well above the broader sector while still below similar companies.
Because the P/E that might be expected given Select Water Solutions' growth profile, margins, scale and risk comes in lower than the current 62.3x, the shares screen as overvalued on this model. Despite the recently completed US$700 million acquisition of Pilot Water Solutions and the new US$500 million credit facility supporting that move, the market is still assigning a richer earnings multiple than this framework suggests. This leaves the burden of proof on future results to close the gap. Explore the numbers behind Select Water Solutions's P/E valuation.
The Select Water Solutions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Select Water Solutions pick up where the valuation puzzle leaves off by spelling out what sort of future growth, profitability and earnings profile would need to hold for the shares to be worth materially more or less than today. Rather than pointing to a single P/E or model output, each Narrative sets out the assumptions behind its view of fair value so you can compare those expectations with the actual numbers as new results arrive.
One of the top community narratives on Select Water Solutions: 37% undervalued
"The current valuation implies the share price does not fully reflect the company’s mix of long-term, contract-backed water midstream cash flows..."
Discover why this Narrative puts Select Water Solutions at 37% undervalued.
One more angle on Select Water Solutions that can change how you see the earnings story
Everything so far has focused on what Select Water Solutions looks like today, but professional estimates for where the business could be a few years from now offer a separate yardstick that is worth lining up against the current share price. Explore where analysts expect Select Water Solutions to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com