
Earnings Beat May Reset The Case For ZoomInfo Stock
- ZoomInfo Technologies reported Q3 2026 GAAP revenue of US$308.8 million, met adjusted EPS expectations, and raised its full-year 2026 revenue guidance to a range of US$1.2235 billion to US$1.2265 billion, with Q4 guidance set at US$294 million to US$297 million.
- Alongside the guidance lift, ZoomInfo is pushing deeper into AI driven workflows through new integrations with Notion, Snowflake, and Exa, which connect its GTM data directly into the platforms where enterprise teams already work.
- This article will examine how ZoomInfo's raised 2026 revenue outlook, supported by stronger large customer traction, fits into the broader investment narrative.
Scan beyond ZoomInfo Technologies to see how other AI driven go to market platforms and data providers stack up in our hand picked list of 41 profitable AI stocks that aren't just burning cash.
ZoomInfo Technologies Investment Narrative Recap
To own ZoomInfo Technologies, you need to believe its role as a core go to market data layer for large enterprises can outweigh current profit volatility and revenue pressure. The raised 2026 revenue guidance suggests management sees steadier demand than headline GAAP figures indicate, even as nine month sales sit essentially flat and losses remain heavy.
The key near term catalyst is execution on upmarket customers and AI driven workflows that translate into more durable, higher value contracts. The biggest risk is still concentration and churn, especially as downmarket revenue declines and net income and EPS remain weak. This update looks directionally supportive but not transformational.
The Snowflake AI Data Cloud integration is especially relevant here. It takes ZoomInfo data and AI orchestration directly into where sales, RevOps, and data teams already work, and it supports both natural language querying and large scale enrichment through APIs and Bulk endpoints.
For catalysts, this kind of deep embedding can help stickiness with large accounts and support the guidance lift if usage grows across sales, operations, and analytics teams. The flip side is execution risk around data quality, privacy, and performance at scale, which matters given customer concentration and already high investment in AI workflows.
ZoomInfo Technologies' current analyst narrative points to revenues of US$1.2b and earnings of US$391.8 million by 2029, based on an assumed 1.3% yearly revenue decline. Earnings are projected to move from a loss of US$541.0 million today to that US$391.8 million profit, a swing of about US$932.8 million.
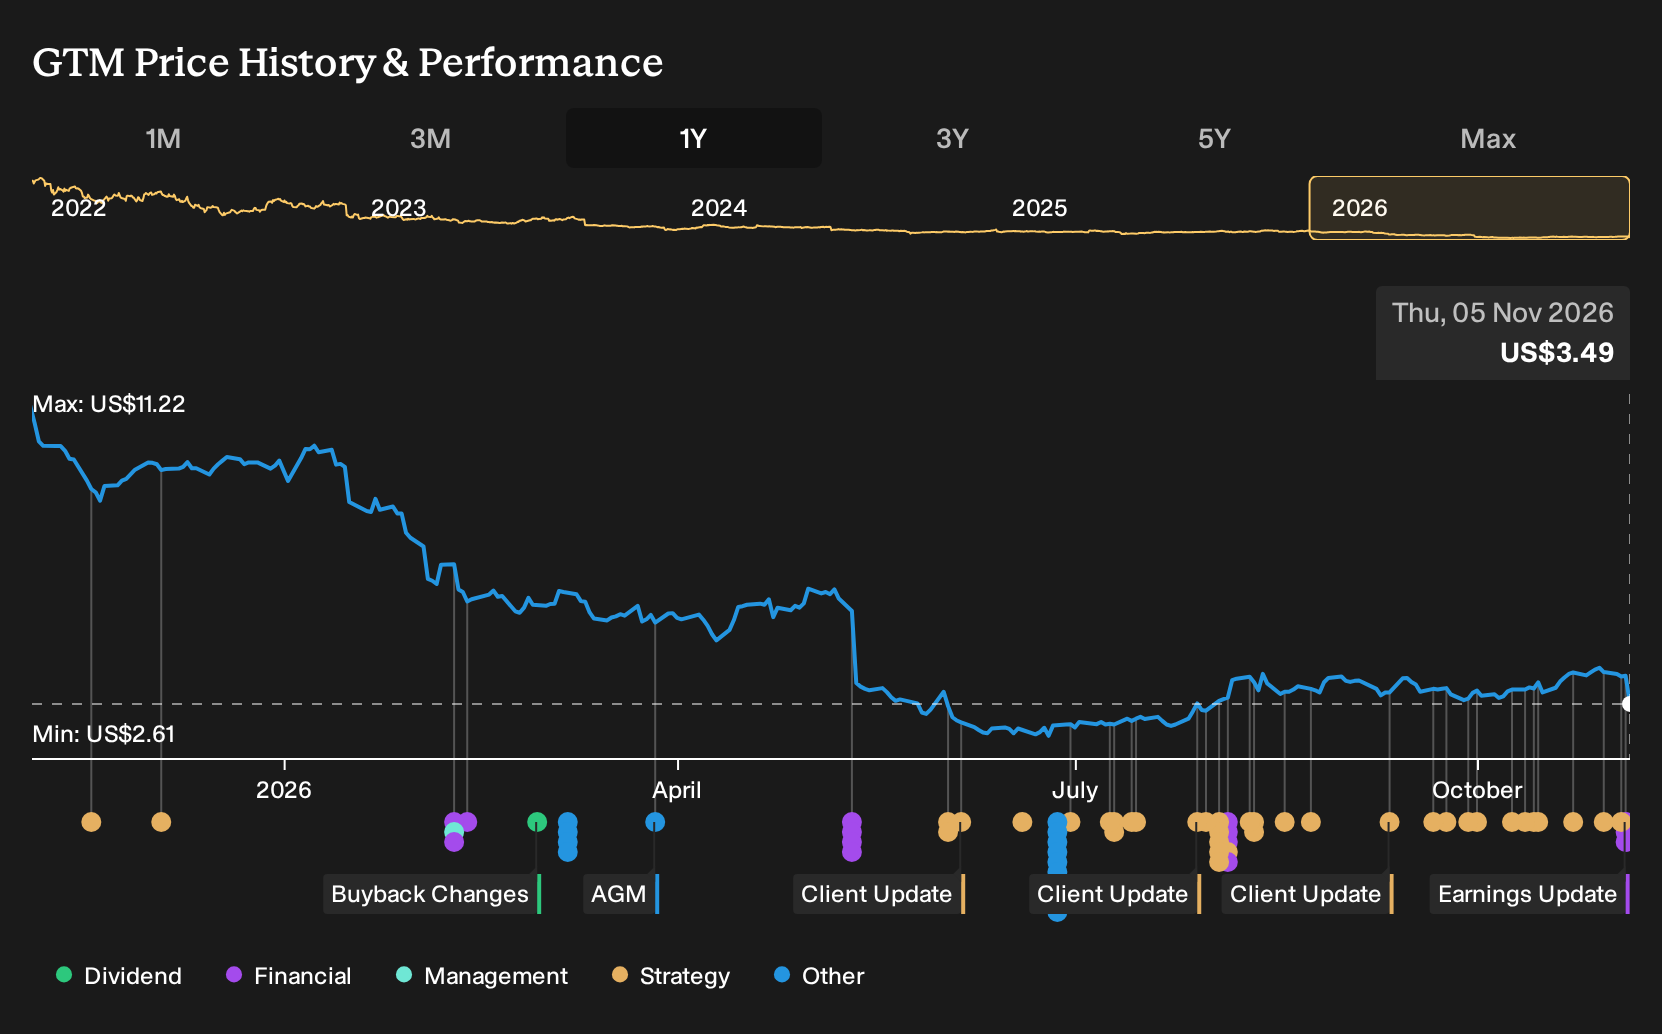
Uncover why ZoomInfo Technologies' fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on ZoomInfo Technologies focuses on margin potential rather than AI product reach. The most optimistic analysts were already modeling profit margins rising to 29.8% and earnings of about US$366.1 million by 2029, compared with more cautious peers. Those views predate this guidance hike, so opinions and models may shift as you reassess the spread of forecasts.
Explore 4 other ZoomInfo Technologies fair value estimates, including one that suggests potential upside of up to 253% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your ZoomInfo Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ZoomInfo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate ZoomInfo Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond ZoomInfo Technologies?
If ZoomInfo Technologies has you thinking about where to allocate capital next, the Simply Wall St Screener can help you scan for other companies that fit your style and risk appetite in a structured, data driven way.
- If you want potential value with stronger fundamentals, start by reviewing a 21 high quality undiscovered gems that could be flying under the radar.
- If capital preservation is front of mind, narrow your focus to a 32 resilient stocks with low risk scores that scores well on resilience metrics and balance sheet strength.
- If you care about durable income alongside price appreciation, filter for a 6 dividend fortresses that may suit a more income focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com