
Avis Budget Group (CAR) Stock Still Looks Undervalued After A 53% Slide
Avis Budget Group has seen its stock price move around sharply in recent years, and that raises a straightforward question for investors who care about the basics. Is the current share price of Avis Budget Group still in line with what the business is generating in sales.
- Over the past 5 years the stock has fallen 52.5%. That puts the focus squarely on whether today's valuation can still be anchored in the revenue the rental car group brings in.
- Recent earnings headlines have highlighted both a decline in profit and record vehicle utilization. These factors can influence how investors think about future revenue quality, margins and the timing of cash generation that support any sales based multiple.
- Your read on Avis Budget Group is one view; the desks covering it have another. See what analysts think Avis Budget Group's shares could be worth.
The issue now is whether Avis Budget Group's current share price is justified by its sales once you line it up against a Fair Ratio benchmark.
As you weigh whether Avis Budget Group's current price still lines up with its sales, it can help to compare that sales based story with 42 high quality undervalued stocks.
Is Avis Budget Group Still Cheap on Sales?
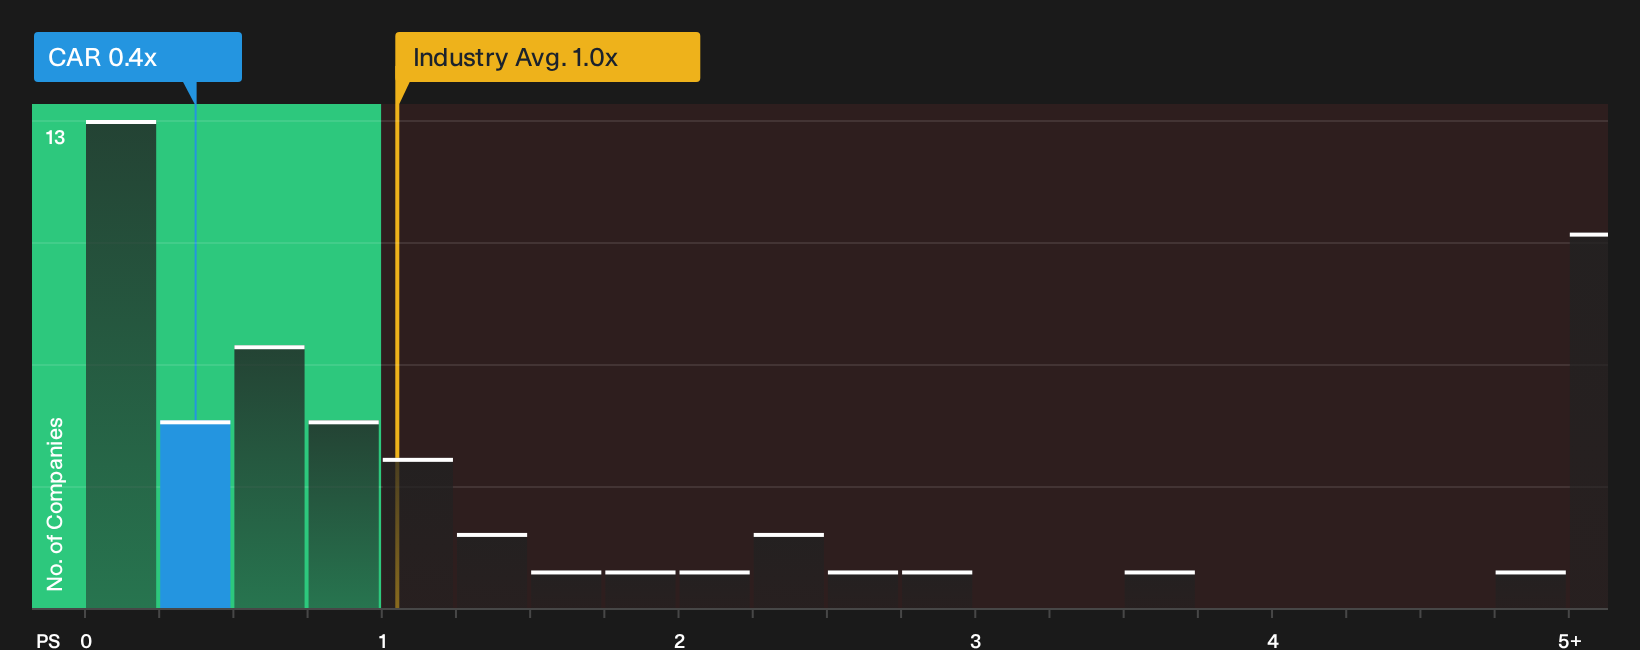
P/S works well for Avis Budget Group because investors often focus on how much revenue each dollar of share price represents in rental car businesses. The stock is trading on a P/S ratio of 0.4x, compared with about 1.0x for the wider Transportation industry and roughly 1.5x for its closest peers, so the market is currently paying much less per dollar of sales than it does for similar operators.
Recent Q3 2026 results came with an earnings miss and an 8% decline in adjusted EBITDA, yet the P/S multiple still sits below the tailored Fair Ratio benchmark that reflects Avis Budget Group's own risk profile, margins and scale. Because that model based yardstick is higher than the current 0.4x, the shares screen as undervalued on sales, even after the headline pressure around profitability and the reaction in the share price. Explore the numbers behind Avis Budget Group's P/S valuation.
The Avis Budget Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle around Avis Budget Group leaves off. They spell out which combinations of future growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today's price, all hosted on the Community page. Each narrative links its number to a clear view on how Avis Budget Group's revenue profile, profitability and risk might evolve, which you can revisit as fresh information comes through.
Community views on Avis Budget Group are split between those who see more upside in the current setup and others who think expectations already look full.
Bull case: 14% undervalued
"The shift to treating fleet as capital at risk, with mid single digit cuts to Americas fleet size while maintaining rental days…"
Discover why this Narrative puts Avis Budget Group at 14% undervalued.
Bear case: roughly fairly valued
"Recall campaigns have already grounded a meaningful portion of the Avis Budget Group fleet and created more than US$50 million of directly attributable costs…"
Explore why this Narrative puts Avis Budget Group at roughly fairly valued.
Avis Budget Group’s price is only one piece of the decision
Numbers on the screen tell you what the market pays for Avis Budget Group today, but the people steering the business and how they are rewarded can heavily influence what happens next. See who runs Avis Budget Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com