
What Atlanticus Holdings Stock Earnings Beat Means For Shareholders
- Atlanticus Holdings reported Q3 2026 net income of US$95.35 million compared with US$24.98 million a year earlier, with both basic and diluted earnings per share from continuing operations above the prior period.
- The nine month figures show net income of US$189.24 million versus US$87.07 million a year ago, which indicates materially stronger profitability across the core credit portfolio and a meaningfully higher earnings base for the business.
- We will now explore how Atlanticus Holdings' sharply higher earnings per share might influence the existing investment narrative that investors have been using.
Scan how Atlanticus Holdings' earnings jump compares with other financially solid opportunities by reviewing our curated list of solid balance sheet and fundamentals (24 results) for your next round of ideas.
Atlanticus Holdings Investment Narrative Recap
To own Atlanticus Holdings, you need to believe it can keep scaling near prime and underserved lending while managing credit quality, funding costs, and integration work from recent portfolio deals. The Q3 2026 earnings jump strengthens the case that the core model currently supports higher earnings, but it does not remove exposure to more fragile consumers or competition in cards and point of sale financing.
In the short term, the main positive catalyst is how effectively Atlanticus Holdings embeds the enlarged Mercury related portfolio onto its platform to support returns and cost efficiency. The biggest risk still sits in credit performance and funding. A weaker consumer or tighter capital markets could quickly offset some of the benefit from the latest results.
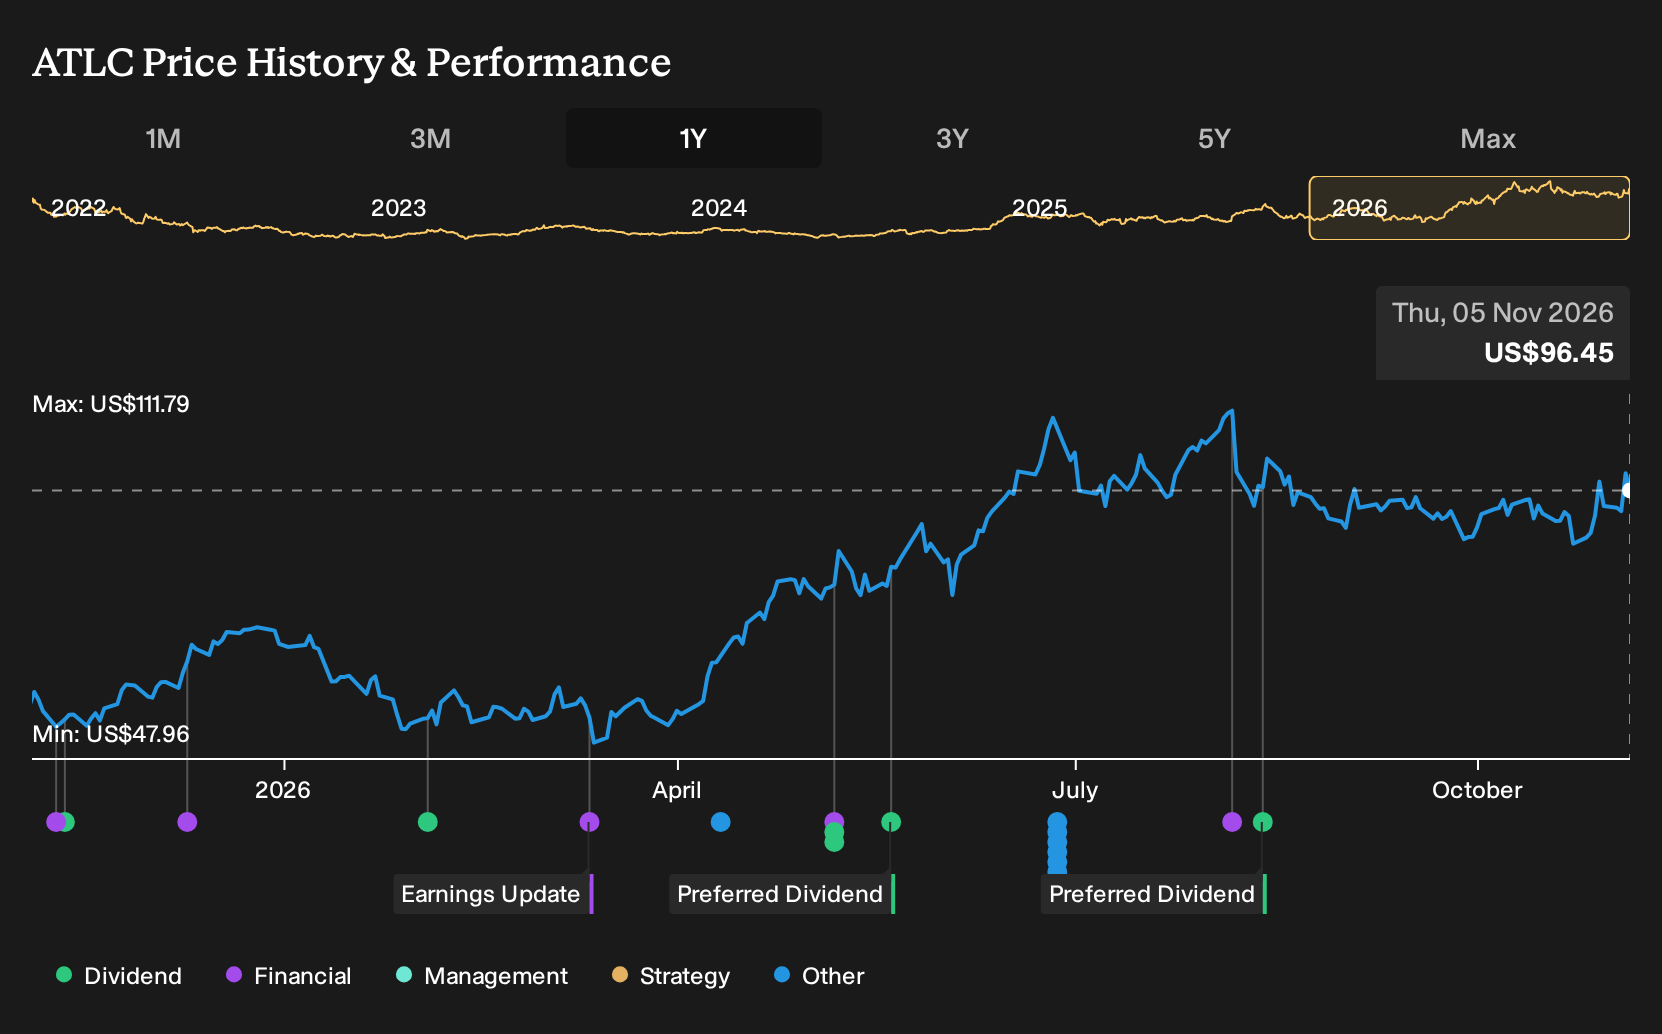
The most relevant development here is the Q3 2026 earnings release on 5 November. Management reported US$95.35 million of quarterly net income and US$189.24 million for the nine month period, with both basic and diluted earnings per share from continuing operations above the prior year. That places fresh data around how the enlarged receivables base is performing.
For you as a shareholder or potential investor, this update helps test the core catalysts around scale, integration and funding. Higher earnings give Atlanticus Holdings more flexibility to keep investing in marketing, technology, and integration work while servicing its largely non deposit funding stack. The same release also keeps the focus on the long list of risks, particularly debt coverage by operating cash flow and sensitivity to any deterioration in customer payment behavior.
Atlanticus Holdings' current analyst story points to US$5.5b of revenue and US$451.9 million of earnings by 2029, based on an assumed 96.2% yearly revenue growth rate and a move from US$144.8 million of earnings today to the 2029 consensus figure, which is a little more than 3x higher than the current level.
Discover why Atlanticus Holdings' fair value indicates a 38% potential upside to its current price, which could diminish quickly.
Exploring Other Perspectives
One alternate view focuses on credit strain rather than growth. The most cautious analysts worried that higher fuel and living costs could hit Atlanticus Holdings customers hard. They were already baking in earnings of about US$125.7 million, rising to US$490.5 million on roughly US$5.2b of revenue by 2029, yet still saw only a US$110 price target. That more pessimistic stance was set before this Q3 2026 earnings surprise, so you may want to compare those older assumptions with your own and see which story feels closer to your expectations.
Explore 4 other Atlanticus Holdings fair value estimates, including one that suggests there could be as much as 40% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Atlanticus Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Atlanticus Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atlanticus Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Atlanticus Holdings?
Once you are done weighing Atlanticus Holdings, it can help to zoom out and compare it with a wider field of companies that match the kind of risk and return profile you want in your portfolio.
- If you prefer potential mispricing opportunities backed by stronger fundamentals, scan a curated set of value ideas through 42 high quality undervalued stocks for your next round of candidates.
- If resilience and capital protection matter more to you than headline growth, focus your research on a 32 resilient stocks with low risk scores that already screens for sturdier business profiles.
- If you are hunting for companies that are not yet heavily followed but still show solid financial underpinnings, widen your watchlist with a hand picked pool of 21 high quality undiscovered gems that might fit your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com