
What ArcBest (ARCB)'s Earnings Beat Means For Shareholders
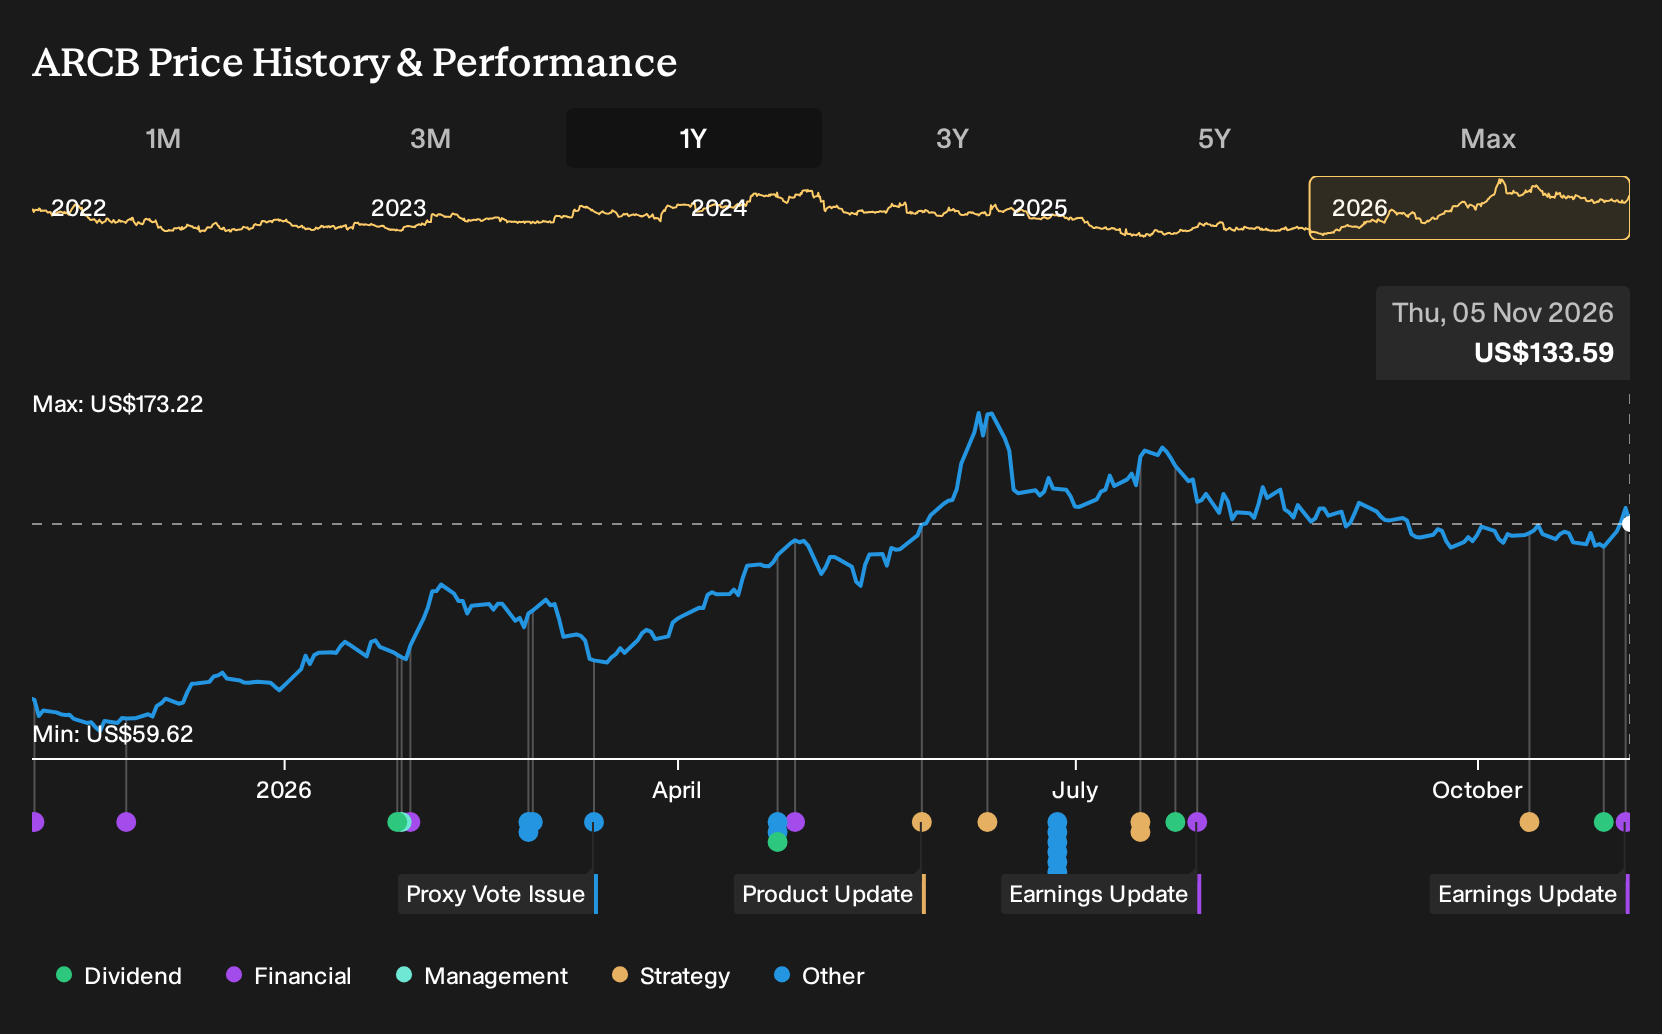
- ArcBest reported Q3 2026 revenue of US$1,210.5 million and net income of US$51.66 million, with earnings per share from continuing operations above the prior year, alongside a quarterly dividend of US$0.12 per share declared in October.
- The logistics provider paired stronger quarterly results with commentary on cost savings, AI driven tools and record managed logistics performance, highlighting how technology spending and network execution are shaping ArcBest’s operating profile.
- Now the focus shifts to how ArcBest’s stronger Q3 earnings, supported by pricing discipline, align with the existing investment narrative built around efficiency.
Scan ArcBest's earnings story against a curated pool of logistics focused opportunities by comparing it with our list of solid balance sheet and fundamentals (24 results)
ArcBest Investment Narrative Recap
To be comfortable owning ArcBest, you need to believe its freight network can convert tight truckload capacity and heavier LTL shipments into healthier profitability through technology and cost discipline. The Q3 2026 update supports that thesis in the near term, with higher sales, improved operating performance and better earnings per share from continuing operations.
The short term catalyst still sits in execution on network optimization, AI tools and pricing discipline, especially as freight demand remains uneven. The biggest risk remains mix and cost pressure. Heavier shipments, muted volumes in weaker end markets and rising insurance or claims costs could cap margin progress if pricing power softens.
The clearest recent marker for that thesis is ArcBest's Q3 2026 earnings release. Revenue of US$1,210.5 million and net income of US$51.66 million, both above the prior year, point to more effective use of its asset based and asset light platforms. Management linked this to cost reductions, freight mix and new digital tools.
That same update also flagged a record quarter in managed logistics and continuing roll out of ArcBest's AI driven systems and transportation management platform. For you, the near term watch list is simple: do these tools keep supporting productivity and pricing discipline, or do softer freight trends and higher operating costs reassert themselves?
ArcBest's analyst narrative points to revenues of US$5.4b and earnings of US$426.4 million by 2029, based on forecast revenue growth of 8.8% a year and an earnings increase of about US$410 million from US$16.3 million today.
Uncover why ArcBest's fair value indicates a 27% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
One alternate view on ArcBest leans heavily on pricing pressure. The most cautious analysts worry that wider use of digital freight tools could limit future rate gains, which feeds into their softer targets of about US$5.2b of revenue and US$395.2 million of earnings by 2029. These pre Q3 estimates are more pessimistic than consensus, so treat them as one of several angles to compare against the fresh earnings news.
Explore 2 other ArcBest fair value estimates, including one that suggests as much as 42% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ArcBest research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for ArcBest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ArcBest's overall financial health at a glance.
Looking For More Investment Ideas Beyond ArcBest?
If ArcBest has earned a spot on your watchlist, it can be helpful to benchmark it against other opportunities that share similar strengths or cater to different priorities. The Simply Wall St Screener lets you filter for qualities that matter to you, from balance sheet resilience to income potential.
- If capital preservation is at the top of your list, start by reviewing 32 resilient stocks with low risk scores that have historically paired steadier fundamentals with lower overall risk profiles.
- If value is your priority, compare ArcBest with a curated 42 high quality undervalued stocks that combine solid cash flows with stronger balance sheets.
- If income is a focus, look at 6 dividend fortresses that target 5%+ yields and may appeal to investors seeking more consistent payout streams.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com