
Why Did Brink's (BCO) Stock Drop After Its Latest Update?
Brink's (BCO) just released a mixed third quarter update that combined record profitability in key service lines with softer top-line momentum and a guidance range that came in lighter than many investors expected.
Brink's shares have been choppy around the earnings release, with the 1-day share price return down 2.69% even after a 7.62% gain over the past week. The year-to-date share price return has slipped 5.56% as investors weigh guidance and the NCR Atleos deal against a 79.34% total shareholder return over five years.
Compare Brink's mixed reaction to earnings with other contract-based service providers by scanning our hand picked list of 32 resilient stocks with low risk scores that may offer steadier risk profiles.
Brink's just posted record margins while the share price has already delivered a strong multi year run, so the real question now is whether the meat of the upside is ahead or mostly behind as valuation comes into focus.
Most Popular Narrative: 25% Undervalued
With Brink's last closing price at $109.98 against a widely followed fair value anchor of $146.33, the current setup hinges on whether investors buy into a much larger, higher margin business emerging from ATM Managed Services, Digital Retail Solutions and the Atleos integration.
The NCR Atleos acquisition is expected to roughly double Brink's scale to about US$10b of revenue and US$2b of adjusted EBITDA with US$200m of cost synergies and an indicated lift to EPS in the first year. This could reset how investors value the company once the combined EBITDA margin and free cash flow profile are reflected in reported results.
See why 5 investors see Brink's as 25% undervalued.
Result: Fair Value of $146.33 (UNDERVALUED)
Still, the Brink's narrative can be knocked off course if cash usage falls faster than expected in key regions, or if the Atleos integration fails to deliver planned synergies.
Find out about the key risks to this Brink's narrative.
Another View On Brink's Valuation
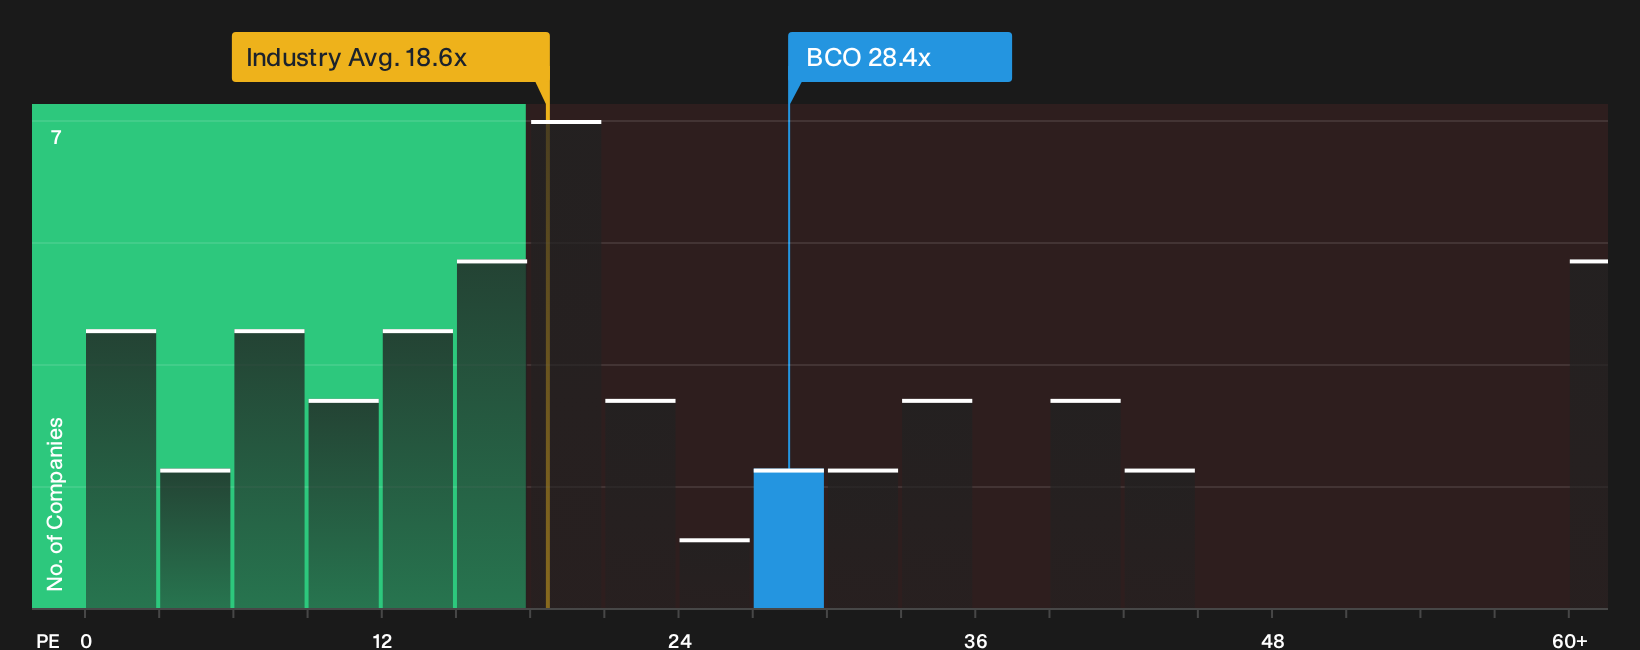
The story looks very different once you shift from fair value anchors to what the market is paying for Brink's earnings today. The stock trades on a P/E of 28.4x, which is higher than both peers at 22.2x and the wider US Commercial Services group at 19.1x.
Against an estimated fair ratio of 47.6x, the current multiple sits in the middle. Pricing looks richer than competitors but still below where the fair ratio suggests it could move, which raises a practical question for investors: Is that gap a cushion for future disappointment or room for sentiment to rebuild?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Brink's valuation can pull you in both directions, so move quickly to weigh the evidence yourself and focus on what matters most. To examine the balance between upside potential and red flags, read the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Brink's?
If Brink's has your attention but you want a broader watchlist, now is the moment to line up a few high conviction candidates before the next wave of results hits.
- Target stronger balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio when conditions get tougher.
- Hunt for quality at a discount and review a 42 high quality undervalued stocks that screens for fundamentals first instead of just chasing headlines.
- Build a pipeline of future ideas by checking a 21 high quality undiscovered gems where fewer eyes may leave more pricing inefficiencies on the table.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com