
Is GXO Logistics (GXO) Reasonable After Record Contract Wins?
GXO Logistics has climbed recently, helped by fresh contracts and expansion projects. This puts a spotlight on whether the current US$55.18 share price lines up with what the business earns today. With the stock carrying a mixed return record over different timeframes, the key issue is how those earnings stack up against what investors are now paying for each dollar of profit.
- Over 5 years the share price has fallen 42.3%. This makes the current valuation question more about what the earnings profile now justifies than about past highs or lows.
- Recent contract wins, a growing sales pipeline and new logistics hubs may support expectations for future profitability. This matters directly for any earnings based multiple investors are willing to accept.
- The analysts covering GXO Logistics have run their own numbers. See what analysts think GXO Logistics's shares could be worth.
The issue now is whether GXO Logistics' current market price is adequately supported by its earnings when judged against a Fair Ratio benchmark.
If you want to examine this same earnings question beyond GXO Logistics, apply the same analysis to a broader group of 89 robotics and automation stocks
Does GXO Logistics Look Pricey on Earnings?
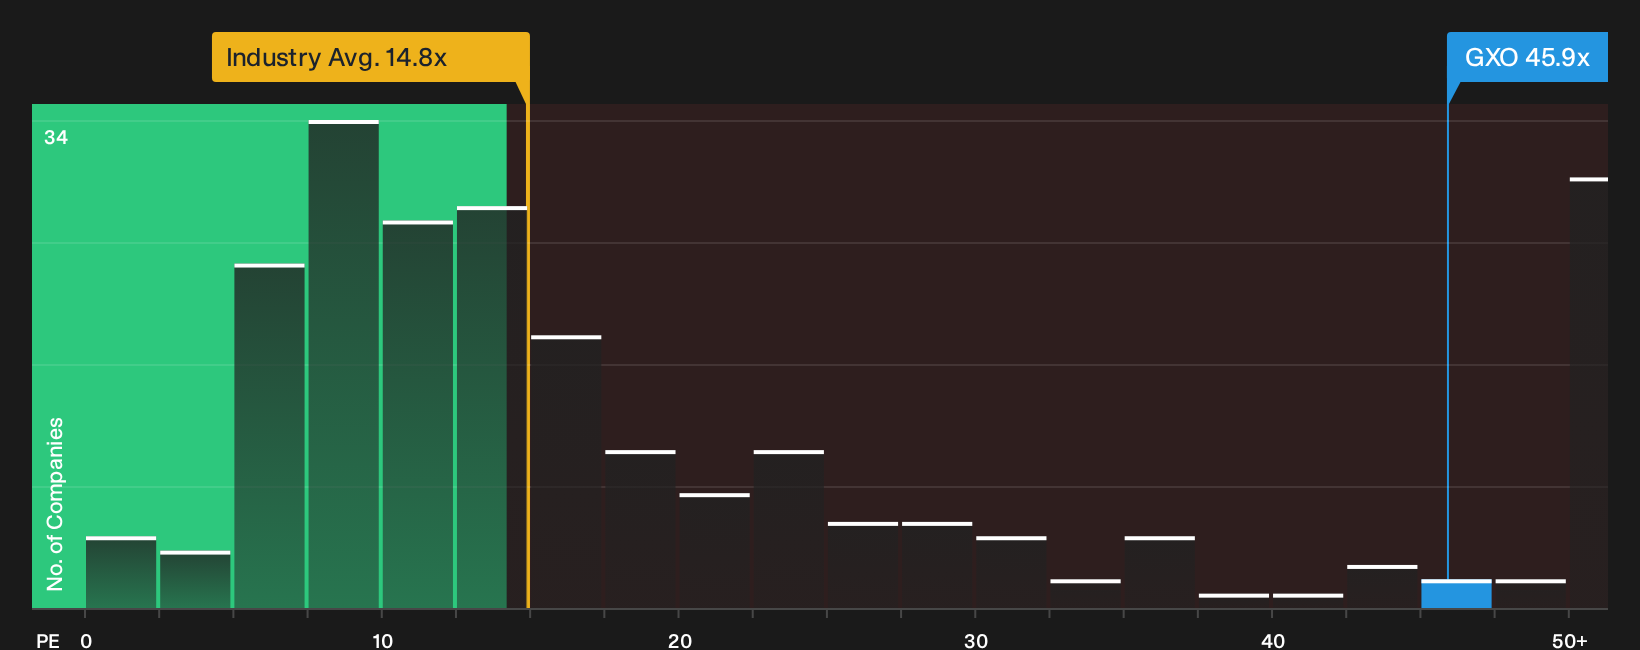
The P/E ratio is a useful way to look at GXO Logistics because earnings sit at the center of how investors value this kind of asset light logistics operator. At about 45.9x earnings, the stock trades well above the broader logistics sector, where the average P/E is around 14.8x. It is also higher than the peer group reference point of roughly 17.6x, which already reflects how similar businesses are priced.
A Fair Ratio benchmark, which adjusts for factors like growth profile, margins, size and risk, comes in lower than the current P/E, so the shares screen as overvalued on this measure. Despite the strong Q3 2026 update and record US$3.1b sales pipeline, the valuation already assigns a rich price tag to GXO Logistics relative to both sector norms and that tailored benchmark. Explore the numbers behind GXO Logistics's P/E valuation.
The GXO Logistics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for GXO Logistics leaves off and explain in plain terms what kind of future in growth, margins and earnings would need to occur for the stock to be worth materially more or less than it is today on the screen. Rather than giving a single number, they outline the business path that number relies on so you can follow how reality compares with it over time on the Community page.
The GXO Logistics community is divided between investors who see underappreciated contract momentum and margin potential, and others who focus on cash conversion and uncertainty around robotics.
Bull case: 20% undervalued
"The focus on long-term multiyear contracts with blue chip customers, high retention around the mid-90s, and more than US$1 billion of incremental 2026 revenue already secured supports resilient contracted cash flows that can improve earnings visibility and support more consistent free cash flow conversion over time..."
Discover why this Narrative puts GXO Logistics at 20% undervalued.
Bear case: 25% overvalued
"GXO’s apparent discount loses conviction when adjusted for negative first-half free cash flow, back-end-loaded guidance, meaningful leverage, Wincanton integration risk, minimal discretionary insider buying, unproven robotics economics, and a valuation that is highly sensitive to cash-conversion assumptions..."
Explore why this Narrative puts GXO Logistics at 25% overvalued.
One more piece of the GXO Logistics puzzle before you decide
Current multiples tell you what the market is willing to pay today. However, the projected earnings path a few years out offers a different reference point that can sharpen your own view. Explore where analysts expect GXO Logistics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com