
Has Modine Manufacturing (MOD) Fallen Far Enough to Still Be a Bargain?
Modine Manufacturing has seen a sharp pullback in its share price after an extended multi year climb, which puts fresh focus on whether the current valuation can still be explained by its earnings power. With the stock now around US$91.39, the question is how this new level lines up with what the underlying business is generating in profit.
- Over the past 5 years the share price has risen by about 7x. As a result, a lot of the discussion now revolves around how much earnings strength is already reflected in that move.
- Recent news around strong top line gains, pressure on gross margins, and a shift toward lower margin activities can influence how investors think about the durability and quality of Modine Manufacturing’s earnings stream.
- There is a second opinion on Modine Manufacturing worth weighing. See what analysts think Modine Manufacturing's shares could be worth.
The issue now is whether the stock price at today’s level is appropriately aligned with Modine Manufacturing’s current and expected earnings profile.
If you want a broader yardstick for Modine Manufacturing’s recent swings and earnings focus, compare it to 40 power grid technology and infrastructure stocks.
Does Modine Manufacturing Look Undervalued on Earnings?
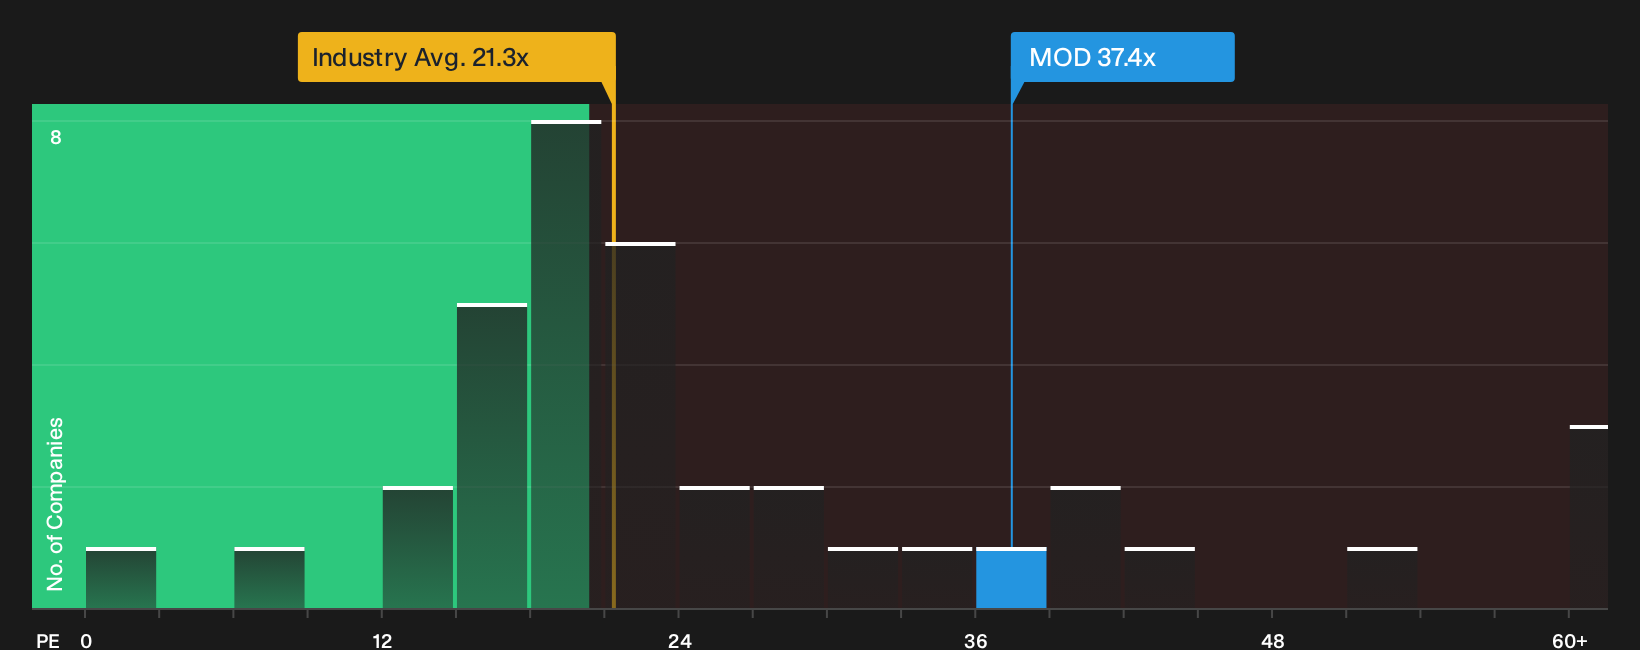
The P/E ratio matters most for Modine Manufacturing because investor attention is firmly on earnings power after the recent pullback. On this yardstick, Modine trades at about 37.4x earnings, which is much richer than the Building industry average of roughly 21.3x and above peers around 24.2x. Because the fair multiple for this business profile is lower than today’s P/E, the stock screens as overvalued on this model.
Because the recent results showed strong sales but pressure on gross margins and a tilt toward lower margin activities, that premium P/E multiple already bakes in a lot of optimism on future profitability. For anyone looking at Modine Manufacturing today, the key question is whether the earnings stream that emerges after the spin off and margin reset can justify paying well above sector and peer levels on this earnings measure. Explore the numbers behind Modine Manufacturing's P/E valuation.
The Modine Manufacturing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Modine Manufacturing pick up where the P/E puzzle leaves off. They spell out which views on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each narrative ties its number to a clear stance on how Modine Manufacturing’s expansion, profitability mix and key risks might evolve, giving you something concrete to revisit as fresh results arrive on the Community page.
One of the top community narratives on Modine Manufacturing: 69% undervalued
"The main thing that has to go right is execution on the climate solutions pivot, including the Performance Technologies spin off and the ramp of new data center and Commercial HVAC capacity…"
Discover why this Narrative puts Modine Manufacturing at 69% undervalued.
One more Modine Manufacturing angle worth checking before you move on
There is a whole other lens on Modine Manufacturing that sits outside today's multiples and recent results. This perspective focuses on where professional coverage sees this business a few years from now. Explore where analysts expect Modine Manufacturing to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com