
China IoT: China's road logistics freight rate index in October was 104.9 points, down 0.22% month-on-month
The Zhitong Finance App learned that in October 2026, the China Highway Logistics Freight Index, which was jointly surveyed by the China Federation of Logistics and Purchasing and Lin'an Logistics Group, was 104.9 points, down 0.22% from the previous year and 0.06% from last year. Looking at the month, the first-week, third-week, and five-week freight rate index rebounded, while the second and fourth week freight indices declined somewhat month-on-month.
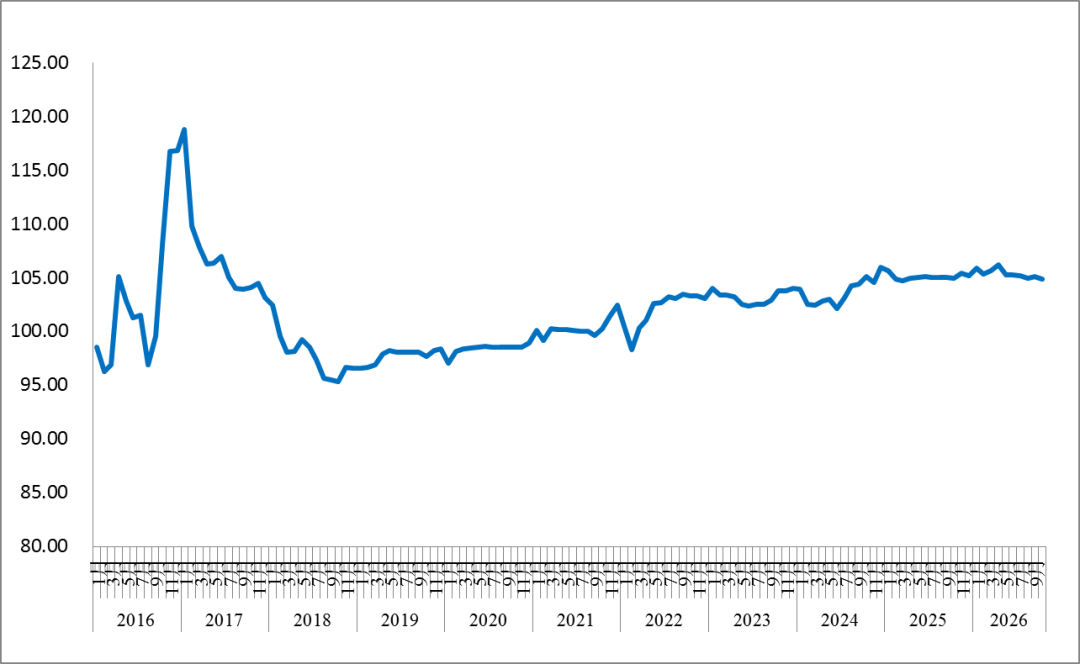
Figure 1 Road logistics rate index for each month since 2016
Table 1 China Highway Logistics Tariff Index for October 2026
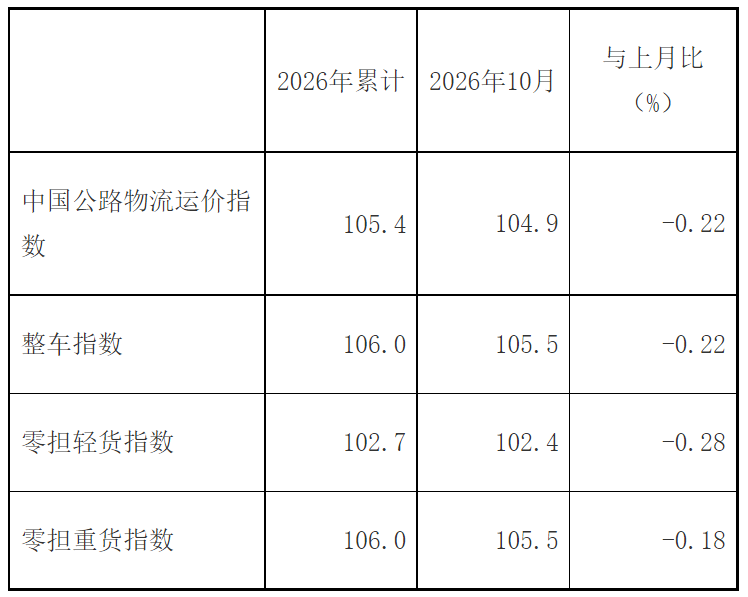
Looking at the model index, the various model indices declined slightly from month to month, diverging from last year's trend. Among them, the vehicle index, which mainly focuses on commodities and regional transportation, was 105.5 points, down 0.22% month-on-month and 0.03% year-on-year. In the LTL index, the LTL light goods index was 102.4 points, down 0.28% month-on-month and 0.21% year-on-year; the LTL index was 105.5 points, down 0.18% month-on-month, which was basically the same as the previous year.
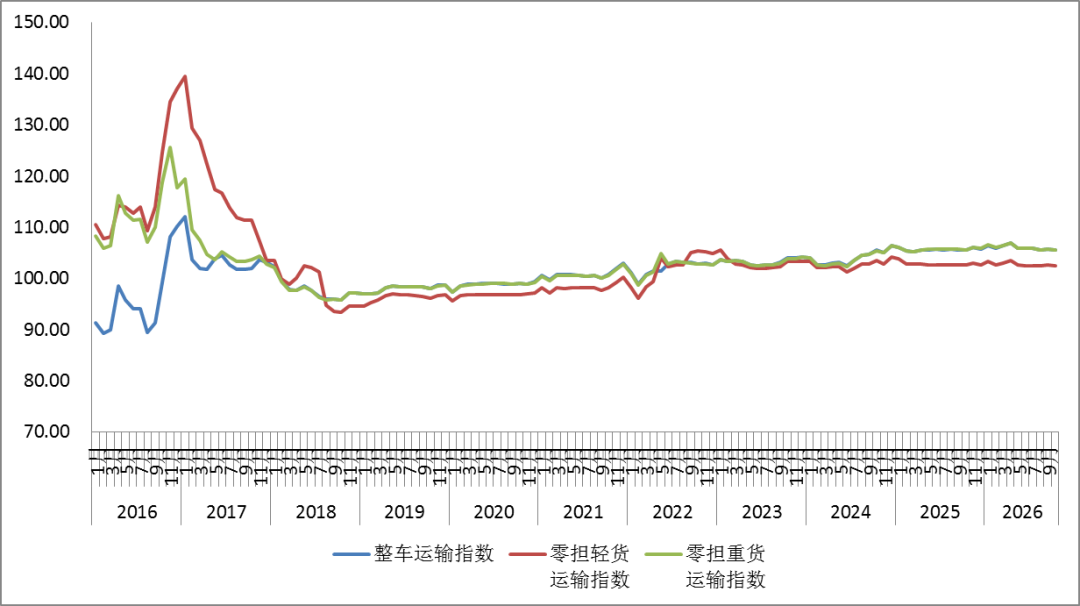
Figure 2 China Highway Logistics Tariff Index by Vehicle Model for Each Month Since 2016
The road transport market activity has slowed down this month compared to the previous period. Affected by short-term disturbances such as the National Day holiday, fluctuations on both sides of supply and demand were quite obvious, and the freight rate index showed a moderate fluctuation and slight correction. On the demand side, market demand is stabilizing and slowing down this month. First, the National Day holiday led to the early release of some demand and diluted the increase in demand this month; second, infrastructure projects, industrial production, construction industries, etc. resumed work slowly after the holiday season, and demand for transportation of bulk raw materials was weak. On the supply side, the supply of capacity remained high, and the situation of oversupply in the market continued. Only in the first week of resuming work after the holiday season, there were shortages in local areas and traffic on popular routes. Overall, the road transport market entered a short-term adjustment this month, and the freight rate index adjusted somewhat, but the steady and positive trend of production and construction in the fourth quarter did not change. The continued release of production and consumer demand at the end of the year provided a basis for a steady recovery in road transport. The relevant departments continue to rectify “internal rolling” low price competition, improve the road freight price monitoring system, promote the smooth flow of cost and price transmission mechanisms, and support the smoother and more orderly operation of road transport.
Looking at later trends, with the year-end industrial and infrastructure sprint targets for the whole year, and the arrival of the e-commerce “Double Eleven” peak season cycle, demand for bulk raw materials and express e-commerce orders are expected to increase significantly. Demand for road transportation may pick up overall, driving the freight rate index to rise slightly, but under the fundamentals of long-term excess capacity, there is limited room for freight rate increases. Meanwhile, the escalation of geopolitical tension in the Middle East has led to a high rise in oil prices. Labor and fuel costs for enterprises are still high, and rigid upward pressure on transportation costs may continue to show at the end of the year.