
AAR (AIR) Stock Could Be 35% Overvalued After MRO Deal Financing
AAR Corp. has ridden a powerful multi‑year share price climb while also committing to a large debt funded acquisition, which puts a simple question in front of investors who care about cash generation. Are the cash flows that AAR can produce over time enough to justify where the stock trades today?
- Over the past 5 years, AAR has delivered a 171.9% share price gain, so a lot of future cash flow is already being referenced by the current valuation debate.
- The planned acquisition of MRO Holdings, backed by a US$1.92b senior notes offering and a larger revolving credit facility, can reshape both AAR's earnings power and its future interest and principal outflows, which matters directly for any cash flow based valuation.
- If you'd rather focus on earnings, this one's for you. See why AAR's 21.4x P/E tells a different valuation story.
The issue now is whether AAR's current share price around US$104, viewed through its Discounted Cash Flow (DCF) intrinsic value estimate, lines up with the cash the business is expected to generate over time.
If you want to test the same cash flow question you are asking of AAR across a wider field, compare it with companies in the 42 high quality undervalued stocks
Does AAR Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash AAR Corp. can return to shareholders over time and discounts it back to today. AAR is currently generating last twelve month free cash flow of about $145 million, and the 2 Stage Free Cash Flow to Equity model assumes that this cash generation grows from that base rather than shrinking.
Those projections point to rising annual free cash flow into the next decade, which helps explain why the DCF output still comes in substantially below the current share price of $104.48. The planned $1.92b senior notes to fund the MRO Holdings deal add a meaningful layer of future interest and principal payments, so the equity cash flows in the model need to work harder to support today’s valuation. Because the MRO transaction is funded with higher cost debt, the gap between the DCF estimate and the traded price becomes easier to understand for anyone focused on cash returns. Find out what AAR could be worth using our Discounted Cash Flow (DCF) estimate.
The AAR Narrative: What Would Justify Today's Price?
Narratives pick up where the DCF puzzle leaves off for AAR Corp., by spelling out what would need to be true on growth, profitability and earnings for the stock to trade meaningfully higher or lower than it does today on Simply Wall St's Community page. Instead of stopping at a single valuation output, Narratives unpack the set of future assumptions that number relies on, so you can see how AAR's actual progress lines up with that story over time.
One of the top community narratives on AAR: 32% undervalued
"The current valuation suggests that AAR’s share price already reflects concerns about higher net leverage, cash flow conversion, and execution risk…"
Discover why this Narrative puts AAR at 32% undervalued.
One more AAR Corp. puzzle worth checking
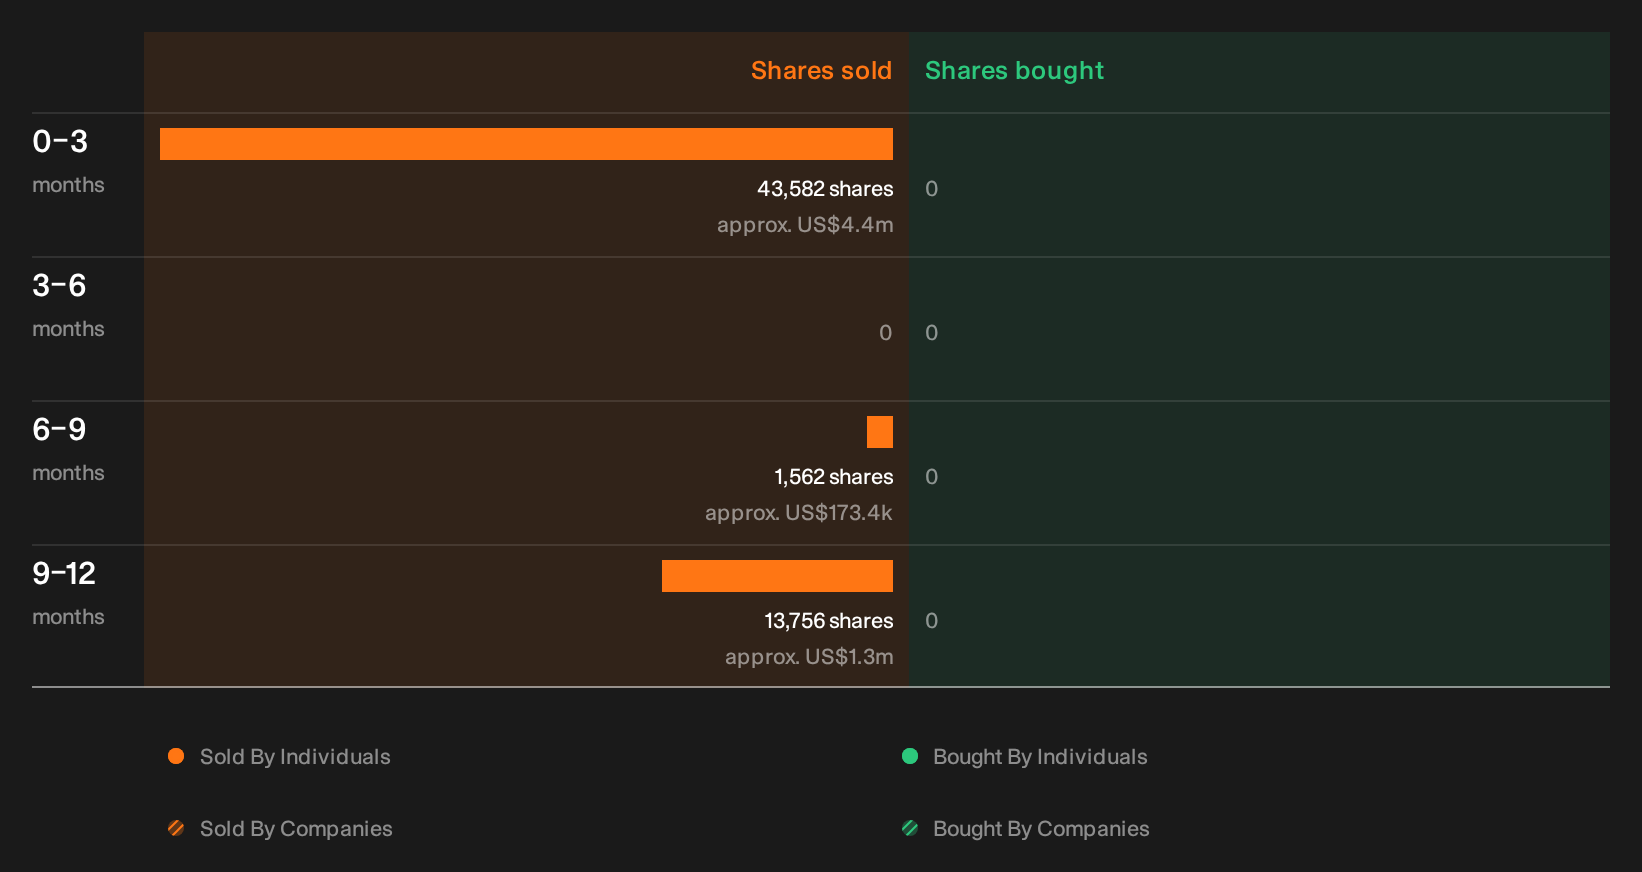
There is one last piece of the AAR Corp. picture that cash flow models cannot touch. It is what recent insider trading activity might be signalling about how those closest to the business are acting today. See the recent insider selling flagged for AAR.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com