
What Experian (LSE:EXPN)'s Vanquis Partnership Means For Shareholders
- Experian disclosed a multi year agreement with Vanquis that extends Experian data, eligibility tools, analytics and fraud prevention services across Vanquis's lending portfolio to support more robust credit decisioning and risk controls.
- The deal gives Experian another large scale outlet for its data and AI driven decisioning platforms, which can deepen client integration into core lending workflows and reinforce demand for Experian's broader credit and fraud solutions.
- The next step is to evaluate how Experian's broader investment narrative is influenced by this Vanquis data and fraud partnership.
Scan opportunities around Experian's data and credit decisioning theme by reviewing our hand picked list of solid balance sheet and fundamentals (9 results) that lean on robust credit profiles and disciplined risk controls.
Experian Investment Narrative Recap
To own Experian, you need to believe its data, analytics and AI tools keep getting embedded deeper into clients’ decision flows, and that this integration offsets pressure points in US mortgage, North America Consumer Services and any weaker Latin America B2B demand. The Vanquis deal and the RECLAIM documentary do not materially change the near term revenue catalyst, which still hinges on wider adoption of Experian’s AI and agent products.
The main operational risk remains execution. Experian needs its financial health marketplace, healthcare products and new AI platforms to carry more weight before the large North America data breach contracts roll off between Q4 FY26 and Q3 FY27. If that transition is slow, earnings and margins could undershoot current expectations.
The Vanquis partnership connects directly to Experian’s core catalyst around scaling AI driven decisioning and fraud tools. Vanquis broadens the footprint for products like RiskOS and Experian’s eligibility engines inside lending workflows. That kind of embedded usage can support revenue per client and help absorb any drag from US mortgage or contract roll offs if adoption is strong and usage is consistent.
There is a second angle investors should watch. Vanquis leans heavily on consumer credit assessment in a UK market where Experian already has deep coverage, so execution quality here becomes a reference point for other lenders that may consider shifting more of their decisioning to Experian’s cloud and AI stack. If performance, fraud outcomes and customer experience all track well, this partnership can reinforce the wider growth narrative without being a single, dominant driver on its own.
Experian's current analyst narrative points to revenues of US$10.6b and earnings of US$2.0b by 2029, based on a 7.9% yearly revenue growth rate and an increase in earnings of about US$0.5b from US$1.5b today.
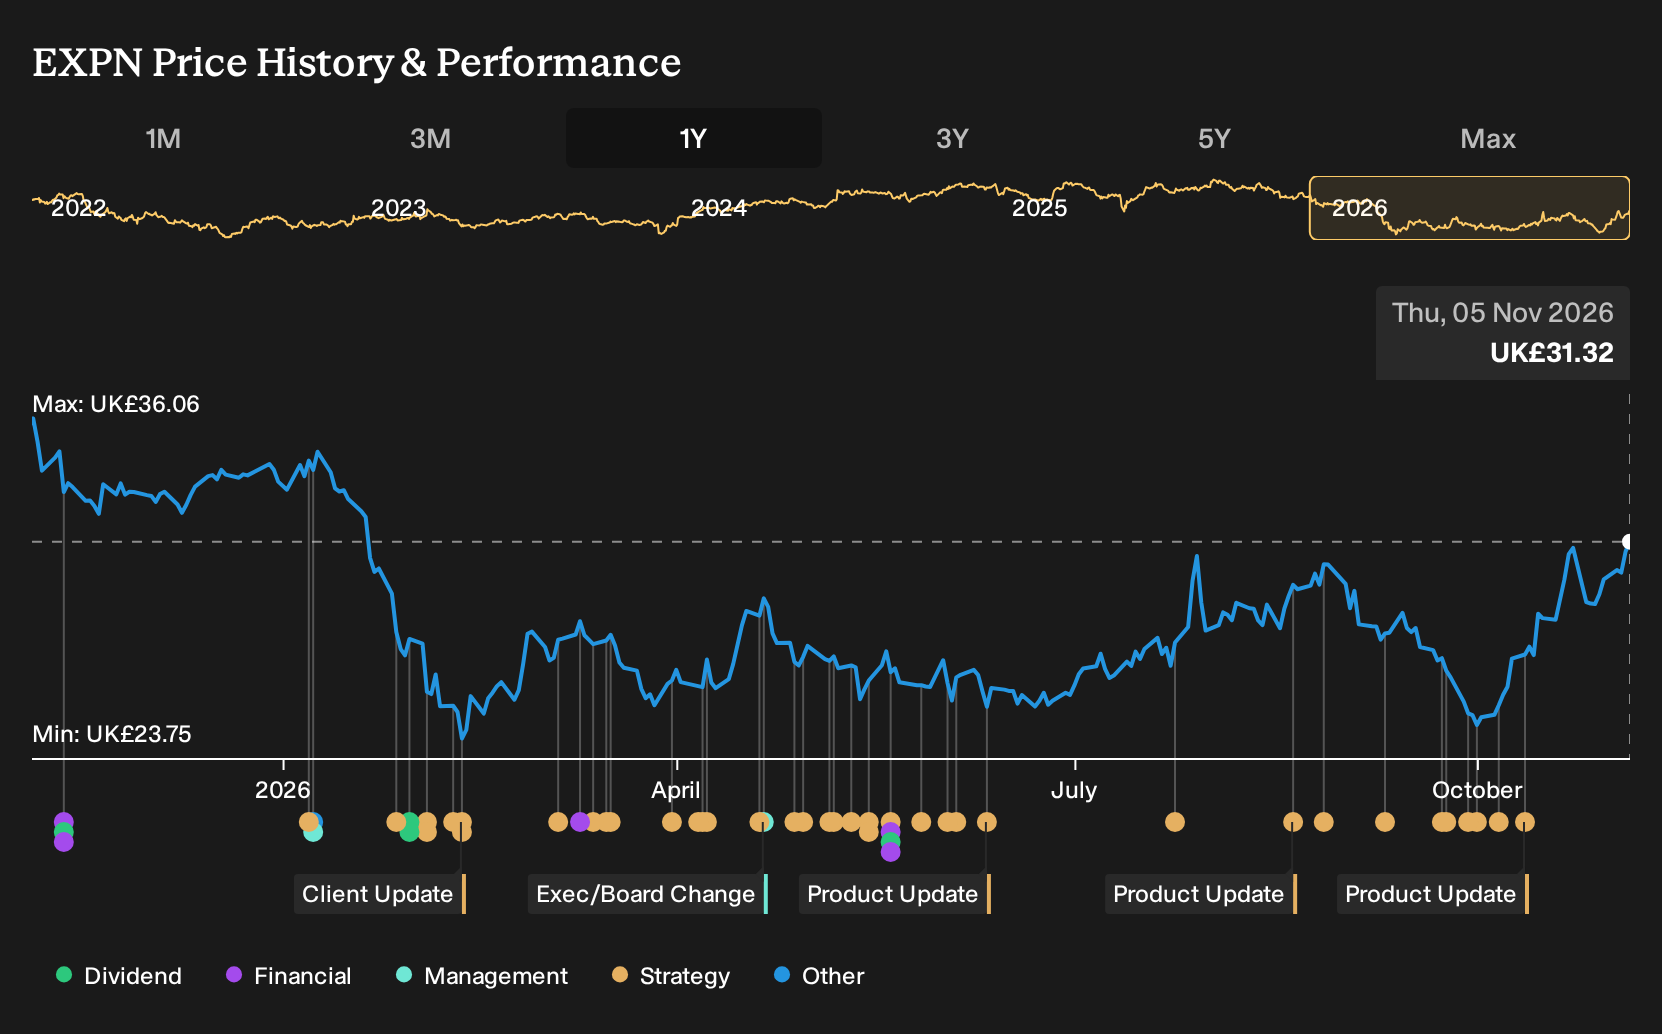
Uncover how Experian's fair value indicates a 17% potential upside to its current price, which could narrow quickly if Experian continues to execute on data and AI adoption.
Exploring Other Perspectives
One bearish twist on Experian focuses on valuation risk rather than product execution. You see analysts in this camp arguing the stock already prices in strong AI and fraud adoption, even before the Vanquis deal and RECLAIM film. Their lower case built on about US$10.4b revenue and US$2.1b earnings by 2029 looks far more cautious. Those numbers sat behind a price target near £25.62, well below consensus. Both sets of forecasts came before this week’s announcements, so treat them as starting points and explore how your own view might shift as the new partnership and brand work play through.
Explore 4 other Experian fair value estimates, including one that suggests it could be worth just £33.12.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Experian research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Experian. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Experian's overall financial health at a glance.
Looking for more investment ideas beyond Experian?
If the Experian story has sharpened your thinking on data, risk and balance sheet strength, you can use that lens across the wider market with the Simply Wall St Screener.
- For investors who care most about financial durability and low leverage, start with a list of solid balance sheet and fundamentals (9 results) that already clears high bars for balance sheet resilience.
- If you are hunting for opportunities where quality and price still appear out of sync, scan a 15 high quality undervalued stocks that combines strong fundamentals with more modest market expectations.
- Income focused readers who want yield without ignoring risk can review a 6 dividend fortresses that aims to balance payout strength with business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com