
Why Wolters Kluwer (ENXTAM:WKL) Is Getting Attention Today
Wolters Kluwer (ENXTAM:WKL) is back in focus after a run of AI-related product news and a reaffirmed 2026 outlook, which is raising fresh questions about how its software-heavy model is being valued.
Recent product launches in AI-enabled tax preparation and healthcare workflows, together with the reaffirmed 2026 outlook and ongoing share buybacks, have coincided with strong momentum in Wolters Kluwer’s share price. The 30 day share price return is 33.25% and the 90 day share price return is 31.88%, even though the 1 year total shareholder return has declined 4.18% and the 3 year total shareholder return has fallen 19.57%.
Scan beyond Wolters Kluwer and compare it with hand-picked peers that also lean heavily on software and AI by checking our 53 AI infrastructure stocks
The share price is racing ahead of the 2026 story at Wolters Kluwer. After this kind of AI-fuelled surge, investors may ask whether the current valuation still leaves enough upside to justify the risk for new money.
Most Popular Narrative: 10% Overvalued
On the most followed valuation view, Wolters Kluwer’s fair value of €84.12 sits below the recent close of €92.42. This puts the current AI-fuelled rally under pressure to justify its price.
Fair value EUR 84.1: three-stage dividend discount model (current dividend EUR 2.52, 6.5% growth for 10 years, fading to 3% over the next 10 years, 7.5% required return). Buybacks are not included, so the estimate is conservative.
See why 1 investors see Wolters Kluwer as 10% overvalued.
Result: Fair Value of €84.12 (OVERVALUED)
Still, the narrative can crack if organic growth in Health or Tax & Accounting stalls, or if Wolters Kluwer’s AI products fail to gain traction.
Find out about the key risks to this Wolters Kluwer narrative.
Another View: What P/E Says About Wolters Kluwer
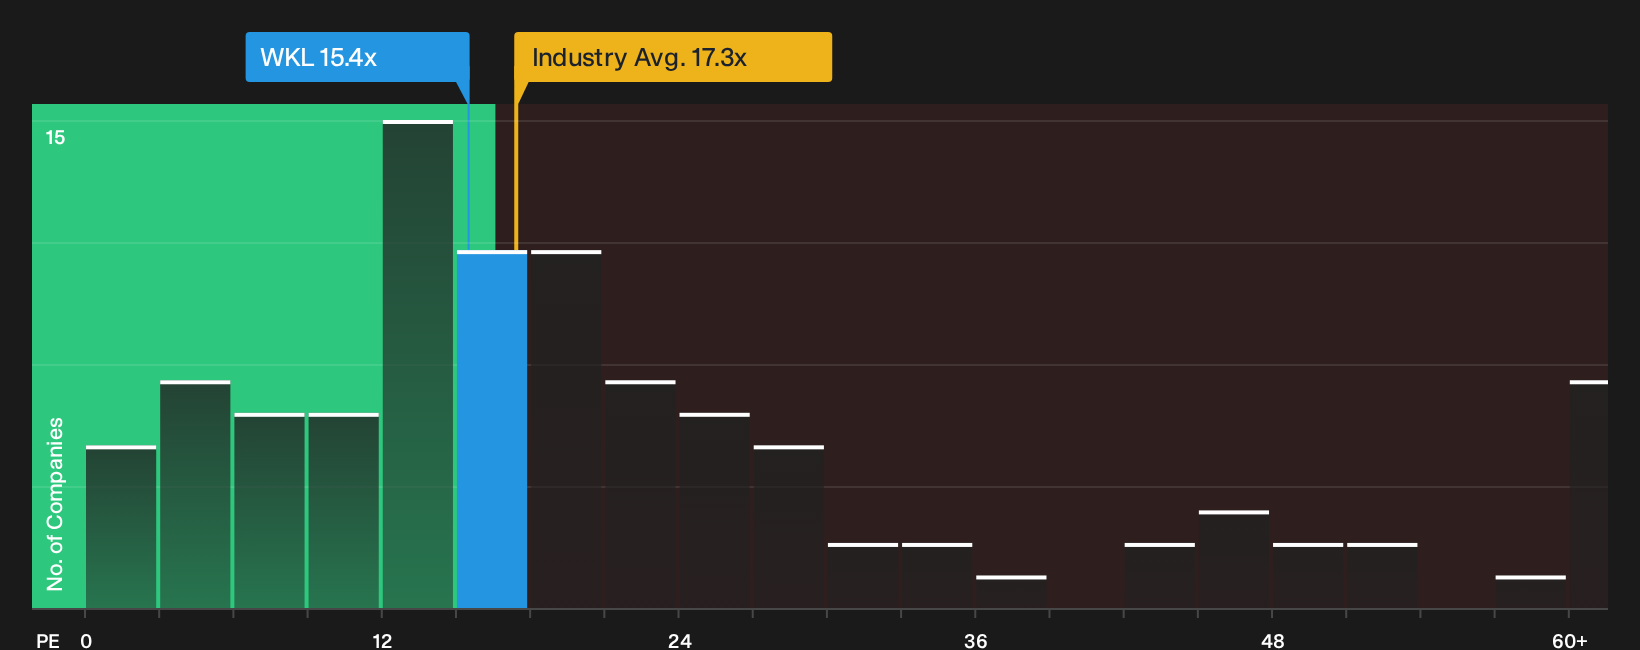
The three stage dividend model flags Wolters Kluwer as about 10% overvalued at €92.42 versus a fair value of €84.12. On earnings, the picture flips. The current P/E of 15.4x sits below the European Professional Services average of 17.3x and well under a fair ratio of 20.3x, which points to less valuation pressure and more room for sentiment to shift. Which story do you trust when both are built on the same set of cash flows and risks?
For a closer look at how the earnings based view stacks up against cash flow assumptions, take a moment to read through the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Wolters Kluwer story today. If the push and pull between risks and rewards feels uncomfortable, use that tension as a prompt to check the underlying data, stress test your own assumptions, and then weigh up the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Wolters Kluwer?
If the Wolters Kluwer story leaves you wanting a broader watchlist, use this momentum to scan fresh ideas instead of waiting on the sidelines.
- Target potential mispricing and let the data surface candidates that look cheaper than their fundamentals suggest through the 210 high quality undervalued stocks.
- Build a more resilient income stream by filtering for companies that match your yield and reliability preferences using the 215 dividend fortresses.
- Strengthen your downside protection by focusing on businesses with robust finances through the list of solid balance sheet and fundamentals (193 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com