
PagerDuty (PD) Faces A Fresh Valuation Test After Its New AI Push
PagerDuty (PD) just reshaped its pitch to investors with a fresh AI push. The firm launched Paige, a next generation SRE agent, alongside its revamped PD Reliability Platform and new PD Labs initiative.
Recent trading tells a mixed story for PagerDuty. The share price is US$16.23, with a 1-day move that declined 4.53% and a 7-day share price return down 6.62%. However, the 90-day share price return of 38.84% and year-to-date gain of 30.99% point to momentum that has built ahead of this AI launch, even as the 5-year total shareholder return of 61.03% lower highlights how long term holders have experienced a very different journey.
Scan other AI-focused operators showing similar momentum shifts with our curated list of 41 AI small caps that are leaning hard into automation and incident management use cases.
PagerDuty’s recent surge followed by a sharp pullback could be read as a verdict on the AI roadmap, or as fickle sentiment finding a new story. Which lens actually fits the current valuation?
Most Popular Narrative: 26% Overvalued
PagerDuty last closed at $16.23, while the most widely followed narrative pegs fair value at $12.86 using a 9.36% discount rate. That gap puts the recent AI excitement up against a thesis that leans heavily on flat revenue expectations and pressured profitability.
The current valuation implies the market is placing a high value on PagerDuty’s ability to convert essentially flat revenue and mid 20s non-GAAP operating margins into durable free cash flow growth, despite this narrative holding that the stock is overvalued and skewed to the downside.
See why 18 investors see PagerDuty as 26% overvalued.
Result: Fair Value of $12.86 (OVERVALUED)
Still, if PagerDuty keeps retention near recent levels and grows those US$100,000 plus and seven figure usage contracts, this bearish narrative could face meaningful pushback.
Find out about the key risks to this PagerDuty narrative.
Another View: DCF Points The Other Way
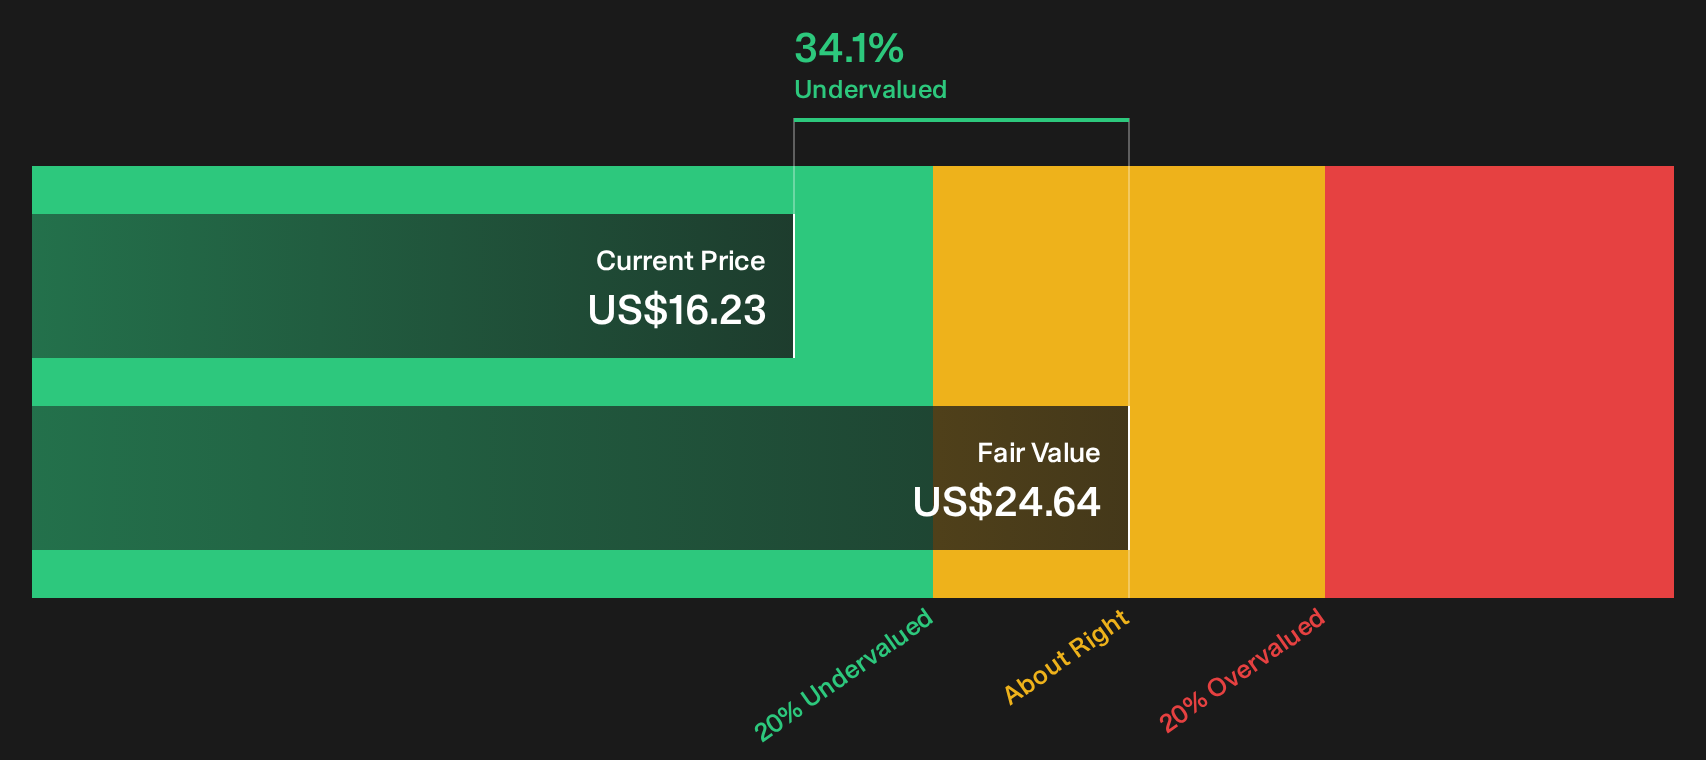
Analyst narratives lean on a fair value of $12.86 for PagerDuty, yet the Simply Wall St DCF model points to a future cash flow value of $24.64. At a $16.23 share price, that implies the stock trades about 34% below this DCF view. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Conflicted by the split views around PagerDuty and its AI push. Move quickly, stress test the thesis against the underlying data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PagerDuty?
If PagerDuty has you thinking differently about risk, return, and AI exposure, it makes sense to widen the field and pressure test your next candidates.
Use the Simply Wall St Screener to find fresh opportunities that match your style before the crowd rushes in.
- Target resilient balance sheets and temper downside risk by scanning a list of solid balance sheet and fundamentals (24 results) that filters for financial strength and cleaner fundamentals.
- Hunt for quality at a discount and compare PagerDuty with a 42 high quality undervalued stocks that focuses on strong cash flows and more conservative valuations.
- Stack potential total return by checking a 6 dividend fortresses built around higher yields and businesses that prioritize steady cash returns to shareholders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com