
Avery Dennison (AVY) Just Gave Investors Something To Reconsider
Avery Dennison (AVY) has just paired fresh quarterly results with full year earnings guidance and a confirmed dividend, giving investors new numbers to assess the stock’s current appeal and risk profile.
Avery Dennison’s latest earnings and guidance arrive after a strong recent run, with the share price gaining 12.62% over the past 30 days and 7.07% over 90 days, while the 1-year total shareholder return of 12.84% contrasts with a decline over 5 years of 6.34%.
Spot fresh momentum in Avery Dennison and then compare it with other materials names showing similar earnings traction in our hand picked 42 high quality undervalued stocks.Bulls see Avery Dennison’s recent earnings and guidance as support for the rally, while bears focus on the longer term share price drag. Which case do the current valuation numbers lean toward?
Most Popular Narrative: 6% Undervalued
Avery Dennison’s widely followed narrative pegs fair value at $201.80, a touch above the recent $189.70 close. This frames the current rally as still leaving some upside on the table if those assumptions hold.
The ongoing shift in the Materials Group toward high value categories like Specialty and Durable Labels, Embelex, Vestcom and new architectural films, while still growing core label materials, may improve mix quality and support both segment revenue and adjusted EBITDA margins over time.
Repeated use of pricing actions, material reengineering and strategic sourcing to respond to swings in raw material and wage inflation, including sequential price increases through 2026, suggests Avery Dennison has levers that can help protect net margins and earnings even as input costs move higher.
See why 14 investors see Avery Dennison as 6% undervalued.
Result: Fair Value of $201.80 (UNDERVALUED)
Still, Avery Dennison’s narrative can wobble if customer inventory prebuys unwind faster than demand or if raw material inflation squeezes margins more than expected.
Find out about the key risks to this Avery Dennison narrative.
Another View: Avery Dennison Through The P/E Lens
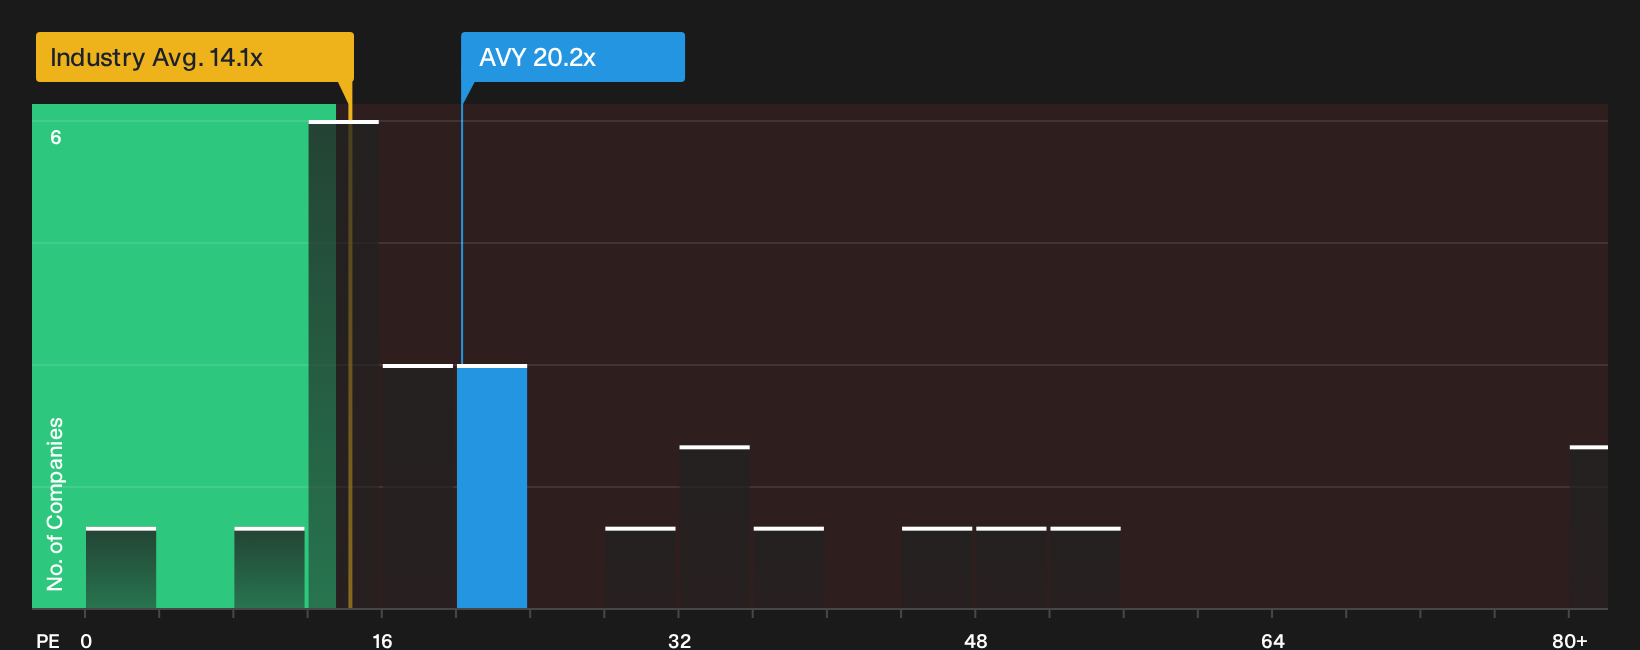
The fair value narrative at $201.80 paints Avery Dennison as 6% undervalued. The P/E ratio tells a tougher story. At 20.2x earnings, the stock trades richer than the global Packaging industry on 14.1x and above its own fair ratio of 18.2x. This raises the question of how much mispricing is really left.
Investors weighing this richer multiple against the fair ratio and sector level pricing may want to stress test their own earnings and cash return assumptions before deciding which version of value feels more realistic over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Getting mixed signals from Avery Dennison’s story so far is normal, especially with both risks and bright spots in play. Move quickly, review the underlying data and pressure test your own expectations against the 4 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Avery Dennison?
If Avery Dennison has sharpened your focus on quality, do not stop here. Cast a wider net so you are not missing stronger fits for your watchlist.
- Target resilient balance sheets and steady fundamentals using the list of solid balance sheet and fundamentals (25 results) to surface companies that may better match your comfort with financial strength.
- Hunt for potential mispricing by scanning the 21 high quality undiscovered gems so you spot strong businesses before the crowd pays attention.
- Lock in a shortlist of reliable income candidates through the 6 dividend fortresses and keep your cash flow options open.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com